The UK Financial Conduct Authority (FCA) has dropped plans to make climate reporting mandatory for listed companies, instead adopting a comply-or-explain approach under the UK’s new Sustainability Reporting Standards. The framework is based on international sustainability standards and will apply to accounting periods beginning on or after 1 January 2027, with first reporting expected in 2028.
Key Overview
- The FCA has moved away from mandatory climate reporting.
- Listed companies will use a comply-or-explain approach.
- The framework is based on UK Sustainability Reporting Standards.
- The standards align with IFRS S1 and IFRS S2.
- The rules apply from 1 January 2027.
- First reporting is expected in 2028.
- Companies receive transitional relief for Scope 3 and wider sustainability disclosures.
- The change follows concerns about reporting costs and regulatory burdens.
FCA Moves Away From Mandatory Climate Reporting
The UK’s Financial Conduct Authority has changed its approach to climate and sustainability reporting for listed companies.
Instead of requiring mandatory climate disclosures under the new framework, the regulator will apply a comply-or-explain approach across the UK’s Sustainability Reporting Standards.
Under this model, companies can provide the relevant disclosures or explain why they have not done so.
The change follows feedback from businesses concerning the costs and practical challenges associated with mandatory reporting, as well as concerns about the competitiveness of the UK as a listing destination.
Climate Reporting Is Not Being Removed
The FCA’s decision does not eliminate climate and sustainability reporting requirements.
Listed companies will report against the UK Sustainability Reporting Standards, with flexibility built into the framework.
The standards are based on the International Sustainability Standards Board’s IFRS S1 and IFRS S2 standards, covering sustainability-related and climate-related financial disclosures.
The framework is intended to provide investors with information about financially material sustainability and climate-related risks and opportunities.
Rules Begin in 2027
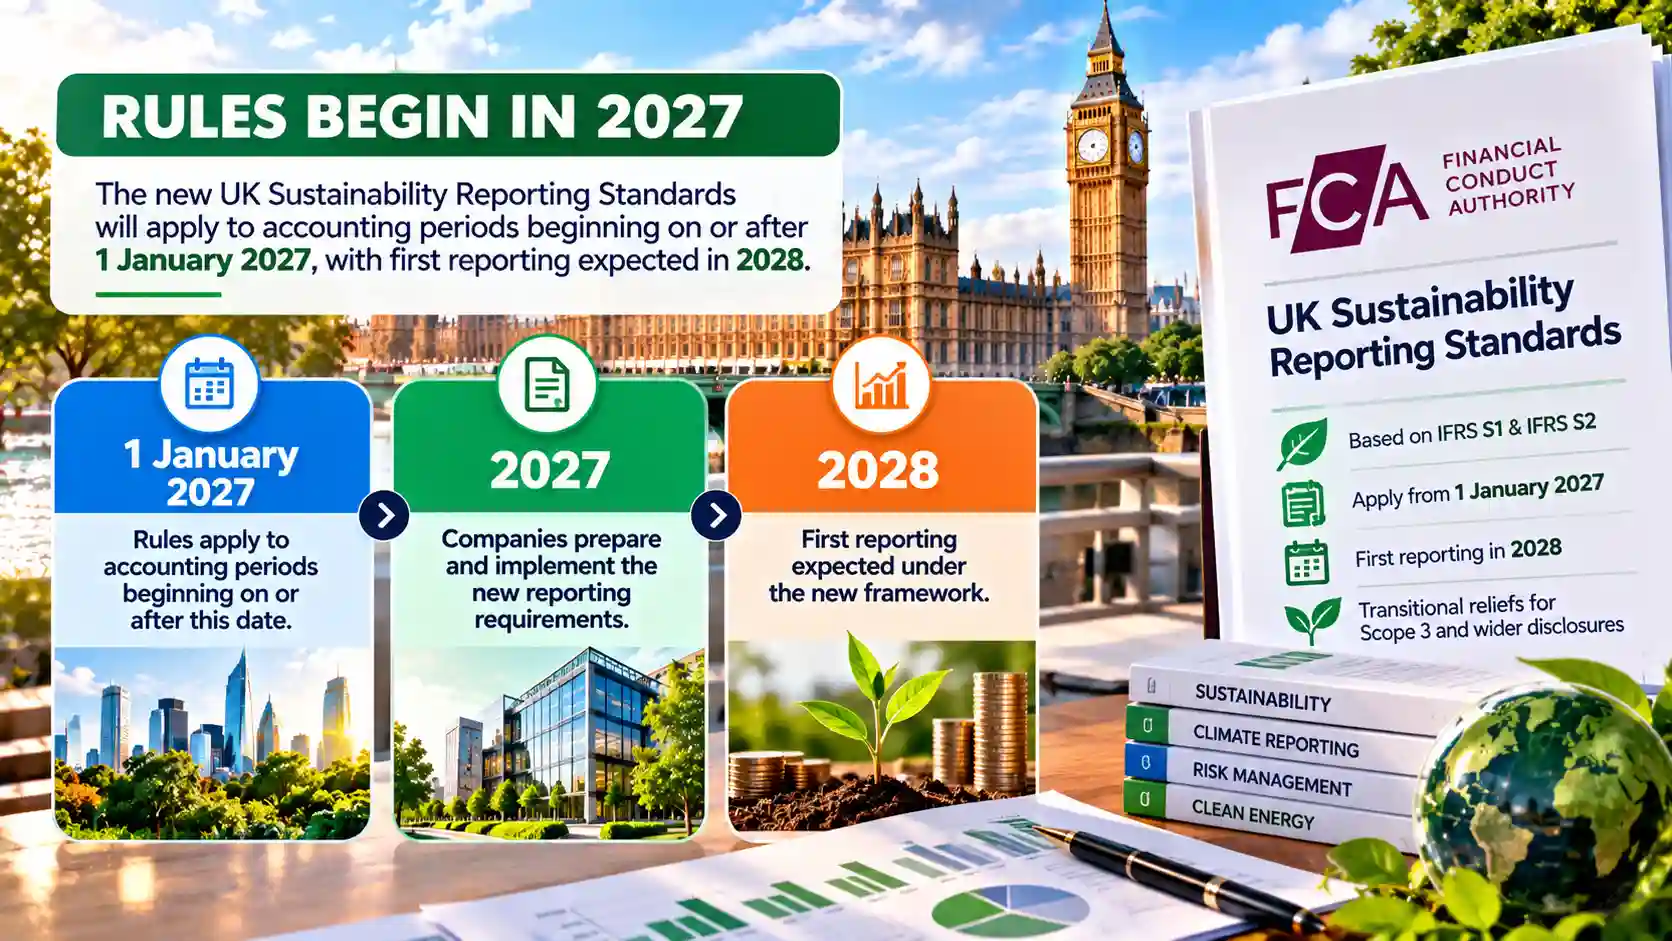
The revised requirements will apply to accounting periods beginning on or after January 1, 2027.
Companies are expected to begin their first reporting under the new framework in 2028.
The FCA has also introduced transitional reliefs to give businesses more time to implement certain requirements.
Companies will receive one year for Scope 3 emissions disclosures, while wider sustainability disclosures under UK SRS S1 will receive a two-year transitional period.
Why the FCA Changed Its Approach
Concerns about the cost and complexity of climate reporting were central to the change.
Smaller listed companies in particular raised concerns about the resources required to produce detailed climate and sustainability disclosures.
The FCA also considered the potential impact of mandatory requirements on the UK’s competitiveness as a listing venue.
The regulator said companies have different business models and levels of exposure to climate and sustainability risks, meaning the relevance of individual disclosures can vary.
The comply-or-explain model is intended to provide greater flexibility while maintaining a common reporting framework.
Existing Climate Disclosure Levels
The FCA’s review of FTSE 350 companies’ 2025 annual reports found that 92 per cent complied with the existing Task Force on Climate-related Financial Disclosures framework.
This indicates that a large proportion of major listed companies were already providing climate-related information.
The FCA is therefore retaining climate and sustainability reporting expectations while changing how strictly individual disclosures must be provided.
Context is everything. Stay ahead of shifting trends with today’s market updates, and uncover emerging opportunities using the Serrari Group Market Index and Marketplace. Then, take control of your own financial future by exploring our Money & Life Reset Transformation Blueprint ™ to build stronger habits, create better systems, and design a path toward lasting wealth.
Scope 3 Reporting Gets More Time
Scope 3 emissions reporting will receive a specific transitional period under the new framework.
Companies can defer the relevant Scope 3 disclosure requirements for one year.
Wider sustainability disclosures under UK SRS S1 will receive a two-year transitional period.
The additional time is intended to help companies develop the systems needed to collect, assess and report sustainability information.
Guidance and Implementation
The FCA is also consulting on guidance to help companies implement the new framework.
The consultation includes guidance on applying the comply-or-explain approach proportionately.
Feedback is due by 28 October 2026.
The FCA has also scheduled a webinar to explain the updated sustainability disclosure requirements and proposed implementation guidance.
What It Means for Investors
The move towards comply-or-explain reporting gives companies greater flexibility, but it also places greater importance on the explanations provided when disclosures are not made.
Investors will continue to need reliable information to assess financially material climate and sustainability risks.
The FCA’s approach seeks to balance the cost of reporting for companies with the need for decision-useful information for investors.
The shift also brings UK reporting closer to international sustainability disclosure standards through the adoption of IFRS-based requirements.
Outlook
The FCA’s decision changes how UK-listed companies will approach climate and sustainability reporting from 2027.
Mandatory climate reporting under the original proposal has been replaced with a comply-or-explain approach covering the wider UK Sustainability Reporting Standards framework.
The rules will apply to accounting periods beginning on or after 1 January 2027, with first reporting expected in 2028. Transitional reliefs will provide additional time for Scope 3 and wider sustainability disclosures.
For companies, the framework offers greater flexibility. For investors, the focus will remain on whether disclosures provide consistent and decision-useful information about financially material climate and sustainability risks.
FAQs
1. What has the FCA changed?
The FCA has moved away from mandatory climate reporting and will instead use a comply-or-explain approach across the UK Sustainability Reporting Standards.
2. When will the new rules apply?
The rules apply to accounting periods beginning on or after 1 January 2027, with first reporting expected in 2028.
3. What are UK Sustainability Reporting Standards?
They are the UK’s sustainability reporting standards based on the International Sustainability Standards Board’s standards, including IFRS S1 and IFRS S2.
4. Why did the FCA change its approach?
The change followed concerns about reporting costs, the burden on smaller companies and the potential impact of mandatory requirements on UK listing competitiveness.
Your financial future isn’t something you wait for—it’s something you build.
The real question is: when do you begin?
Move beyond simply staying informed.
Navigate the markets with clarity—track trends through the Serrari Group Market Index, uncover opportunities in the Serrari Marketplace, and build practical knowledge with our Curated Wealth Builder Platform.
Stay connected to what truly matters.
Get daily insights on macro trends and financial movements across Kenya, Africa, and global markets—delivered through the Serrari Newsletter.
Growth opens doors.
Advance your career through professional programs including ACCA, HESI A2, ATI TEAS 7 , HESI EXIT , NCLEX – RN and NCLEX – PN, Financial Literacy!🌟—designed to move you forward with confidence.
See where money is flowing—clearly and in real time.
Track Money Market Funds, Treasury Bills, Treasury Bonds, Green Bonds, and Fixed Deposits, alongside global and African indexes, key economic indicators, and the evolving Crypto and stablecoin landscape—all within Serrari’s Market Index.