Canada’s housing market recorded a marginal recovery in October 2026, with national home sales increasing by 0.3% from September. However, activity remained 10.6% below October 2025, highlighting continued weakness in the property market. The Canadian Real Estate Association (CREA) reported that the national home price measure stood at C$656,200, down 3.1% from a year earlier, despite a 0.1% monthly increase. The Bank of Canada’s decision to raise its benchmark interest rate to 2.5% in October has added uncertainty for prospective buyers, while listings increased by 0.8% and national housing inventory reached approximately five months.
Key Takeaways
- Canadian home sales increased by 0.3% month over month in October 2026.
- Sales remained 10.6% lower than in October 2025.
- The reported national home price measure was C$656,200, down 3.1% year over year.
- The Bank of Canada raised its policy interest rate by 25 basis points to 2.5% on October 28.
- Newly listed properties increased by 0.8% between September and October.
- Approximately 197,000 properties were listed for sale nationally at the end of October.
- National housing inventory stood at around five months, broadly in line with its long-term average.
Why Did Canadian Home Sales Increase Slightly in October?
Canada’s housing market recorded a modest increase in home sales in October, offering a small improvement after weaker activity in the preceding months. However, the recovery remains limited, with transactions still significantly below levels recorded a year earlier.
According to the Canadian Real Estate Association (CREA), national sales in October were up 0.3 per cent month over month, while actual sales on an unadjusted basis were down 10.6% compared with October 2025.
The monthly increase partially reversed the 2.3% decline recorded in September and the 0.7% drop in August.
The relatively stable activity surprised some market observers, who had expected sales to weaken further towards the end of the year following the Bank of Canada’s latest interest rate increase.
CREA senior economist Shaun Cathcart said there had been little change in activity between September and October, despite expectations of a more significant slowdown.
“Not much activity between September and October,” Cathcart said. “But the remarkable part about that is that it ran counter to … a lot of analysts’ — including ours — expectations.”
The figures suggest that prospective buyers have not withdrawn from the market as sharply as some forecasters anticipated. Nevertheless, the annual decline indicates that Canada’s housing market is still operating below the activity levels recorded in 2025.
How Are Higher Interest Rates Affecting Canada’s Housing Market?
The Bank of Canada’s monetary policy decisions remain an important factor influencing housing market activity.
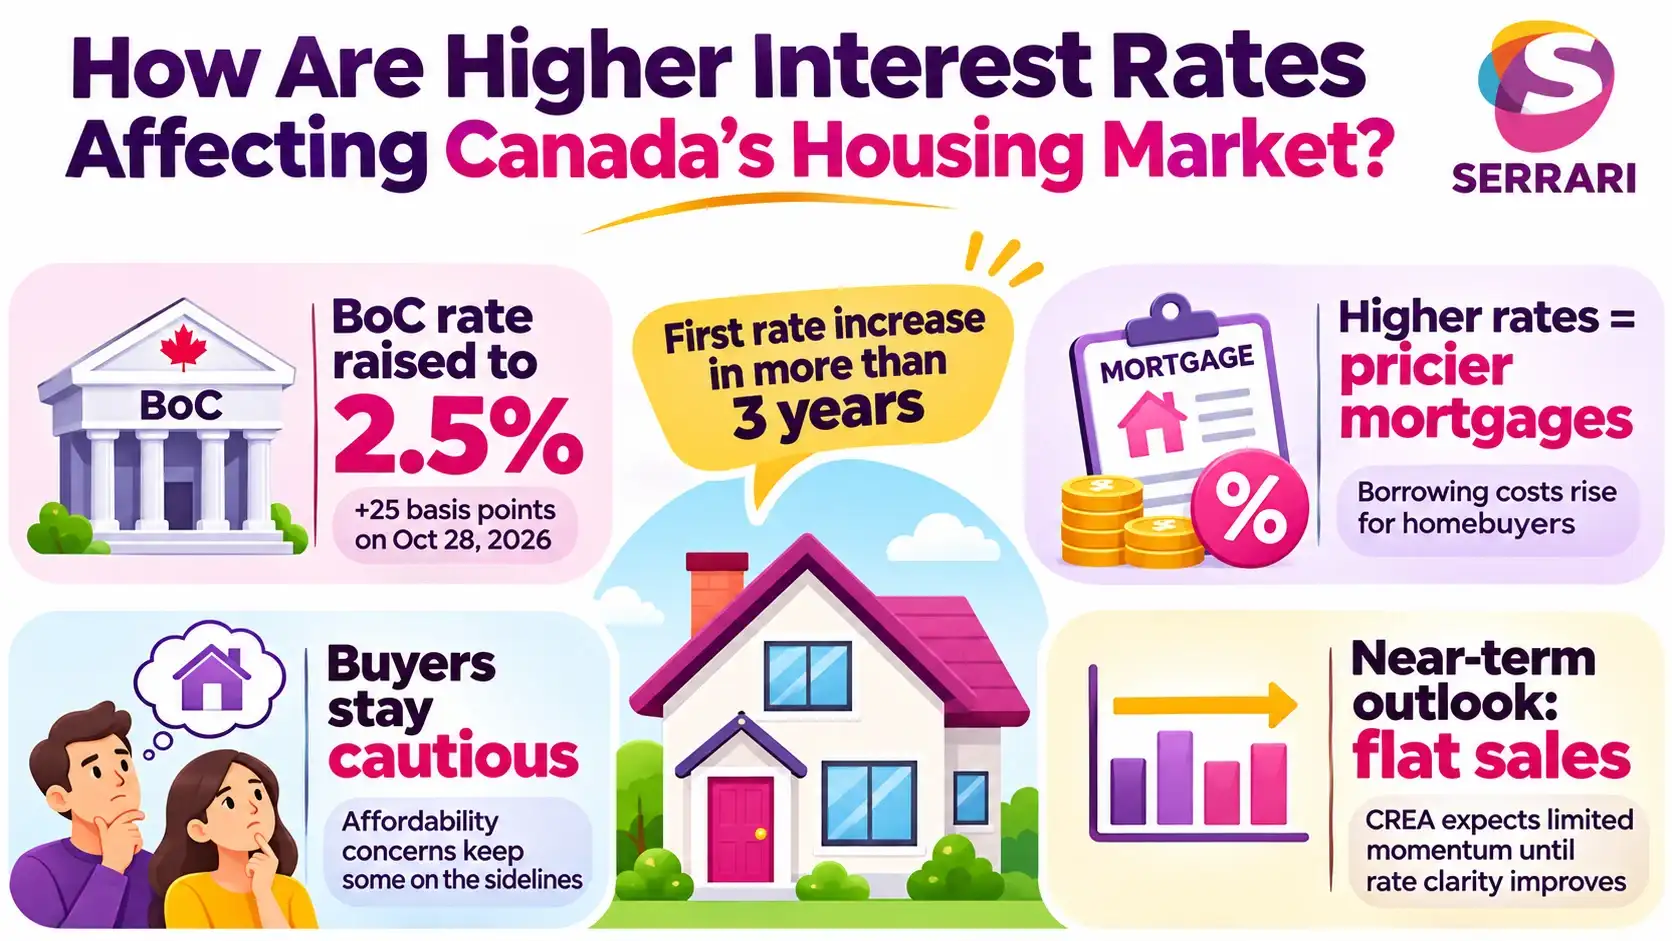
On October 28, 2026, the central bank increased its benchmark overnight interest rate by 25 basis points to 2.5%. This marked the first rate increase in more than three years and the first adjustment in a year.
Higher interest rates can increase borrowing costs, making mortgages more expensive for prospective homeowners. Buyers considering property purchases may therefore delay their decisions while assessing whether further rate increases could affect their monthly repayments.
The rate increase has raised concerns among cost-conscious potential buyers about the possibility of higher mortgage payments, keeping some of them on the sidelines.
Cathcart expects national sales to remain relatively flat over the coming months as buyers wait for greater clarity on the direction of interest rates.
He suggested that if the number of further increases remains limited and borrowing conditions become more predictable, the housing market could regain momentum next year.
However, the outlook remains uncertain, particularly as affordability concerns continue to influence purchasing decisions.
The central bank’s preferred measures of underlying inflation have remained relatively subdued, despite pressure from higher energy prices. CREA’s senior economist therefore suggested that the current tightening cycle is unlikely to resemble the more aggressive rate increases experienced in 2022.
This distinction matters because the scale and pace of interest rate increases influence how households approach mortgage borrowing and property purchases.
Context is everything. Stay ahead of shifting trends with today’s market updates, and uncover emerging opportunities using the Serrari Group Market Index and Marketplace. Then, take control of your own financial future by exploring our Money & Life Reset Transformation Blueprint ™ to build stronger habits, create better systems, and design a path toward lasting wealth.
What Happened to Canadian Home Prices in October?
Home prices recorded a small monthly increase in October, although values remained below their levels a year earlier.
The reported national home price measure stood at approximately C$656,200, equivalent to around US$459,000. This represented a 0.1% increase from September but remained 3.1% lower than the corresponding period in 2025.
The monthly increase in benchmark house prices was the largest in more than two years, although it was not enough to reverse the broader annual decline.
Benchmark home prices remained 3.1% from 12 months ago, reflecting continued weakness in Canada’s property market.
The price movement suggests that the market is showing some signs of stabilisation, but the recovery remains uneven.
CREA’s figures also indicate that the annual decline in benchmark prices was softer than the 7.7% retreat recorded in September and smaller than several other readings reported during 2026.
However, buyers and sellers are still operating in a market shaped by affordability pressures and uncertainty over future borrowing costs.
It is also important to distinguish between the reported national price measure and the benchmark house price index. These are different ways of measuring property prices, even where the reported figures are similar.
Which Canadian Regions Are Experiencing Stronger Housing Activity?
Housing market conditions vary across Canada, with some regions experiencing stronger activity than others.
Ontario and British Columbia continue to record relatively slow housing market conditions, while the Prairie provinces and parts of Canada’s East Coast have been performing more strongly.
Cathcart noted that the Prairie and Eastern Canadian markets had been “hotter” than many people might realise.
These regional differences highlight why national housing figures do not necessarily reflect conditions in every province or city.
Markets with stronger local demand may experience more resilient sales activity, while areas facing affordability pressures or weaker buyer confidence may continue to record slower transactions.
However, the national outlook could become more subdued if higher borrowing costs influence purchasing decisions across additional regions.
Are More Homes Becoming Available for Sale?
Housing supply increased slightly in October, providing prospective buyers with more properties to consider.
Newly listed properties increased by 0.8% between September and October, while approximately 197,000 homes were available through Canadian real estate boards at the end of the month.
This was slightly above the long-term average of approximately 190,000 listings.
The country also recorded around five months of housing inventory, a measure of how long it would take to sell the available properties at the prevailing pace of sales if no additional listings entered the market.
The inventory level was slightly higher than during the summer but remained broadly in line with its longer-term average.
The increase in available properties could give buyers more choice and reduce some of the pressure associated with limited housing supply.
However, the effect on prices will depend on how listings and buyer demand develop over the coming months.
If sales remain weak while available properties increase, sellers may face greater pressure to adjust asking prices to attract buyers.
How Could Government Housing Policies Influence the Market?
Government housing policies are another factor shaping Canada’s property market.
The federal government has proposed easing restrictions under the foreign buyer ban to allow purchases of newly built homes, while also putting forward a plan to extend the ban until January 1, 2029.
The proposed approach is intended to maintain restrictions on foreign purchases across most of the existing housing market while allowing additional investment in newly constructed properties.
The government’s budget document stated that the measure would help protect housing affordability while unlocking additional investment in new housing supply.
The potential policy changes could influence the level of investment entering Canada’s residential construction market.
However, their actual effect will depend on implementation, investor response and whether additional investment translates into more completed homes.
For a housing market dealing with weak sales and affordability concerns, increasing supply remains an important consideration alongside mortgage costs and buyer confidence.
The Bigger Picture: Canada’s Housing Market Is Struggling to Regain Momentum
October’s figures illustrate the challenges facing Canada’s residential property market as it enters the traditionally quieter winter period.
Although monthly sales increased slightly, the 10.6% annual decline indicates that the market has yet to return to the activity levels recorded in 2025.
Higher interest rates, concerns about mortgage affordability and uncertainty over future borrowing costs continue to influence buyer behaviour.
At the same time, the increase in property listings and the availability of approximately five months of housing inventory suggest that supply is not currently as constrained as it can be in tighter housing markets.
The differences between Ontario and British Columbia and the stronger-performing Prairie and East Coast markets also demonstrate that Canada’s housing conditions are not uniform.
For investors, developers and prospective homeowners, these trends highlight the importance of monitoring regional conditions rather than relying exclusively on national averages.
Why Does This Matter Now?
The October housing figures come shortly after the Bank of Canada’s decision to raise its benchmark interest rate to 2.5%, introducing further uncertainty into an already subdued property market.
For prospective buyers, the possibility of higher mortgage repayments could influence whether they purchase immediately or wait for clearer signals about future interest rates.
For homeowners and sellers, relatively weak annual sales and increased listings could affect the time required to sell properties and the prices buyers are willing to pay.
For developers and investors, the proposed changes to foreign buyer restrictions could create opportunities in newly built housing, although the impact will depend on how the policies are implemented.
The combination of borrowing costs, housing supply and regional differences will therefore remain important in determining the direction of Canada’s property market.
Outlook: Will Canada’s Housing Market Recover in 2027?
Canada’s housing market is showing limited signs of stabilisation, but October’s 0.3% increase in monthly sales does not yet indicate a broad recovery.
CREA expects sales to remain relatively flat nationally in the coming months as potential buyers wait for greater certainty about interest rates.
The direction of monetary policy will be particularly important. If borrowing costs become more predictable and buyers regain confidence, housing activity could strengthen next year.
However, continued affordability pressures and the possibility of further interest rate increases could delay that recovery.
The next developments to watch include changes in mortgage borrowing costs, monthly sales activity, property listings and regional home prices.
Ultimately, Canada’s housing market will need stronger buyer confidence and more predictable financing conditions to move beyond its current period of subdued activity.
Frequently Asked Questions (FAQs)
1. How much did Canadian home sales increase in October 2026?
National home sales increased by 0.3% from September 2026, although actual sales remained 10.6% lower than in October 2025.
2. What was the average home price in Canada in October 2026?
The reported national home price measure was approximately C$656,200, equivalent to around US$459,000. It increased by 0.1% month over month but was 3.1% lower than a year earlier.
3. Why are higher interest rates affecting Canadian home sales?
Higher interest rates can increase mortgage borrowing costs and monthly repayments, making property purchases less affordable and encouraging some prospective buyers to delay their decisions.
4. How many homes were available for sale in Canada in October 2026?
Approximately 197,000 properties were listed for sale across Canadian real estate boards at the end of October, slightly above the long-term average of around 190,000.
Your financial future isn’t something you wait for—it’s something you build.
The real question is: when do you begin?
Move beyond simply staying informed.
Navigate the markets with clarity—track trends through the Serrari Group Market Index, uncover opportunities in the Serrari Marketplace, and build practical knowledge with our Curated Wealth Builder Platform.
Stay connected to what truly matters.
Get daily insights on macro trends and financial movements across Kenya, Africa, and global markets—delivered through the Serrari Newsletter.
Growth opens doors.
Advance your career through professional programs including ACCA, HESI A2, ATI TEAS 7 , HESI EXIT , NCLEX – RN and NCLEX – PN, Financial Literacy!🌟—designed to move you forward with confidence.
See where money is flowing—clearly and in real time.
Track Money Market Funds, Treasury Bills, Treasury Bonds, Green Bonds, and Fixed Deposits, alongside global and African indexes, key economic indicators, and the evolving Crypto and stablecoin landscape—all within Serrari’s Market Index.