

U.S. equities advanced on Monday, October 5, with the S&P 500 moving to within 0.3% of its all-time high and the Nasdaq Composite setting another record. Major acquisition announcements involving PTC and RXO boosted sentiment, while gains in artificial-intelligence-linked stocks including Nvidia and Broadcom added momentum.
Investors nevertheless faced a complicated backdrop of elevated Treasury yields, oil prices near $100 a barrel and signs that inflation pressures remain persistent. Attention is now shifting toward third-quarter corporate earnings and the Federal Reserve’s next interest-rate decisions.
Key Overview
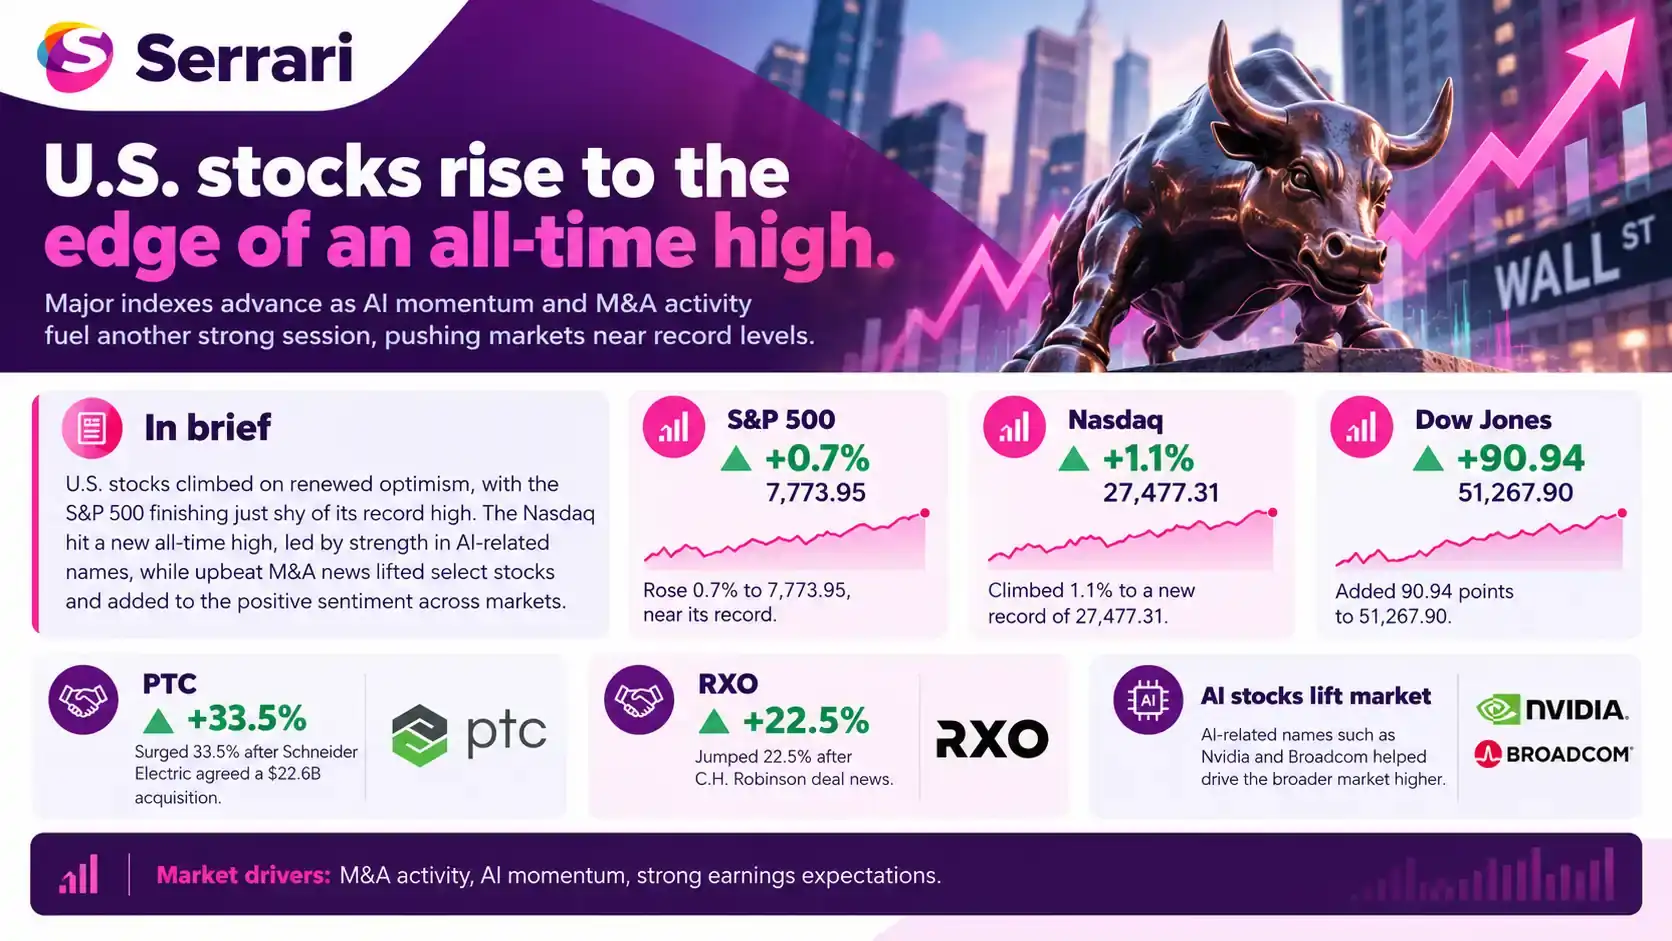
- The S&P 500 gained 0.7% to close at 7,773.95, just 0.3% below its record.
- The Nasdaq Composite climbed 1.1% to a record 27,477.31.
- The Dow Jones Industrial Average added 90.94 points, or about 0.2%, to 51,267.90.
- PTC surged 33.5% following a $22.6 billion takeover agreement with Schneider Electric.
- RXO jumped 22.5% after C.H. Robinson announced a roughly $5.8 billion acquisition.
- Nvidia and Broadcom each gained 2.1%, strengthening the technology-led rally.
- S&P 500 earnings are currently projected to grow 29.5% year over year in the third quarter.
- The 10-year U.S. Treasury yield rose to 5.31%, while Brent crude settled at $100.32 a barrel.
Takeover Deals and AI Stocks Power Market Gains
The S&P 500 rose 0.7% to 7,773.95, leaving the benchmark only 0.3% below the record reached during the summer. The Nasdaq Composite gained 1.1% to 27,477.31, establishing a fresh closing record, while the Dow gained 90.94 points to 51,267.90.
Corporate dealmaking played an important role in Monday’s rally. PTC shares soared 33.5% after Schneider Electric agreed to acquire the industrial software company through a $205-per-share all-cash transaction valuing PTC’s equity at approximately $22.6 billion. The transaction carries an implied enterprise value of about $23.7 billion.
The announcement also supported other software stocks as investors considered the potential value of industrial software and AI-enabled technologies. Autodesk climbed 4.5%.
RXO jumped 22.5% after C.H. Robinson announced an acquisition valued at roughly $5.8 billion. Under the standard structure, RXO shareholders would receive $17.25 in cash plus 0.0856 C.H. Robinson shares for each RXO share, representing implied consideration of $30.25 per share based on the agreed valuation methodology. Investors can also elect cash or stock alternatives, subject to proration.
AI remained another major market driver. Nvidia rose 2.1% and was one of the strongest contributors to the S&P 500’s advance, while Broadcom also gained 2.1%. The strength highlights how enthusiasm around AI infrastructure, computing and enterprise adoption continues to influence broader market valuations.
Context is everything. Stay ahead of shifting trends with today’s market updates, and uncover emerging opportunities using the Serrari Group Market Index and Marketplace. Then, take control of your own financial future by exploring our Money & Life Reset Transformation Blueprint ™ to build stronger habits, create better systems, and design a path toward lasting wealth.
Strong Earnings Expectations Support Elevated Valuations
Investors are now preparing for the third-quarter earnings season, with expectations unusually strong.
Current estimates indicate that S&P 500 earnings could grow 29.5% from a year earlier during the July-to-September quarter. At the beginning of the quarter, projected growth stood at 26.7%, meaning analysts have actually raised estimates as the reporting season approaches.
If the 29.5% estimate is achieved, it would mark the third consecutive quarter in which S&P 500 earnings growth exceeded 25% and the eighth consecutive quarter of double-digit profit growth.
Positive corporate guidance has also been unusually widespread. Of 116 S&P 500 companies that had issued earnings-per-share guidance ahead of the season, 72 provided positive guidance, significantly above historical averages.
That earnings strength has helped equities remain near record levels despite pressure from higher interest rates, inflation and geopolitical uncertainty.
Treasury Yields and Inflation Remain Key Risks
The bond market remains a significant challenge for stocks. The benchmark 10-year Treasury yield climbed to 5.31% on Monday and briefly approached 5.35%, placing borrowing costs near levels not seen since 2002.
Higher Treasury yields can pressure equity valuations because bonds become more attractive relative to stocks while mortgages, business loans and other forms of financing become more expensive.
Inflation risks are also proving difficult to dismiss. September’s U.S. services activity remained in expansion territory, with the Services PMI registering 54.9% for the 27th consecutive month of expansion.
More importantly for monetary policy, the services Prices Index increased to 74.0%, up from 72.6% in August and its highest reading since July 2022. That indicates businesses are continuing to face substantial increases in the prices of materials and services.
The Federal Reserve raised its target range by 25 basis points in September, taking the federal funds rate to 3.75%-4.00%. Expectations for an immediate October increase have since weakened following softer employment data, although financial markets continue to see a meaningful possibility of another increase before year-end.
Oil Volatility Adds Another Layer of Uncertainty
Energy markets remain another source of risk. Brent crude settled at $100.32 a barrel after moving between roughly $100 and $103 during Monday’s trading.
Prices remain sensitive to Middle East supply disruptions and the continuing conflict involving Iran, although increased regional exports and emergency stock releases have provided some relief.
For equity investors, sustained oil prices around or above $100 could complicate the outlook by increasing transportation, manufacturing and consumer costs, potentially reinforcing inflation at a time when interest rates are already elevated.
Despite those risks, U.S. equities continue to display resilience. Strong corporate profits, takeover activity and continued enthusiasm around AI have kept the major indexes close to historic highs. The next test will be whether upcoming earnings results are strong enough to justify those valuations while bond yields and inflation remain elevated.
Sources: Associated Press / PTC / RXO / FactSet / Institute for Supply Management / Federal Reserve / Reuters
Your financial future isn’t something you wait for—it’s something you build.
The real question is: when do you begin?
Move beyond simply staying informed.
Navigate the markets with clarity—track trends through the Serrari Group Market Index, uncover opportunities in the Serrari Marketplace, and build practical knowledge with our Curated Wealth Builder Platform.
Stay connected to what truly matters.
Get daily insights on macro trends and financial movements across Kenya, Africa, and global markets—delivered through the Serrari Newsletter.
Growth opens doors.
Advance your career through professional programs including ACCA, HESI A2, ATI TEAS 7 , HESI EXIT , NCLEX – RN and NCLEX – PN, Financial Literacy!🌟—designed to move you forward with confidence.
See where money is flowing—clearly and in real time.
Track Money Market Funds, Treasury Bills, Treasury Bonds, Green Bonds, and Fixed Deposits, alongside global and African indexes, key economic indicators, and the evolving Crypto and stablecoin landscape—all within Serrari’s Market Index.