

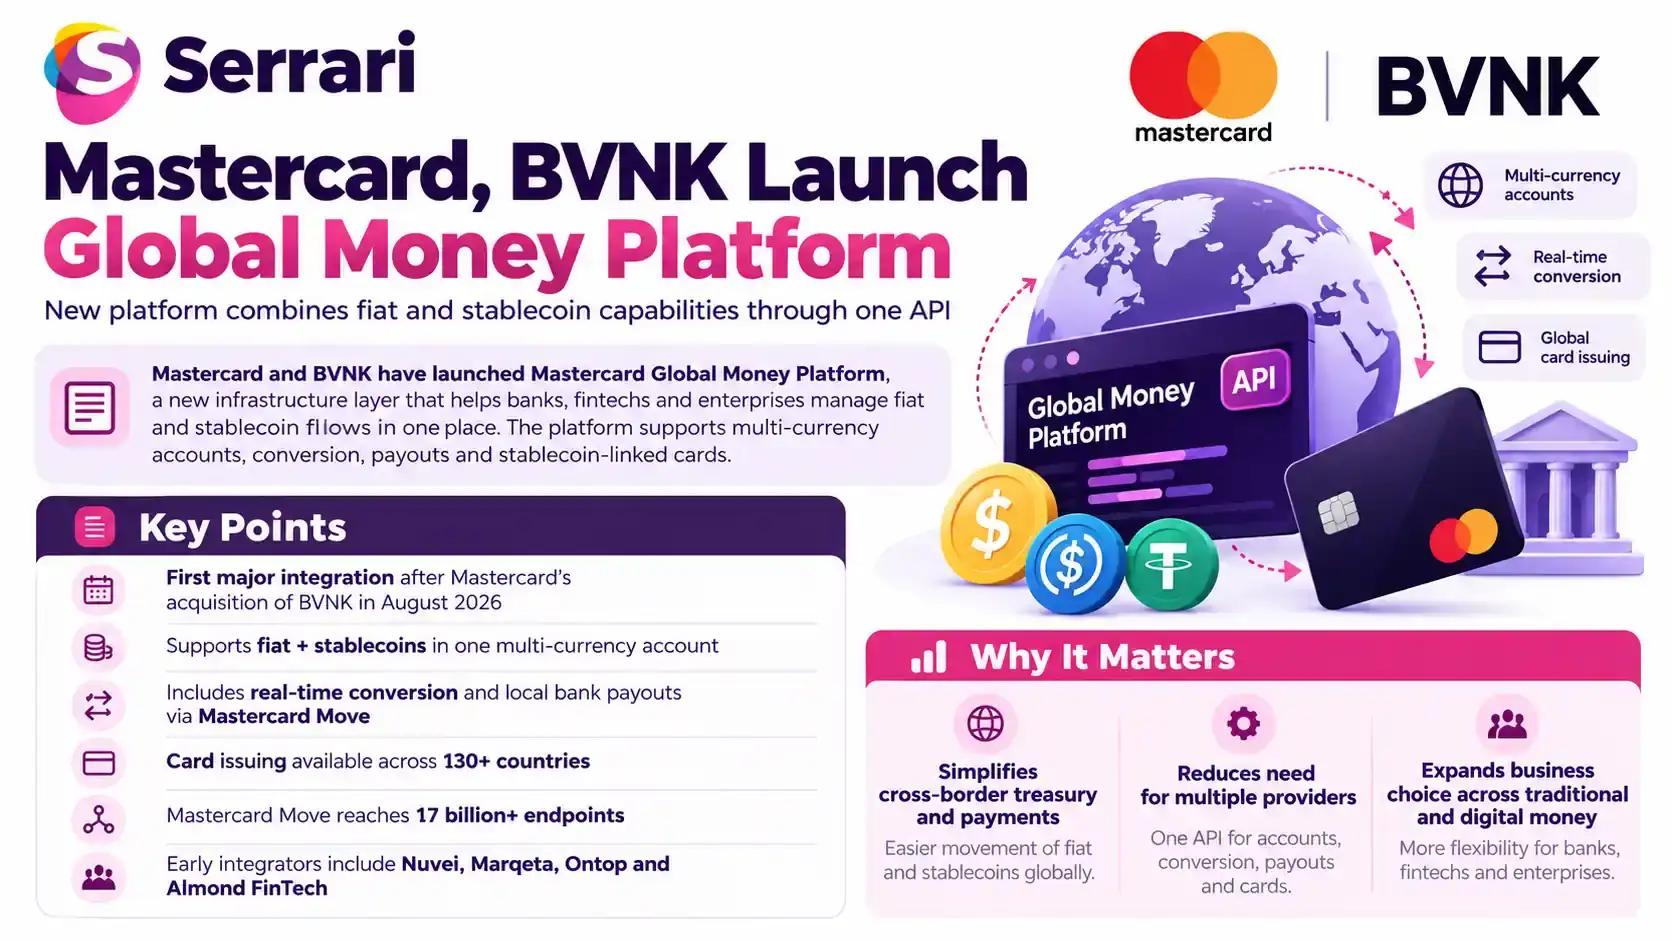
Mastercard and BVNK launched Mastercard Global Money Platform on October 15, 2026, bringing conventional currencies and stablecoin services together through one application programming interface (API). The new payments infrastructure allows banks, fintechs and businesses to offer multi-currency accounts, convert funds, issue stablecoin-linked cards and make local bank payouts.
It is the first major integration of the two companies’ technologies since Mastercard completed its BVNK acquisition on August 3, 2026. The platform is available through BVNK, although individual services and geographic coverage may vary.
Key Overview
- The platform brings fiat and stablecoin accounts, payments and conversions into one integration.
- Banks and fintechs can embed services into products offered under their own brands.
- Mastercard Move, the wider money-transfer network, reaches more than 17 billion endpoints.
- Stablecoin-linked card issuance is available across more than 130 countries.
- Nuvei, Marqeta, Ontop and Almond FinTech are among the announced early integrators.
- Wider payout coverage is planned for 2027; it should not be mistaken for full coverage at launch.
How the Global Money Platform Works
The service centres on a multi-currency account that can hold traditional money, known as fiat currency, alongside stablecoins, which are digital tokens designed to maintain a value relative to an asset such as the US dollar. Businesses can convert balances and manage collections, transfers and payments through a single interface.
Rather than integrating separate providers for wallets, foreign-exchange conversion, cards and payouts, firms can select the services they need and add others over time. The developer documentation describes options for embedded customer accounts as well as direct treasury and payment management.
For example, a manufacturer collecting payments in different currencies could manage receipts and supplier payouts from one system. This may simplify treasury operations and reduce the need to maintain several prefunded payment arrangements, although actual savings will depend on the routes and services used.
Cross-Border Payouts and Stablecoin-Linked Cards
One major feature is the ability to fund local-currency bank payouts using stablecoin balances. The platform integrates Mastercard Move, whose broader network reaches more than 17 billion endpoints.
Mastercard expects the service’s coverage to expand to more than 40 currencies across over 200 countries and territories in 2027. That is a forward-looking expansion target, not a statement that every route is already available.
The platform also enables customers to spend supported stablecoin balances through payment cards. Mastercard says card issuance is available across more than 130 countries, connecting eligible users to its global merchant acceptance network. The account and card capabilities are designed for integration into existing financial products.
Context is everything. Stay ahead of shifting trends with today’s market updates, and uncover emerging opportunities using the Serrari Group Market Index and Marketplace. Then, take control of your own financial future by exploring our Money & Life Reset Transformation Blueprint ™ to build stronger habits, create better systems, and design a path toward lasting wealth.
Early Partners and Business Impact
Payments provider Nuvei and card-issuing platform Marqeta are among the first businesses expected to integrate the technology, alongside Ontop and Almond FinTech. These are announced integrations rather than evidence that every partner has completed a commercial rollout.
For payment companies and financial institutions, the main proposition is simpler access to both traditional payment infrastructure and blockchain-based transfers. Businesses operating across borders could potentially manage working capital more efficiently, while customers may gain more options for receiving, holding and spending funds.
Future Plans for Digital Payments
Mastercard and BVNK say they plan to extend the platform to emerging payment models, including tokenized deposits and agentic commerce, in which software agents can initiate transactions. These capabilities are part of the future development roadmap, not features confirmed as fully operational at launch.
The launch signals a broader effort to make conventional money and digital assets work together within familiar financial products. Adoption will ultimately depend on availability, regulatory requirements, transaction costs and how reliably the combined services perform in real-world payments.
Sources: Mastercard / BVNK
Your financial future isn’t something you wait for—it’s something you build.
The real question is: when do you begin?
Move beyond simply staying informed.
Navigate the markets with clarity—track trends through the Serrari Group Market Index, uncover opportunities in the Serrari Marketplace, and build practical knowledge with our Curated Wealth Builder Platform.
Stay connected to what truly matters.
Get daily insights on macro trends and financial movements across Kenya, Africa, and global markets—delivered through the Serrari Newsletter.
Growth opens doors.
Advance your career through professional programs including ACCA, HESI A2, ATI TEAS 7 , HESI EXIT , NCLEX – RN and NCLEX – PN, Financial Literacy!🌟—designed to move you forward with confidence.
See where money is flowing—clearly and in real time.
Track Money Market Funds, Treasury Bills, Treasury Bonds, Green Bonds, and Fixed Deposits, alongside global and African indexes, key economic indicators, and the evolving Crypto and stablecoin landscape—all within Serrari’s Market Index.