
28 October 2026
Technology leads global gains as the Nasdaq rises 1.18%, while the NSE posts a mixed session with the All-Share at 235.76. Safaricom reports KSh 1.247 trillion in societal value, DStv cuts prices from 5 November and suburban houses outperform apartments.

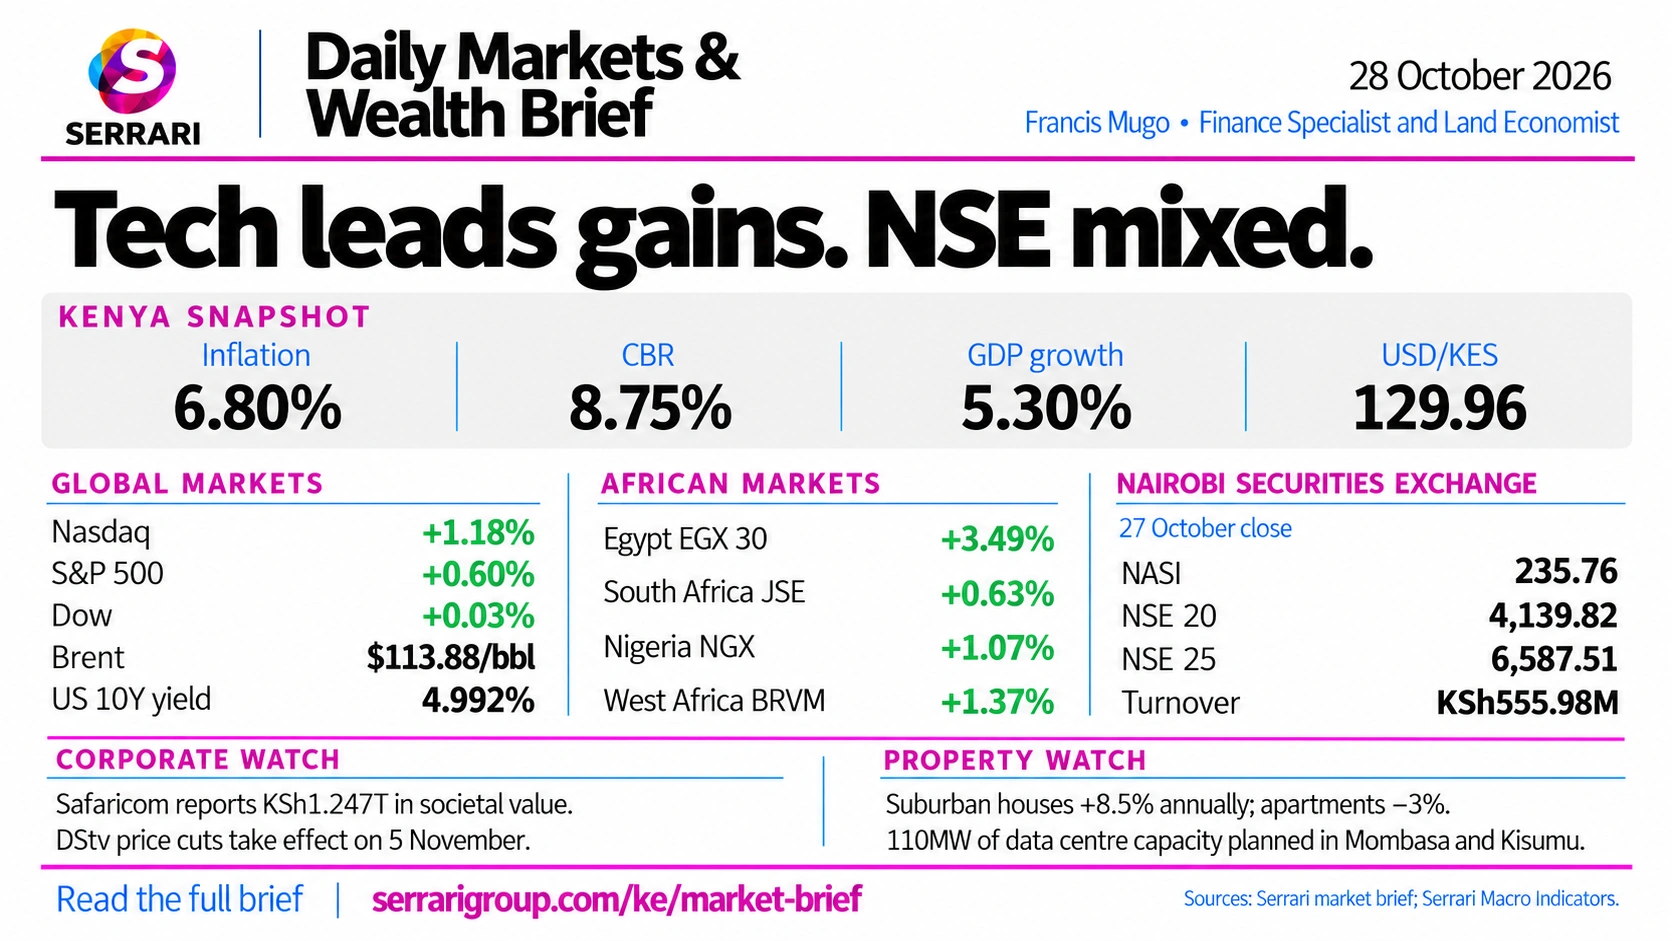
Global Markets
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
| Region | Index | Ticker | Close | Daily change |
|---|---|---|---|---|
| United States | S&P 500 | .INX / .SPX | 7,722.60 | +0.60% |
| United States | Nasdaq Composite | .IXIC | 26,477.81 | +1.18% |
| United States | Dow Jones Industrial Average | .DJI | 52,377.57 | +0.03% |
| South America | Ibovespa | IBOV | 175,710.05 | −0.51% |
| Europe | STOXX Europe 600 | SXXP | 643.68 | +0.47% |
| Europe | DAX | DAX | 25,590.77 | +0.71% |
| Asia | Nikkei 225 | NI225 | 63,268.37 | +1.17% |
| Asia | Hang Seng | HSI | 23,041.32 | −0.42% |
United States Market Core Drivers
- Revived AI Momentum & IPO Optimism: The tech-heavy Nasdaq led a broad market surge (+1.2%), fuelled by optimism surrounding Anthropic's newly announced initial public offering (IPO) filing on the Nasdaq.
- Mega-Cap Funding Blocs: Semiconductor and infrastructure stocks rallied heavily after a banking coalition (including Bank of America, Citi, Morgan Stanley, and Blackstone) announced a $63 billion financing deal for Anthropic to purchase Broadcom's AI technology.
- Corporate Shakeups & Mixed Earnings: General Motors generated headlines by announcing a historic shift of its stock listing from the NYSE to the Nasdaq to align with its tech-driven strategy. Major earnings mixed the market—JetBlue (+19%) and SoFi (+13%) surged on upbeat metrics, while Boeing plunged 11% following steep commercial division losses.
- Macro Disconnect: Despite the headline equity gains, the majority of individual stocks in the S&P 500 actually fell. Investors remained cautious as the Federal Reserve convened for its penultimate policy meeting, weighing a temporary interest rate pause against persistent inflation that could trigger a December hike.
South America Market Core Drivers
- Brazilian Election Fallout: Regional sentiment was dominated by the aftermath of the presidential election in Brazil, where Luiz Inácio Lula da Silva secured victory.
- Currency and Volatility Shock: The Brazilian real dramatically underperformed as the opposing candidate refused to concede, triggering immense volatility that forced the local stock exchange to temporarily halt trading via an automatic circuit breaker.
- Global Trade Headwinds: While the long-term outlook remains tied to the execution of the EU-Mercosur trade bloc agreement to mitigate US/China tariff exposure, near-term Latin American commercial performance remained strained by high regional financing and borrowing costs.
Europe Market Core Drivers
- Pre-Session Hesitation & Cautious Close: European equities initially opened in the red due to macro anxiety, but eventually clawed back modest gains (with the pan-European STOXX 600 ending up 0.47%) by tracking the mid- day Wall Street tech bounce.
- Sovereign Yield Divergence: European bond yields moved in opposite directions. French 10-year OAT yields fell by 12 basis points after Moody's opted to maintain France's A3 credit rating, reducing immediate contagion fears regarding regional fiscal deficits. Conversely, German Bund yields moved higher.
- Central Bank & Fiscal Watch: Investors sat tight ahead of the European Central Bank (ECB) policy updates and the highly scrutinized UK Budget announcement, balancing hopes for economic stabilization against rising business insolvency rates across Western Europe.
Asia Market Core Drivers
- Sizzling Tech Spillover: Asian markets logged a powerful, tech-led advance as regional chip manufacturing heavyweights tracked the US AI boost.
- Blockbuster Capital Injections: In South Korea, SK Hynix surged over 7% to 10% after announcing a spectacular $45 billion capital return plan to shareholders. Samsung Electronics jumped between 5% and 9.5%, and Japan's Advantest and Tokyo Electron experienced massive buying inflows.
- Mixed Greater China Markets: In contrast to Tokyo and Seoul's rallies, Chinese indexes remained under pressure. Hong Kong's Hang Seng and mainland Shanghai benchmarks finished in negative territory as local investors rotated into primary hardware manufacturers and braced for global macroeconomic structural changes.
Sovereign yields
- United States: The 2-year Treasury note yielded 4.739% (+2.8 basis points), the 10-year 4.992% (+0.4 basis points) and the 30-year 5.309% (+0.4 basis points), as investors awaited the Fed statement and watched debt supply.
- Europe: Germany’s 10-year Bund yielded 3.338%, up 1.5 basis points. France’s 10-year OAT was quoted around 3.41%, down 12 basis points after Moody’s preserved its A3 rating.
- Brazil: The 10-year government bond yielded 14.97%–15.03%, down 50 basis points, with National Treasury buffers helping yields retreat from peaks.
- Japan: The 2-year JGB yielded 1.885% (+1.0 basis point) and the 10-year 2.810% (+1.5 basis points) as the tech rally unwound safe-haven demand.
Global forex
- US dollar: DXY rose 0.27% to 102.29 as the Fed began its two-day meeting and firm durable-goods indicators kept a December rate hike in view.
- EUR/USD: 1.1136, down 0.33%, on European fiscal concerns and bank lending weakness.
- USD/JPY: 157.90, up 0.24%, as the technology rebound reduced safe-haven demand.
- GBP/USD: 1.3317, down 0.19%, on pre-Budget caution.
- USD/BRL: R$5.35–R$5.41, with variable moves of 8%–12% against the opening level amid the election shock.
- AUD/USD: 0.7000–0.7040, choppy ahead of Australian Q3 CPI and the Fed statement.
- USD/CAD: 1.4050, up 0.27%, ahead of expected Bank of Canada policy moves.
Global Commodities
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
| Segment | Benchmark | Price / market status | Daily change / driver |
|---|---|---|---|
| Energy | WTI crude | $99.90 / barrel | −1.83% |
| Energy | Brent crude | $113.88 / barrel | −1.67% |
| Energy | Dutch TTF gas | €96.70 / MWh | Stable at peak |
| Precious metals | Gold | $4,055.14 / ounce | +1.00% |
| Precious metals | Silver | $54.20 / ounce | +0.50% |
| Industrial metals | Copper | Mixed momentum | Production expansion |
| Industrial metals | Zinc | Two-week high | Inventory deficit |
| Agriculture | Soybeans | Lower | About −1.00% |
| Agriculture | Sugar and coffee | Soft corrections | Down over 4.00% |
African Markets
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
| Market | Benchmark | Close | Daily change | Context |
|---|---|---|---|---|
| South Africa | FTSE/JSE All Share | 109,820.10 | +0.63% | Mining and retail rebound, supported by interim reports |
| Nigeria | NGX All-Share | 253,990.06 | +1.07% | Record high; market capitalisation ₦164.91 trillion; Dangote Cement up 10% |
| Egypt | EGX 30 | 50,104.83 | +3.49% | Snapped a three-day slide with positive breadth |
| West Africa (UEMOA) | BRVM Composite | About 529.14 | +1.37% | Supported by Bridge Bank and Sonatel rallies |
Sovereign bond yields
- South Africa: The 10-year government bond yielded 8.73%, down 6 basis points on constructive fiscal developments and easing inflation.
- Ivory Coast: The 10-year yielded 7.40%, unchanged. Regional demand remained stable, with a recent 7-year allocation averaging 7.18%.
- Nigeria: The 10-year FGN bond remained near 16.90% as primary-auction stop rates faced supply and liquidity pressure.
- Egypt: The 10-year government bond held at 23.49%; a concurrent 3-year local auction cleared at 24.43%.
Forex, per US dollar
- South Africa: Official USD/ZAR range 16.60–16.64, with the rand around 16.64 under a firmer dollar and softer precious metals; the market is unified.
- Nigeria: Official range 1,339.93–1,352.87, closing at 1,352.87 as the naira appreciated. Parallel rates ranged from 1,380 to 1,385, with street trading around 1,385 ahead of festive imports.
- Egypt: Official USD/EGP range 56.02–56.17; the pound reached 56.17 amid policy adjustments and regional friction.
- West Africa: USD/XOF ranged from 585.00 to 588.17, trading near 588 alongside its euro anchor.
Commodities and staples
- South Africa: Gold was quoted near $4,051 an ounce and platinum near $1,531, alongside citrus and table-grape exports. The Crop Estimates Committee forecast a 17.69 million-tonne maize harvest; the looming AGOA deadline raised export uncertainty.
- Nigeria: Crude oil, cocoa, sesame and cashew exports met seasonal local food inflation: a 50 kg bag of rice reached ₦65,000 and beans exceeded ₦62,000. Shipping demand favoured 20-foot food-grade containers as the cocoa season opened.
- Egypt: Corn imports were projected to overtake wheat in 2026/27 at about 13.2 million tonnes on poultry demand. The government targeted a 20% rise in domestic wheat procurement, alongside citrus, onion, potato and strawberry exports.
- West Africa: The cocoa crop-year opening strained trucking and transport hubs. Cocoa, gold, cotton and cashew remained core exports, with cassava, plantain, sorghum and millet central to domestic demand.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
Market data as at the close of Tuesday 27 October 2026.
- Active counters: Kenya Pipeline Company, Safaricom, Equity Group, Kenya Reinsurance and KCB Group featured among the most active counters.
| Index | Close | Point change | Daily change |
|---|---|---|---|
| NSE All-Share (NASI) | 235.76 | +1.19 | +0.51% |
| NSE 20-Share | 4,139.82 | −14.71 | −0.35% |
| NSE 25-Share | 6,587.51 | −8.94 | −0.14% |
| NSE 10-Share | 2,562.02 | −3.51 | −0.14% |
| NSE Banking Sector Index | 273.80 | −0.75 | −0.27% |
Market statistics
- Market Capitalization: Stood at KSh 3,956.51 Billion, representing an increase of KSh 19.94 Billion on the day.
- Equity Turnover: Recorded at KSh 555.98 Million, coming down from the heightened liquidity seen in previous sessions.
- Total Shares Traded: 16.61 Million shares changed hands across 13,102 equity deals.
- Foreign Flows Tracker: Maintained an active selling bias with net foreign outflows widening to KES 242.7 Million.
Kenya Government Bonds and Treasury Bills
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
| Tenor | Current yield | Month-on-month change | Context |
|---|---|---|---|
| 91-day Treasury bill | 8.748% | −2.16 bp | Slightly lower on high subscriptions |
| 182-day Treasury bill | 8.859% | −1.53 bp | Tracking short-term central bank targets |
| 364-day Treasury bill | 9.027% | −1.16 bp | Stable secondary demand |
| 2-year bond | 9.109% | — | Short-term secondary-market anchor |
| 10-year bond | 12.530% | +13.00 bp | Higher on the month, below the previous year’s cycle |
| 15-year bond | 12.949% | — | Flat mid-to-long pricing |
| 25-year bond | 13.620% | — | Ultra-long yield premium |
Treasury bill auction
- 91-day, issue 2705/091: Weighted average yield 8.7478%, flat week on week.
- 182-day, issue 2679/182: Weighted average yield 8.8591%, flat week on week.
- 364-day, issue 2634/364: Weighted average yield 9.0267%, down 1.16 basis points.
- Liquidity preference: Rates stayed on a flattening path as local liquidity preferences favoured the shortest-duration paper.
Kenya Forex
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
- Ugandan shilling: KES/UGX at 34.14 Ugandan shillings per Kenyan shilling; the brief describes the Ugandan currency as its weakest in decades.
- Tanzanian shilling: KES/TZS at 20.36, stable within historic trading bands.
- Rwandan franc: KES/RWF at 11.36, flat with little weekly slippage.
- Burundian franc: KES/BIF at 22.58, softer amid local liquidity contraction.
| Currency | CBK mean indicative rate (KES) | Context |
|---|---|---|
| US dollar | 129.96 | Consolidated below 130.00 |
| Pound sterling | 173.26 | Muted movement ahead of budget catalysts |
| Euro | 145.10 | Described as unchanged on stable eurozone indicators |
Kenya Commodity Benchmarks
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
| Commodity | Unit | Price / location | Context |
|---|---|---|---|
| White maize | 90 kg bag | KSh 4,243.50 national average; Eldoret KSh 4,500; Nairobi KSh 4,590 | Tight supply before expected late-Q4 short rains |
| Local wheat | 90 kg bag | KSh 5,100 | Raised government procurement floor supports farm income |
| Irish potatoes | 1 kg | KSh 70 wholesale, Meru | Input delivery costs affect supply |
Mombasa tea auction
- Overview: The latest auction cycles indicate a firm recovery, averaging USD 2.36 per Kg (up 15% from last year's lows), though localized output is restricted by dry conditions.
- Standard CTC Teas: Trading between USD 2.20 – USD 2.80 per Kg.
- Premium Teas / Smallholder (KTDA): Attracting higher bids averaging USD 2.46 per Kg.
- Note: Overall margins are being actively calculated against the newly introduced 0.8% export levy enforced since May.
Nairobi coffee auction
- Overview: The newly launched 2026/27 crop year has cleared more than KSh 1.5 Billion across its opening sales.
- Average Auction Price: Settled at USD 288.10 to USD 293.00 per 50-Kg bag (~KSh 758 per Kg of clean coffee).
- Premium Lots: Highest-performing grades successfully topped out at USD 397.00 per 50-Kg bag.
Kenya Corporate News
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
Telecommunications & Tech
- Safaricom Launches 2026 Sustainability Index: At the Michael Joseph Centre, Group CEO Peter Ndegwa unveiled the Safaricom 2026 Sustainable Business Report. The review highlights that Safaricom generated KSh 1.247 trillion in societal value for Kenya's economy over the last fiscal year. However, it revealed its solar transition is lagging, with only 2,028 sites running on solar against its 2030 target of 5,000.
- Data Center Market Expansion: A freshly published database on Kenya's colocation infrastructure highlights that Nairobi remains the primary hub. However, a significant geographical decentralisation is underway, with 110 MW of upcoming capacity planned across Mombasa and Kisumu.
Capital Markets & Financials
- Stockbrokers Record Historic Sh14 Billion Bonanza: Triggered by a sustained bull market on the Nairobi Securities Exchange (NSE), stockbrokers collectively banked an estimated Sh14 billion in commissions over the nine months ending September 2026. Year-to-date equity turnover ballooned to Sh395 billion, more than doubling the entirety of last year's Sh145 billion volume.
- Political Big-Wigs Take Stakes: Kiharu MP Ndindi Nyoro has aggressively expanded his capital market footprint, acquiring a 9.76% stake in investment firm Olympia Capital. Nyoro announced intentions to model the firm into a fully-fledged private equity fund to invest in high-quality local stocks.
- Dangote GDR Deadline Closes: The extension window for Kenyan retail investors to buy into the Dangote Petroleum Refinery's Global Depository Receipts (GDR) closed on October 27, marking a unique cross-border inward public entry.
Entertainment & Retail Services
- MultiChoice Triggers Pay-TV Price War: Facing a massive 82.5% drop in its local subscriber base down to 640,430 accounts, MultiChoice Kenya announced aggressive price slashes. Effective November 5, the pay-TV provider will compress its product lines from six to four, including a 37.6% drop in its top-tier DStv package to Sh7,300 per month to ward off streaming competition from Netflix and YouTube.
Macro-Corporate Risks & Infrastructure
- Rironi-Mau Summit Highway Cancelation Threat: Corporate constructors and project finance desks are monitoring a national fiscal advisory revealing that the Kenyan taxpayer faces a potential Sh180.73 billion penalty if the state terminates its 30-year public-private partnership (PPP) road contracts with Chinese consortia.
- Foreign Currency Stockpiles: Local corporate banking divisions note that wealthy individuals and private businesses have locked a record Sh1.52 trillion in foreign-currency accounts, using hard-currency holdings to insulate working capital against persistent policy adjustments.
Kenya Real Estate
Figures as at · Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
Market Recalibration & "Flight to Quality"
- Prime Townhouses Outperform Apartments: Nairobi's upscale residential segment is undergoing a significant transformation. While multi-story apartment lines in saturated pockets like Westlands face oversupply adjustments, family capital is moving decisively into prime suburban townhouses. Data indicates standalone suburban houses grew +8.5% annually, contrasted against a 3% general decline in high-rise apartment asset values.
- Yields & Rents: City-wide residential rental yields remain anchored near 7.4%, with Nairobi's median asking rent for mid-to-high-tier properties tracking at KSh 140,000 per month.
- Slowing Land Markets: Overall domestic credit allocations to the real estate sector contracted by KSh 6.1 Billion year-on-year, leading to a 35.3% reduction in title deeds issued as investors demand deep feasibility checks before deploying cash.
Commercial & Digital Infrastructure Boom
- Decentralised Data Centers: Kenya's digital real estate infrastructure is rapidly expanding beyond the capital. While Nairobi remains the central digital hub, major regional operations are diversifying with 110 MW of upcoming data center capacity planned across secondary hubs in Mombasa and Kisumu.
National Affordable Housing Tracker
- Eldoret Tender Interruption: Days after President Ruto handed over keys to 2,157 new homeowners at the KSh 5.3 Billion Pioneer Affordable Housing Estate, the Affordable Housing Board formally cancelled Tender No. AHB/DISPOSAL/02/2026-2027. The tender, which regulated the sale and commercial leasing of the estate's 104 shops, will be re-advertised under revised parameters.
- Nakuru Phase 2 Acceleration: Construction on Phase Two of the Bahati Affordable Housing Project is progressing. The G+9 structure is slated to introduce 1,218 new homes to the market.
Major Regulatory Enforcement & Legal Battles
- Mombasa Encroachment Ultimatum: Kenya Power issued a strict 90-day eviction notice to 68 occupants unlawfully holding Land Ref LR NO. JOMVU MN/V/222/2 in Jomvu. The utility ordered immediate cessation of all farming and building activities to secure critical infrastructure corridors.
- EACC Asset Recovery: The Ethics and Anti-Corruption Commission (EACC) successfully recovered stolen public land valued at KSh 40 Million in the Milimani area of Kakamega Town, reverting ownership back to the State Department for Housing.
- Githunguri Injunction Reopened: The Environment and Land Court admitted a procedural error and overturned an active injunction blocking third-party development on the multi-billion estate of the late tycoon Stanley Githunguri, scheduling a new priority hearing to look over disputed commercial holdings.
Strategic Rationale & Advice
- Alternative Financing Routes: With institutional lending rates averaging 14.34%, traditional mortgage accessibility remains heavily restricted. Investors looking to maximize performance are utilizing SACCO lines, rent-to-own models, and diaspora inflows to bridge capital gaps without incurring heavy debt service burdens.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.96
CBK mean indicative rate.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026GBP / KES
173.26
CBK mean indicative rate.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026EUR / KES
145.10
CBK mean indicative rate.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
Equities
NSE All-Share
235.76
+1.19 points, +0.51%
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026NSE 20-Share
4,139.82
−14.71 points, −0.35%
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026NSE 25-Share
6,587.51
−8.94 points, −0.14%
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026Equity turnover
KSh 555.98 million
27 October close.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026Market capitalisation
KSh 3,956.51 billion
Up KSh 19.94 billion.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
Rates
Central Bank Rate
8.75%
Prevailing policy rate.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026Kenya 10-year bond
12.530%
Up 13.00 basis points month on month.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 202691-day Treasury bill
8.7478%
Issue 2705/091.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026182-day Treasury bill
8.8591%
Issue 2679/182.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026364-day Treasury bill
9.0267%
Issue 2634/364.
As at
Serrari Group desk compilation, 28 October 2026; market data as at the close of 27 October 2026
At a glance
- 1The Nasdaq gains 1.18% and the S&P 500 rises 0.60% as AI financing supports technology stocks; Brent settles at $113.88 a barrel.
- 2The NSE All-Share rises 0.51% to 235.76 while the NSE 20 and NSE 25 decline; turnover falls to KSh 555.98 million and net foreign outflows reach KSh 242.7 million.
- 3Suburban house values rise 8.5% annually against a 3% apartment decline, with 110 MW of data-centre capacity planned across Mombasa and Kisumu.
Sources
- Serrari Group desk compilation, 28 October 2026; Markets Snapshot – 27 October 2026
- Serrari Group supplied artwork, 28 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — market statistics
- Serrari published Africa macro data