
27 October 2026
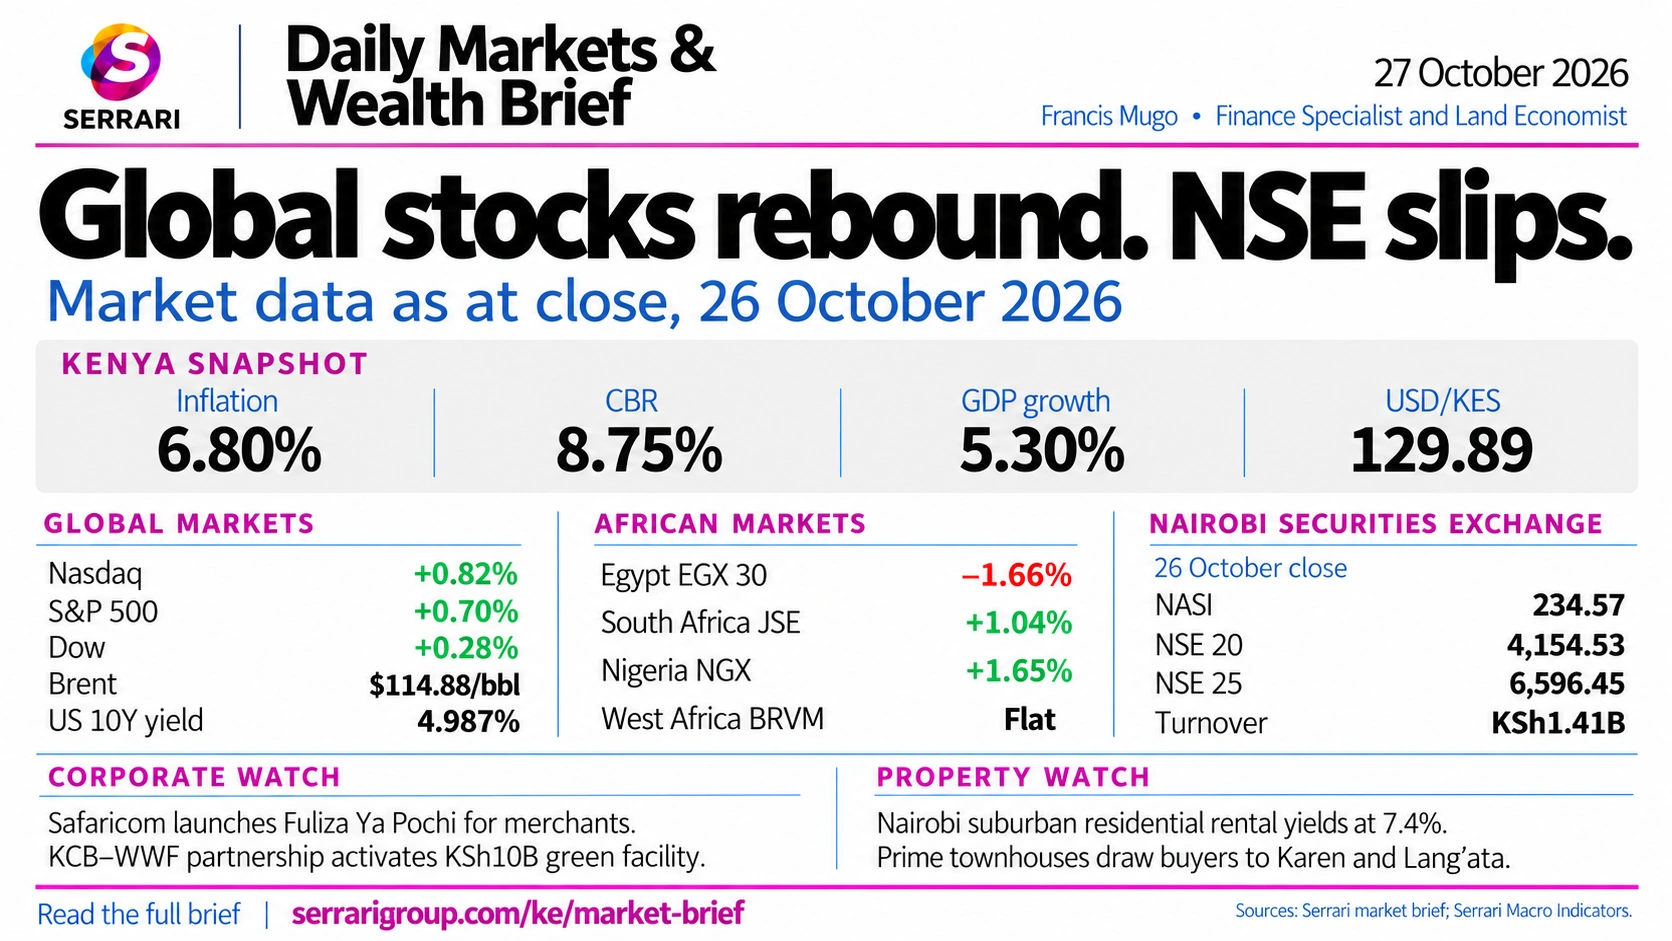
Global stocks rebound as the Nasdaq gains 0.82%, while the NSE All-Share slips to 234.57 on turnover of KSh 1.41 billion. Safaricom launches Fuliza Ya Pochi for merchants, KCB mobilises a KSh 10 billion green facility and Nairobi suburban rental yields reach 7.4%.

Global Markets
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
| Index | Close | Point change | Daily change |
|---|---|---|---|
| S&P 500 | 7,676.77 | +53.09 | +0.70% |
| Nasdaq Composite | 26,169.38 | +214.04 | +0.82% |
| Dow Jones Industrial Average | 52,361.58 | +146.42 | +0.28% |
| Euro STOXX 50 | 6,116.23 | +48.01 | +0.79% |
| DAX | 25,410.84 | — | +0.91% |
| FTSE 100 | 10,767.33 | +76.97 | +0.72% |
| Nikkei 225 | 62,189.65 | −503.51 | −0.80% |
| Hang Seng | 23,211.81 | +118.44 | +0.51% |
| SSE Composite | 3,697.52 | +7.04 | +0.19% |
The Anthropic IPO AI trade revival
- Tech Market Catalyst: Wall Street tech indices registered their largest single-day surge in over a month. The momentum was triggered by the official public IPO filing of Anthropic, the developer behind the Claude AI model.
- Reversing AI Jitters: The filing eased recent market anxieties regarding the multi-billion-dollar monetization timelines of artificial intelligence infrastructure.
Easing Energy Costs & Geopolitical Spikes
- Crude Oil Pullback: International crude oil futures pulled back slightly from near six-month highs. Brent crude fell toward $115.81–$116.00 per barrel, while U.S. West Texas Intermediate (WTI) fell to $101.57–$102.00 per barrel.
- Embedded Risk Premium: Despite the slight Monday retreat on de-escalation hopes, a volatile geopolitical risk premium remains priced into commodities. This follows escalating regional friction involving the US and Iran, alongside fresh Houthi group strikes on Saudi Arabian oil infrastructure over the weekend.
Anticipation of "Hawkish Holds" from Central Banks
- The Federal Reserve (Wednesday): The FOMC is overwhelmingly expected to pause and maintain the Fed funds target range at 3.75%–4.00%. However, sticky 3.7% inflation metrics and a robust U.S. consumer base mean a hawkish tone is expected.
- European Central Bank (Thursday): The ECB is projected to keep its benchmark rate frozen at 2.50%. Attention is heavily fixed on Christine Lagarde's press conference regarding the ongoing French bond market turmoil and widening yield spreads.
- Bank of Japan (Friday): The BOJ is expected to hold its policy rate steady at 1.25% to monitor broader macro stability following its previous tightening cycles.
Sovereign Bond Yield Pressures
- Hovering Near 5%: Strong macro growth metrics pushed the benchmark U.S. 10-year Treasury yield back up to 4.99%.
- Sector Impact: The resilient, elevated yield path continues to compress valuation multiples for high-duration assets and highly leveraged corporate sectors sensitive to long-term borrowing costs.
Emerging Market Instability (Brazil Election Shock)
- Bovespa Collapses: In stark contrast to the U.S. equity rally, emerging market assets faced downward pressure. Brazilian markets crashed as the Bovespa stock index plummeted 14.6% in a single day.
- Fiscal Concerns: This extreme volatility came after leftist President Luiz Inácio Lula da Silva secured a surprise runoff election victory over right-wing conservative Flávio Bolsonaro. The result triggered sudden investor panic over sovereign debt thresholds and mandatory spending limits.
United States Treasury yields
- Overview: U.S. yields finished little changed as macro traders sidelined themselves ahead of the Federal Reserve’s policy meeting on Wednesday. Markets heavily priced in a 90%+ probability that Chair Kevin Warsh would temporarily pause the target rate range at 3.75%–4.00%, though strong economic data kept structural terminal rate expectations firmly hawkish.
- 2-Year Treasury Note: Advanced 3 basis points to finish at 4.716%.
- 10-Year Benchmark Treasury Note: Hovered steadily just below the psychological 5% barrier, easing slightly to 4.987%.
- 30-Year Treasury Bond: Dipped marginally by 2 basis points to settle at 5.299%.
European government bond yields
- Overview: European debt boards traded with a distinct localized split. While core German yields drifted upward as safe-haven equity demand cooled, French sovereign bonds heavily outperformed the broader eurozone market. This relief rally came after credit-rating agency Moody’s unexpectedly kept France’s sovereign credit rating unchanged at Aa3 (retaining a negative outlook), sparking a major squeeze in French risk premiums.
- Germany 10-Year Bund (Eurozone Benchmark): Rose 3.2 basis points to 3.377%.
- Germany 2-Year Note: Advanced 6 basis points to settle at 3.02%.
- France 10-Year OAT: Fell sharply by 6.7 basis points to finish at 4.963% (pulling down further to 4.91% in over- the-counter late interbank trading), narrowingly compressing its spread against Germany.
Asian government bond yields
- Overview: Asian fixed-income markets clawed back yield losses from the prior week's steep multi-decade bond rally. Upward pressure focused heavily on Japan, where sticky 2.1% core inflation prints and rising consumer expectations left traders preparing for a hawkish policy framework shift and a projected rate hike by the BOJ as early as December.
- Japan 2-Year JGB: Rose 2.5 basis points to settle at 1.885%.
- Japan 10-Year JGB (Benchmark): Crept up 1.5 basis points to close at 2.810%, pulling back from multi-week lows.
- Japan 5-Year JGB: Advanced 3 basis points to close at 2.250%.
Major currency pairs
- Overview: The key interbank and spot exchange rates settled as follows on Monday, October 26, 2026:
- EUR/USD: $1.1179 (Down 0.21%) The Euro faced downward pressure due to ongoing growth stagnation in the Eurozone and elevated energy costs, despite receiving a minor relief lift after Moody's opted not to downgrade France's credit rating.
- USD/JPY: 157.46 (Yen down 0.43%) The Japanese Yen slipped against a strengthening greenback. Investors remain focused on the Bank of Japan's upcoming policy meeting on October 30, keeping a close watch for any potential government intervention signals.
- GBP/USD: $1.3348 (Down 0.15%) Sterling pulled back slightly as traders trimmed exposure ahead of the highly anticipated UK Budget announcement scheduled for Wednesday, October 28.
Regional currency dynamics
- Overview: United States (US Dollar) The US Dollar Index (DXY) rose 0.31% to sit near the 102.00 level. Resilient business surveys—including a strong S&P Global Composite PMI expansion at 57.6—and persistent inflation pressures have cemented expectations that the Federal Reserve will hold interest rates steady at its policy meeting, rather than rushing into deeper rate cuts. Europe (Euro & British Pound)
- Fiscal Stress: High European natural gas prices heading into winter continue to cap the Euro's upside. Additionally, political tension and a wider French-German bond yield spread have kept Euro sentiment fragile.
- Pre-Budget Caution: In the UK, the incoming Budget has prompted defensive positioning. Nonetheless, a relatively hawkish Bank of England stance continues to give the Pound a baseline layer of support. Asia (Japanese Yen & Regional Currencies)
- Interest Rate Widening: The wide interest rate gap between the US Fed (4.00%) and the Bank of Japan (1.25%) continues to structurally favour the US Dollar, keeping the Yen pinned above the 157 zone.
- Emerging Asia: In other regional moves, currencies exposed to global trade and commodity demands traded with slight caution due to mixed growth markers coming out of mainland China.
Global Commodities
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
Energy markets
- Overview: Crude oil prices slid broadly as diplomatic channels between Washington, Tehran, and Qatari mediators offered brief hopes of cooling West Asian geopolitical frictions.
- Brent Crude: Settled down 1.6% to $114.88 per barrel. Despite the daily decline, a significant risk premium remains embedded in international benchmarks due to ongoing infrastructure threats.
- WTI Crude: Slipped 1.9% to $101.29 per barrel. Low global stockpiles outside of mainland China continue to keep a structural floor under the U.S. benchmark.
- Natural Gas: The bearish trend persisted for Henry Hub futures, with speculative net short positions tracking near a 2.5-year high amid steady regional output.
Precious and industrial metals
- Overview: Safe-haven commodities moved back to center stage as market participants rotated away from overextended equity positions.
- Gold: Rebounded 0.8% to settle at $4,038.40 per ounce. Bargain hunters stepped in just above the $4,000 baseline as traders awaited clarity on the Federal Reserve’s upcoming interest rate trajectory.
- Copper & Iron Ore: Industrial metals stabilized gently. Copper prices staged a modest technical bounce, while iron ore futures were supported by declining port inventories across Chinese trade hubs.
Agriculture and softs
- Overview: Bumper supply dynamics heavily dominated price action across major agricultural trading desks.
- Soybeans: Plunged to a nearly nine-week low of $12.40 per bushel. Accelerated harvest timelines across the U.S. Midwest and rapid planting expansions in Brazil offset robust short-term export deliveries to China.
- Raw Sugar: Traded with relative weakness, moving toward 20.2¢ per pound. Hedge funds and speculators heavily trimmed long exposures as favourable global weather conditions improved crop yield outlooks.
African Markets
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
| Market | Benchmark | Close | Daily change | YTD context |
|---|---|---|---|---|
| South Africa | JSE All Share | 109,138.34 | +1.04% | About −5% in local currency |
| Nigeria | NGX All-Share | 251,290.54 | +1.65% | Above +57% |
| Egypt | EGX 30 | 48,416.94 | −1.66% | Below the September high above 56,900 |
| West Africa (WAEMU) | BRVM Composite | 529.14 | Flat | About +53% |
Sovereign bond yields
- South Africa: The 10-year government bond yielded 8.79%, near one-month lows after a bond-friendly mid-term budget update.
- Nigeria: The 10-year FGN bond yielded 16.91%, reflecting heavy supply and a 23.00% policy rate.
- Egypt: The 10-year Treasury bond yielded 23.49%, under pressure from geopolitical risk, foreign outflows and currency weakness.
- WAEMU: The BRVM average market yield stood at 6.60%; major sovereign tranches carried coupons of 6.15%–6.85%.
Forex, per US dollar
- South Africa: USD/ZAR at R16.62; the rand depreciated 0.37% on the day within its multi-month trading channel.
- Nigeria: USD/NGN at ₦1,367.61; the naira weakened by ₦5.77 from Friday at the official window.
- Egypt: USD/EGP at 56.27, a record low for the pound as external strains intensified.
- WAEMU: USD/XOF at 586.51 FCFA, slightly weaker alongside the euro’s decline.
Commodities
- Nigeria: The regional table quotes Brent around $116.00 a barrel, about $51 above the budget benchmark, supporting oil revenues.
- Egypt: 21-karat gold held at EGP 6,329 per gram as currency depreciation supported local asset values; the table cites a 0.4% global recovery bounce.
- West Africa: ICE cocoa fell 1.59% to $5,503 a tonne as inventories rebuilt and consumer chocolate demand softened.
- South Africa: Platinum and domestic fuel markets were mixed. The government announced a R10 billion fuel levy relief package amid high global oil costs.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
Market data as at the close of Monday 26 October 2026.
- Trading activity: Equity turnover rose 136.3% to KSh 1.41 billion from KSh 596.4 million on Friday. Volume increased 154.4% to 42.95 million shares across 16,540 deals.
- Foreign flows: Foreign investors recorded net outflows of KSh 56.5 million, with purchases of KSh 1.02 billion and sales of KSh 1.08 billion.
- Gainers and losers: Nairobi Securities Exchange PLC led gainers, followed by Kenya Pipeline Company and Express Kenya. Uchumi Supermarkets led losses, followed by Longhorn Publishers and Sasini Tea and Coffee.
| Index | Close | Point change | Daily change | YTD |
|---|---|---|---|---|
| NSE All-Share (NASI) | 234.57 | −0.35 | −0.15% | +25.72% |
| NSE 10-Share | 2,565.53 | −17.70 | −0.69% | +30.55% |
| NSE 20-Share | 4,154.53 | −22.88 | −0.55% | +32.34% |
| NSE 25-Share | 6,596.45 | −42.29 | −0.64% | +29.43% |
| NSE Banking Sector Index | 274.55 | −1.88 | −0.68% | +34.81% |
Kenya Government Bonds and Treasury Bills
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
| Tenor | Auction / market yield | Annualised net yield after 15% WHT |
|---|---|---|
| 91-day Treasury bill | 8.75% | About 7.44% |
| 182-day Treasury bill | 8.86% | About 7.53% |
| 364-day Treasury bill | 9.03% | About 7.68% |
| 2-year bond | 9.11% | About 7.74% |
| 5-year bond | 9.23% | About 7.85% |
| 10-year bond | 12.53% | About 10.65% |
Treasury bill auction
- 91-day, issue 2705/091: Interest rate 8.7478%; post-tax net yield about 7.4356% after 15% withholding tax, unchanged from the prior week.
- 182-day, issue 2679/182: Interest rate 8.8591%; post-tax net yield about 7.5302% after 15% withholding tax, unchanged with a narrow premium over 91-day paper.
- 364-day, issue 2634/364: Interest rate 9.0267%; post-tax net yield about 7.6727% after 15% withholding tax, down 1.1 basis points from 9.038%.
Auction subscription and bidding
- Total Subscription Rate: The week's auction was fully subscribed, tracking at 103% overall performance. Total bids received across the electronic DhowCSD infrastructure platform amounted to KSh 28.8 billion against the KSh 28.0 billion initially advertised by the government.
- Government Acceptance: The National Treasury accepted 100% of the submitted bids (KSh 28.8 billion), utilizing the balanced subscription to fulfill short-term funding allocations without forcing stop rates higher.
- Maturity Concentration: Shorter tenors continue to dominate investor bidding preferences. The 91-day paper attracted the most active bidding relative to its standalone allocation block, closing at 179% subscribed as corporate and retail asset managers focused on immediate short-term liquidity shields.
Kenya Forex
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
- Uganda: KES/UGX at 34.19 Ugandan shillings per Kenyan shilling, up from about 32.26 the previous week.
- Tanzania: KES/TZS at 20.33, within a fraction of its six-month baseline.
- Rwanda: KES/RWF at 11.36, flat over a multi-week stretch.
- Burundi: KES/BIF at 23.09, flat within a regulated mid-month range.
| Pair | Official mean rate | Context |
|---|---|---|
| USD / KES | 129.89 | The brief describes 0.5% weakening over seven days; six-month average 129.44 |
| GBP / KES | 173.73 | Up from 173.58 at the preceding weekend close |
| EUR / KES | 145.53 | Up from Friday’s 145.34 |
| ZAR / KES | 7.86 | Flat within regional capital flows |
Kenya Commodity Benchmarks
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
| Commodity | Market | Price | Context |
|---|---|---|---|
| Super petrol | EPRA stations, Nairobi | KSh 226.96 / litre | Elevated after mid-month subsidy removal; the local table quotes Brent at $115.91 |
| Diesel | EPRA stations, Nairobi | KSh 227.76 / litre | Pressure from European winter distillate demand |
| Dry white maize | National wholesale average | KSh 4,243.50 / 90 kg bag | Retail quotes: KSh 6,500 in Kisumu and KSh 4,670 in Eldoret |
| Export coffee | Nairobi Coffee Exchange | About US$287 / 50 kg bag | New season opens; the table also quotes about KSh 745 per kg of clean coffee |
| Export black tea | Mombasa auction / EATTA | About KSh 283.80 / kg | Average about US$2.20 per kg; Mununga premium grades above KSh 433 per kg |
Kenya Corporate News
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
Capital markets: CMA quarterly report
- Overview: The Nairobi Securities Exchange (NSE) hit a milestone as its total market capitalisation officially crossed the KSh 4.1 trillion mark for the first time.
- The Valuation vs. Trading Paradox: According to a newly released report by the Capital Markets Authority (CMA), listed wealth grew by KSh 360 billion over the preceding quarter due to a strong bull-market run. However, actual share trading turnover plunged by 72.4% down to KSh 72.7 billion, pointing to a tight market where valuations are surging despite lower trading liquidity.
- Investor Base Expansion: Backed by high-profile corporate listings earlier in the year (such as Kenya Pipeline Company (KPC) and Family Bank), total registered investors on the bourse jumped to 2.36 million, more than tripling last year's growth trajectory.
Telecommunications: Safaricom Deploys Massive Product Double-Feature
- Overview: Safaricom PLC executed two major product rollouts targeting retail connectivity and micro-merchant credit lines:
- "Family Share" Home Fiber Integration: Safaricom launched its integrated Family Share bundle. Starting at KSh 3,749, the plan consolidates home fiber internet, mobile data, and voice minutes into a single monthly bill, allowing the primary user to distribute mobile allowances across up to five family members. The move targets retention as its active fiber-to-the-home business grows 27% year-on-year.
- "Fuliza Ya Pochi" Credit Line: In its fintech ecosystem, Safaricom introduced Fuliza Ya Pochi, extending M-PESA's popular overdraft facility to over one million small-scale Pochi La Biashara merchants. This allows micro- enterprises to overdraw their balances instantly to pay suppliers or buy raw stock even when cash flows run thin.
Banking & Sustainable Finance: KCB Mobilises Green Capital
- Overview: KCB Group entered a strategic partnership with WWF-Kenya to plug growing shortfalls in traditional conservation and climate funding.
- The Green Facility: The initiative explicitly activates KCB's KSh 10 billion Green Climate Fund facility. The private-sector partnership is designed to fund eco-tourism, finance local nature-based enterprises, and embed environmental and biodiversity risk metrics directly into corporate lending decision frameworks.
Entertainment: MultiChoice Slashes DStv Subscriptions
- Overview: Confronting structural pressures from illegal streaming operations and changing digital trends, MultiChoice Kenya unveiled a redesigned package tier for its DStv service set to take effect on November 5, 2026.
- New Price Structures: CEO Zola Miranda announced price changes to give consumers greater choice, introducing an entry-level Starter Pack at KSh 750 alongside premium tiers: Select (KSh 1,500), Sports (KSh 3,000), and Ultimate (KSh 7,300).
Energy & Mergers: The Dangote-KPC Valuation Struggle
- Overview: The KSh 42.5 billion block trade for a 24.76% stake in Kenya Pipeline Company nearly collapsed over the price demanded by state-backed sellers, including NSSF. A compromise was reached, with Dangote agreeing to forgo KSh 1.4 billion in initial dividends.
Wealthy Kenyans Stockpile a Record Sh1.52 Trillion in Dollars
- Overview: A new report from the Kenya National Bureau of Statistics (KNBS) has revealed that wealthy individuals and corporate entities have stockpiled an all-time high of KSh 1.52 trillion in foreign-currency deposits (mainly US dollars, Euros, and Sterling) within local commercial banks.
- The Motivating Factor: Foreign-currency holdings surged by KSh 240.57 billion over a rolling 12-month window. Financial experts note that local cash-rich savers are heavily hedging values against incoming US Federal Reserve rate transitions and cash flow management, choosing banking cushions over domestic industrial expansion.
- The Corporate Bulk: Corporates account for 71.3% (KSh 957 billion) of the total dollar pile, primarily to buffer international supplier settlement loops, while individual households control the remaining 28.7%.
Trade & Infrastructure: Russia Diplomacy and Toll-Road Rollouts
- Overview: The National Treasury and diplomatic missions moved to address structural trade deficits and infrastructure shortfalls:
- The Russian Export Push: Prime Cabinet Secretary Musalia Mudavadi finalized preparations to travel to Moscow for the Russia–Africa Summit. Kenya is aggressively trying to bridge a KSh 26.6 billion bilateral trade deficit with Russia. While imports of Russian fertilizers and wheat fell, Nairobi plans to seek expanded, direct shelf access for Kenyan tea, coffee, and horticultural produce.
- KSh 42 Billion Toll Contracts: To construct critical transit pathways without expanding public debt, the National Treasury announced it is seeking KSh 42 billion in private toll contracts to fund major highway bypasses across Nairobi and Mombasa.
Insurance & Regional Mergers: APA Apollo Expands into Tanzania
- Overview: Kenyan financial powerhouse APA Apollo Group completed a major cross-border expansion.
- Double Takeover Executed: The group finalized the acquisition of majority stakes in two prominent Tanzanian corporations: Meticulous General Insurance Company and Metro Life Assurance Company. The undisclosed deal kicks off APA Apollo's 2026–2030 regional platform expansion strategy.
Kenya Real Estate
Figures as at · Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
Legal & Land Tenure: Supreme Court Sets a New Precedent
- Overview: A massive 24-year-old corporate land dispute concluded with a historic judgment regarding adverse possession rules in Kenya.
- The Kakuzi vs. Makuyu Club Verdict: On October 23, 2026, the Supreme Court officially dismissed a final appeal by agricultural giant Kakuzi Plc, ordering it to permanently forfeit approximately 70 acres of land to Makuyu Club.
- 12-Year Statutory Enforcement: The apex court ruled that despite Kakuzi holding the formal title since 1967, it failed to assert its ownership rights within the statutory 12-year limitation period while the golf club actively developed and occupied the land. Property lawyers are flagging this as a massive warning to absentee or passive institutional landowners across the country.
Market Squeeze: The Luxury Townhouse Pivot & Flight to Quality
- Overview: A distinct divergence has emerged across Nairobi’s residential ecosystem. While high-density apartment blocks face cooling demand, prime standalone houses and townhouses are seeing strong capital appreciation.
- The Yield Cushion: Data from HassConsult puts Nairobi’s suburban residential rental yields at an impressive 7.4%, the highest baseline in nearly two decades.
- Strategic Corridors: Driven by a definitive "flight to quality," affluent buyers are bypassing congested nodes to invest heavily in master-planned townhouse developments along the Lang'ata and Karen corridors. Projects like Purple Dot International’s 89-unit Marigold II townhouse estate highlight the intense institutional rush to lock down finite land before construction raw material inflation surges further.
Regulatory Shock: Widespread Structural Safety Fears in High-Rises
- Overview: Regulatory compliance and building structural safety have triggered massive anxiety across the capital's real estate sector.
- The South C Crisis: An enforcement clampdown has intensified following the catastrophic structural failure of a 16-storey building developed by Abyan Consulting Limited along Muhoho Avenue in Nairobi's South C estate.
- The Enforcement Fallout: Authorities revealed the high-rise had been flagged multiple times by county planners for illegally adding unapproved floors and ignoring formal stop-work orders. Analysts warn this tragedy is heavily denting buyer confidence in speculative off-plan high-rises across Eastleigh, Pangani, Parklands, and Langata, prompting prospective tenants to demand immediate refunds or exit to safer suburbs.
Land and Taxation
- The Kiambu Land Rate Protests: Tensions are mounting in the Nairobi metropolitan fringes as Kiambu county landowners plan major protests against the National Rating Act. The new law forces counties to charge strict land rates on all freehold and leasehold residential plots, with county compliance officers already halting residential construction for owners carrying historical arrears.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.89
Official mean rate.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026GBP / KES
173.73
Official mean rate.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026EUR / KES
145.53
Official mean rate.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026ZAR / KES
7.86
Official mean rate.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
Equities
NSE All-Share
234.57
−0.35 points, −0.15%
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026NSE 20-Share
4,154.53
−22.88 points, −0.55%
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026NSE 25-Share
6,596.45
−42.29 points, −0.64%
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026Equity turnover
KSh 1.41 billion
Up 136.3% on the session.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
Rates
Central Bank Rate
8.75%
Policy rate shown in the supplied artwork.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026Kenya 10-year bond
12.53%
Steady on the day.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 202691-day Treasury bill
8.7478%
Issue 2705/091.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026182-day Treasury bill
8.8591%
Issue 2679/182.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026364-day Treasury bill
9.0267%
Issue 2634/364.
As at
Serrari Group desk compilation, 27 October 2026; market data as at the close of 26 October 2026
At a glance
- 1US equities rebound ahead of central bank meetings: the Nasdaq rises 0.82%, the S&P 500 0.70% and the Dow 0.28%, while Brent settles at $114.88 a barrel.
- 2The NSE All-Share eases 0.15% to 234.57 as equity turnover rises to KSh 1.41 billion and foreign investors record KSh 56.5 million in net outflows.
- 3Safaricom extends overdrafts to Pochi La Biashara merchants, KCB and WWF-Kenya activate a KSh 10 billion green facility, and Nairobi suburban rental yields reach 7.4%.
Sources
- Serrari Group desk compilation, 27 October 2026; Markets Snapshot – 26 October 2026
- Serrari Group supplied artwork, 27 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — market statistics
- Serrari published Africa macro data