
26 October 2026
Brent surges to $116.72 a barrel as global equities retreat, while the NSE All-Share closes at 234.92. EABL faces a KSh 924 million liquor-licence arrears demand and real estate bank lending falls to KSh 445.9 billion.

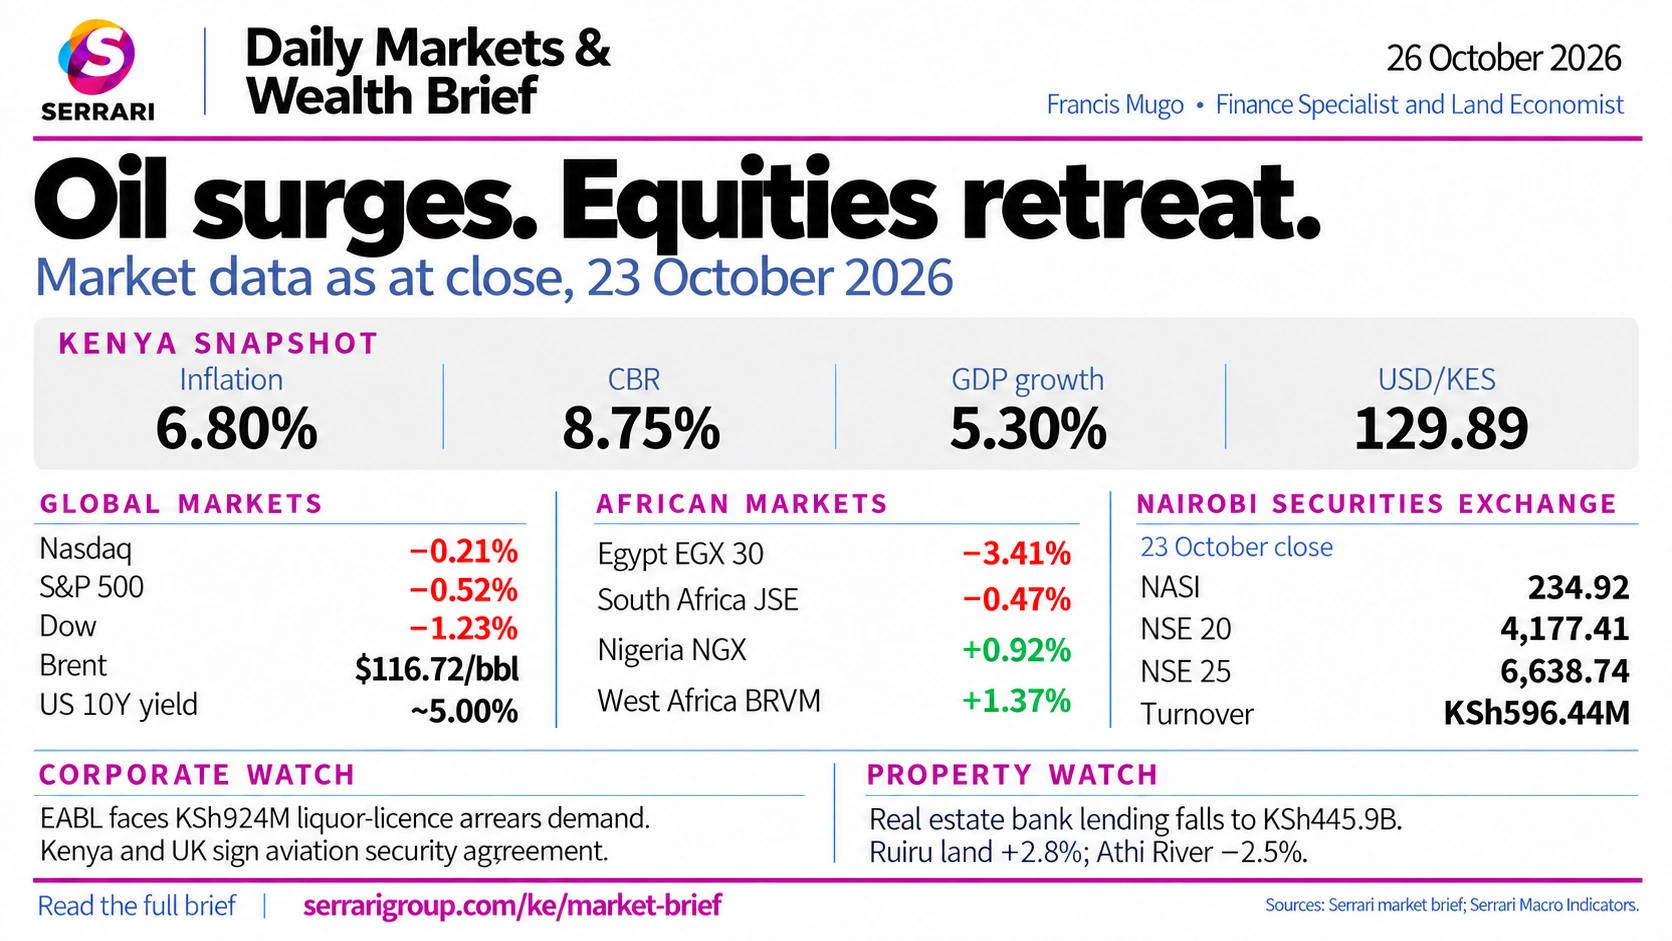
Global Markets
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
| Index | Close | Point change | Daily change |
|---|---|---|---|
| Nasdaq Composite | 25,955.34 | −53.52 | −0.21% |
| S&P 500 | 7,623.68 | −39.75 | −0.52% |
| Dow Jones Industrial Average | 52,215.16 | −652.82 | −1.23% |
| Russell 2000 | 2,775.90 | −8.13 | −0.29% |
| STOXX 600 | 635.77 | −1.97 | −0.31% |
| DAX | 25,152.31 | — | −0.80% |
| CAC 40 | 7,782.82 | — | −0.30% |
| FTSE 100 | 10,690.36 | −34.67 | −0.32% |
| Nikkei 225 | 62,693.16 | −214.68 | −0.34% |
| KOSPI | — | — | Flat / positive |
| CSI 300 | — | — | Under pressure |
Energy shock and rotation
- Oil supply risk: Houthi drone strikes on Saudi oil infrastructure and reported spills in the UAE drove Brent to $116.72 a barrel, up 3.14%, heightening inflation fears.
- Energy stocks: The S&P 500 energy sector rose 2.5% to a record high, with Chevron up 2.9% and ConocoPhillips up 3.6%.
United States
- Index divergence: The Dow lost 652.82 points, or 1.23%, to 52,215.16. The Nasdaq eased 0.21% to 25,955.34 as chipmakers cushioned broader weakness.
- AI investment: Micron recovered 2.5%, Intel 1.7% and AMD 1.7% after the previous session’s sell-off. SK Hynix scrapped plans for a US IPO of its memory-chip subsidiary, according to the brief.
- Restructuring: American Express fell 3.7% after announcing cuts to about 5% of its workforce despite an earnings-per-share beat. Caterpillar declined 2.4%.
Europe and Asia
- European companies: The opening summary quotes the STOXX 600 down 0.6% and the Euro STOXX 50 down 0.9%. Kering fell about 16% on weak Chinese retail demand and Volvo Car 26% after an almost 50% year-on-year fall in China revenue. LSEG gained 7.7% after raising guidance.
- Asia: The opening summary quotes the Nikkei down 0.6%. The KOSPI recovered from an early 4% fall to finish around flat or positive, supported by SK Hynix’s 4.4% rise. Japanese annual inflation of 2.1% reinforced December rate-hike expectations; Kao gained 3.0% and Secom 2.7%.
Sovereign yields and macro
- United States: The 10-year yield approached 4.99%–5.00%, up 3.7 basis points, as oil inflation revived higher-for-longer expectations. PCE inflation was forecast at 3.7%, while University of Michigan consumer sentiment registered a multi-month low.
- Europe and Japan: The UK 10-year reached 5.37%, up 4 basis points; Germany’s was 3.31%–3.33%, down 1 basis point; France’s 5.04%, down 3.5 basis points, with the OAT–Bund spread near 170–178 basis points. Japanese yields remained elevated and steady amid 2.1% inflation.
Global forex
- EUR/USD: 1.1215, down 0.10%, with weak eurozone flash PMI of 48.4 and French budget concerns.
- USD/JPY: 156.90, down 0.04% or broadly flat, supported by Japanese inflation and expectations of a December rate hike.
- GBP/USD: 1.3392, down 0.11%, on profit-taking before the UK fiscal budget statement.
- USD/CHF: 0.8205, down 0.08%, as the Swiss franc retained safe-haven support.
- USD/CAD: 1.4035, up 0.11%, as Canadian slowdown concerns outweighed oil support.
- Dollar index: DXY 101.68, up 0.08%, supported by the rebound in Treasury yields.
Global Commodities
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
| Commodity | Price | Daily change | Context |
|---|---|---|---|
| Brent crude | $116.72 / barrel | +3.14% | Middle East supply risks; the table describes the highest level since June 2022 |
| WTI crude | $103.27 / barrel | +3.82% | Broke above $100 on regional conflict fears |
| Dutch TTF gas | €93.00 / MWh | Positive | Highest since December 2022 amid restricted Qatari LNG supply |
| Henry Hub gas | $2.66 / MMBtu | Negative | Two-month low on mild weather |
| Spot gold | $3,998.35 / ounce | −0.60% | Below $4,000; down 4% for the week |
| Spot silver | $53.97 / ounce | −1.00% | Lowest baseline since late 2025 |
| Spot platinum | $1,555.84 / ounce | −0.90% | Near three-month support floors |
| LME 3-month copper | $14,059.20 / tonne | Mixed | About 1% higher intraday, capped by rising exchange inventories |
| CBOT soybeans | $12.56 / bushel | +0.28% | Modest late-session gains |
African Markets
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
| Market | Benchmark | Close | Daily change |
|---|---|---|---|
| South Africa | JSE All Share | 108,020.10 | −0.47% |
| Nigeria | NGX All-Share | 247,222.27 | +0.92% |
| Egypt | EGX 30 | 51,052.30 | −3.41% |
| West Africa (WAEMU) | BRVM Composite | — | +1.37% |
Stocks
- Regional performance: South African mining liquidation weighed on the JSE; Nigeria broke a two-day losing streak; Egypt faced geopolitical and margin pressure; West Africa advanced on banking splits.
Sovereign yields
- South Africa: 5-year 8.225%, 10-year 8.790% and 30-year 9.080%; the 10-year rose 2 basis points but remained near monthly lows on fiscal consolidation.
- Nigeria: 2-year 16.207%, 10-year 16.893% and 30-year 14.751%. Average short- and long-term FGN yields rose 37 and 17 basis points respectively as Q4 domestic borrowing expanded.
- Egypt: 3-month bill 23.931%, 5-year bond 23.780% and 10-year bond 23.490%. The submission describes an inverted curve and a 47.7% widening trade deficit.
- WAEMU: Average sovereign yields held at 6.60%–6.69%, supported by liquidity across 210 active fixed-income lines.
Currencies
- US dollar rates: USD/ZAR 16.5630, USD/NGN 1,361.84, USD/EGP 55.2500 and USD/XOF 585.97. The brief describes local-currency weakening of 0.54%, 1.30%, 1.63% and 0.38% respectively, amid risk reduction, import demand and euro weakness.
- Egyptian pressure: The Egyptian pound faced an expanding $48.1 billion trade deficit and energy import costs.
Commodities
- Oil exporters and importers: Brent at $116.72 offered windfall receipts to Nigerian and West African producers while raising import inflation elsewhere. Nigeria’s production edged toward 1.56 million barrels a day; Bonny Light traded at a premium to Brent.
- South African metals: The regional table quotes gold at $3,998.49 an ounce, platinum at $1,555.84 and palladium at $1,048.31. Precious metals fell to multi-month lows, while corn, iron and bulk exports to China held steady.
- Food and regional supply: Egypt faced wheat price increases above 30% but retained six months of strategic food cover through expanded silos. West African cocoa remained firm and mining consolidated, with forward supply agreements cushioning exposure.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
Market data as at the close of Friday 23 October 2026.
- Turnover: Equity turnover fell to KSh 596.44 million.
- Market capitalisation: Declined KSh 53.86 billion to KSh 3,942.39 billion.
- Volume: 16.88 million shares traded across 13,822 deals.
- Market movers: Nairobi Securities Exchange PLC bucked the broader decline. Kenya Pipeline Company led gainers, followed by Shri Krishana Overseas and Kakuzi; Olympia Capital Holdings and Express Kenya led losses.
| Index | Close | Point change | Daily change |
|---|---|---|---|
| NSE All-Share (NASI) | 234.92 | −3.21 | −1.35% |
| NSE 20-Share | 4,177.41 | −44.26 | −1.05% |
| NSE 25-Share | 6,638.74 | −118.58 | −1.75% |
| NSE 10-Share | 2,583.23 | −54.16 | −2.05% |
| NSE Banking Sector Index | 276.43 | −5.22 | −1.85% |
Kenya Government Bonds and Treasury Bills
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
| Security / tenor | Weighted average yield |
|---|---|
| 91-day Treasury bill | 8.748% |
| 182-day Treasury bill | 8.859% |
| 364-day Treasury bill | 9.027% |
| 2-year bond | 9.109% |
| 5-year bond | 9.230% |
| 10-year bond | 12.530% |
| 25-year bond | 13.602% |
Treasury bill auction
- 91-day, issue 2705: KSh 8.00 billion offered, KSh 14.34 billion bid and KSh 14.33 billion accepted; yield 8.7478%, down 0.22 basis points on the week.
- 182-day, issue 2679: KSh 10.00 billion offered, KSh 7.69 billion bid and accepted; yield 8.8591%, down 0.09 basis points.
- 364-day, issue 2634: KSh 10.00 billion offered, KSh 6.80 billion bid and KSh 6.77 billion accepted; yield 9.0267%, down 1.16 basis points.
- Auction totals: KSh 28.00 billion offered, KSh 28.83 billion bid and KSh 28.79 billion accepted; net borrowing KSh 8.64 billion. Value date: 26 October 2026.
Bond reopening
- Budget support: CBK reopened 15- and 30-year fixed-coupon bonds seeking KSh 50 billion, with yields quoted in the submission at 12.34% and 12.50%. The offer runs until 4 November 2026.
Kenya Forex
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
| Pair | CBK indicative rate | Context |
|---|---|---|
| USD / KES | 129.8900 | From 129.9100 in the prior session |
| GBP / KES | 173.5800 | From 173.9200 earlier in the week |
| EUR / KES | 145.3400 | From 145.8300 |
Retail conditions
- Dollar spreads: Retail dollar purchase quotes ranged between KSh 132.80 and KSh 133.50, wider than the official indicative rate.
- Corporate demand: Energy marketers and manufacturers placed strong dollar orders to clear import bills ahead of expected oil-driven price adjustments.
Buffers and regional crosses
- Export receipts and reserves: Tea, horticulture and remittances helped absorb import pressures. CBK reserves stood at $14.693 billion, equivalent to 5.9 months of imports.
- EAC rates per Kenyan shilling: KES/UGX 32.2600, up from 31.97 earlier in the week; KES/TZS 20.3900; KES/RWF 11.3500; KES/BIF 22.5100.
Kenya Economy and Commodities
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
Budget and taxation
- 2027/28 draft budget: The draft Budget Policy Statement proposes KSh 5.42 trillion in spending, including recurrent expenditure above KSh 4 trillion and development expenditure of KSh 915.8 billion. External borrowing is projected at KSh 423.8 billion.
- PAYE proposals: Treasury CS John Mbadi said a bill implementing the President’s tax directives would reach Parliament the following week, proposing tax-free salaries for 1.7 million low-income workers and higher taxes for high earners.
- Bank tax collections: The 2025 PwC/Kenya Bankers Association Total Tax Contribution Report shows tax collections by banks rose 13.24% to KSh 107.22 billion, exceeding taxes paid directly by lenders. Withholding tax on professional fees rose 292% and royalties 159%.
Energy and food supply
- Mombasa fuel arrivals: The KPA shipping schedule listed seven fuel and chemical tankers, including M.T. Bellatrix and M.T. Torm Sublime, discharging over 230,000 tonnes of gasoline and gasoil.
- Maize shortfall: The brief reports a 2.3 million-tonne maize import shortfall and a domestic harvest of 2.2 million tonnes following extreme weather, describing the sharpest output contraction against the five-year average in 50 years.
- Household prices: The CBK Agriculture Sector Survey warned of higher maize flour, wheat flour, fresh milk, sugar and garden pea prices due to dry weather, fuel and logistics costs.
Cash crops
- Tea auctions: Average black tea auction prices reached $2.33 per kilogram. Premium factories east of the Rift Valley earned KSh 1.6 billion in a week, with top grades above KSh 387 per kilogram.
- Macadamia warning: Kakuzi issued a profit warning linked to weak global macadamia pricing and export restrictions.
Kenya Corporate News
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
Aviation and trade
- Kenya–UK aviation agreement: A new security memorandum allows baggage arriving from Heathrow and Gatwick into JKIA to bypass repeat screening, aiming to reduce transfer delays and strengthen Nairobi’s hub role.
- US trade and AGOA: At the Germany–Africa trade conference in Nairobi, officials said Kenya expected to finalise a comprehensive US trade deal by December and was lobbying for a five-year AGOA extension.
Sustainability
- Thamani Asili: The government and international donors, including Walton and Cargill family heirs, closed a $160 million, approximately KSh 20.8 billion, conservation finance deal. Ten-year funding is tied to environmental policy measures protecting over 173,000 square kilometres from the Rift Valley to the Maasai Mara.
- Fly 748: The airline committed KSh 3.1 million over three years with the Kenya Forest Service to restore 10 acres of Ngong Forest, building on earlier work in Kakamega.
Corporate updates
- EABL: Nairobi County issued a demand for KSh 924 million in outstanding liquor-licence arrears.
- Turkana oil identity: The State Department for Petroleum invited public submissions for a Kenyan commercial name for Turkana crude. The brief quotes commercial production starting on 1 December 2026 at 20,000 barrels a day.
- Pension adequacy: Kenya’s debut Mercer CFA Institute Global Pension Index assessment gave adequacy a D grade despite B+ regulatory integrity, highlighting retirement income and healthcare pressures.
Kenya Real Estate
Figures as at · Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
Eastleigh building collapse
- Structural failure: A 12-storey residential building under construction collapsed on a crowded commercial street in Eastleigh, Nairobi.
- Rescue response: Multi-agency teams searched for people feared trapped in the basement and ground floors, where electronics and grocery shops reportedly operated without an occupation certificate. Police used tear gas to disperse crowds and prevent looting of neighbouring shops.
- Regulatory response: Governor Johnson Sakaja and police leaders promised action against building professionals involved, renewing calls for stricter structural and safety enforcement.
Regulation and property markets
- REIT incentives: Finance Act 2026 exemptions from capital gains tax and stamp duty on property transfers to registered REITs are encouraging corporate asset pooling, according to the submission.
- Satellite land: The Hass Land Index showed Ruiru up 2.8% and Juja up 1.2%, while Athi River fell 2.5% and Ngong 1.7% as outer-ring momentum cooled.
- Property credit: Real estate bank lending fell from KSh 452 billion to KSh 445.9 billion over the trailing 12 months as lenders managed exposure.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.89
CBK indicative rate.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October sessionGBP / KES
173.58
CBK indicative rate.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October sessionEUR / KES
145.34
CBK indicative rate.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
Equities
NSE All-Share
234.92
−3.21 points, −1.35%
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October sessionNSE 20-Share
4,177.41
−44.26 points, −1.05%
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October sessionNSE 25-Share
6,638.74
−118.58 points, −1.75%
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October sessionEquity turnover
KSh 596.44 million
23 October close.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October sessionMarket capitalisation
KSh 3,942.39 billion
Down KSh 53.86 billion.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
Rates
Central Bank Rate
8.75%
Policy rate shown in the supplied artwork.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October sessionKenya 10-year bond
12.530%
As quoted in the supplied brief.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session91-day Treasury bill
8.7478%
Auction value date: 26 October 2026.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session182-day Treasury bill
8.8591%
Auction value date: 26 October 2026.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session364-day Treasury bill
9.0267%
Auction value date: 26 October 2026.
As at
Serrari Group desk compilation supplied for 26 October 2026, reporting the 23 October session
At a glance
- 1Brent rose 3.14% to $116.72 a barrel, renewing inflation pressures as the S&P 500 fell 0.52% and the Dow lost 1.23%.
- 2The NSE All-Share fell 1.35% to 234.92 and equity turnover dropped to KSh 596.44 million; the shilling held at KSh 129.89 per dollar.
- 3Real estate bank lending declined to KSh 445.9 billion, while satellite land returns diverged: Ruiru gained 2.8% and Athi River fell 2.5%.
Sources
- Serrari Group desk compilation, 26 October 2026; Markets Snapshot – 23 October 2026
- Serrari Group supplied artwork, 26 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — market statistics
- Serrari published Africa macro data