
23 October 2026
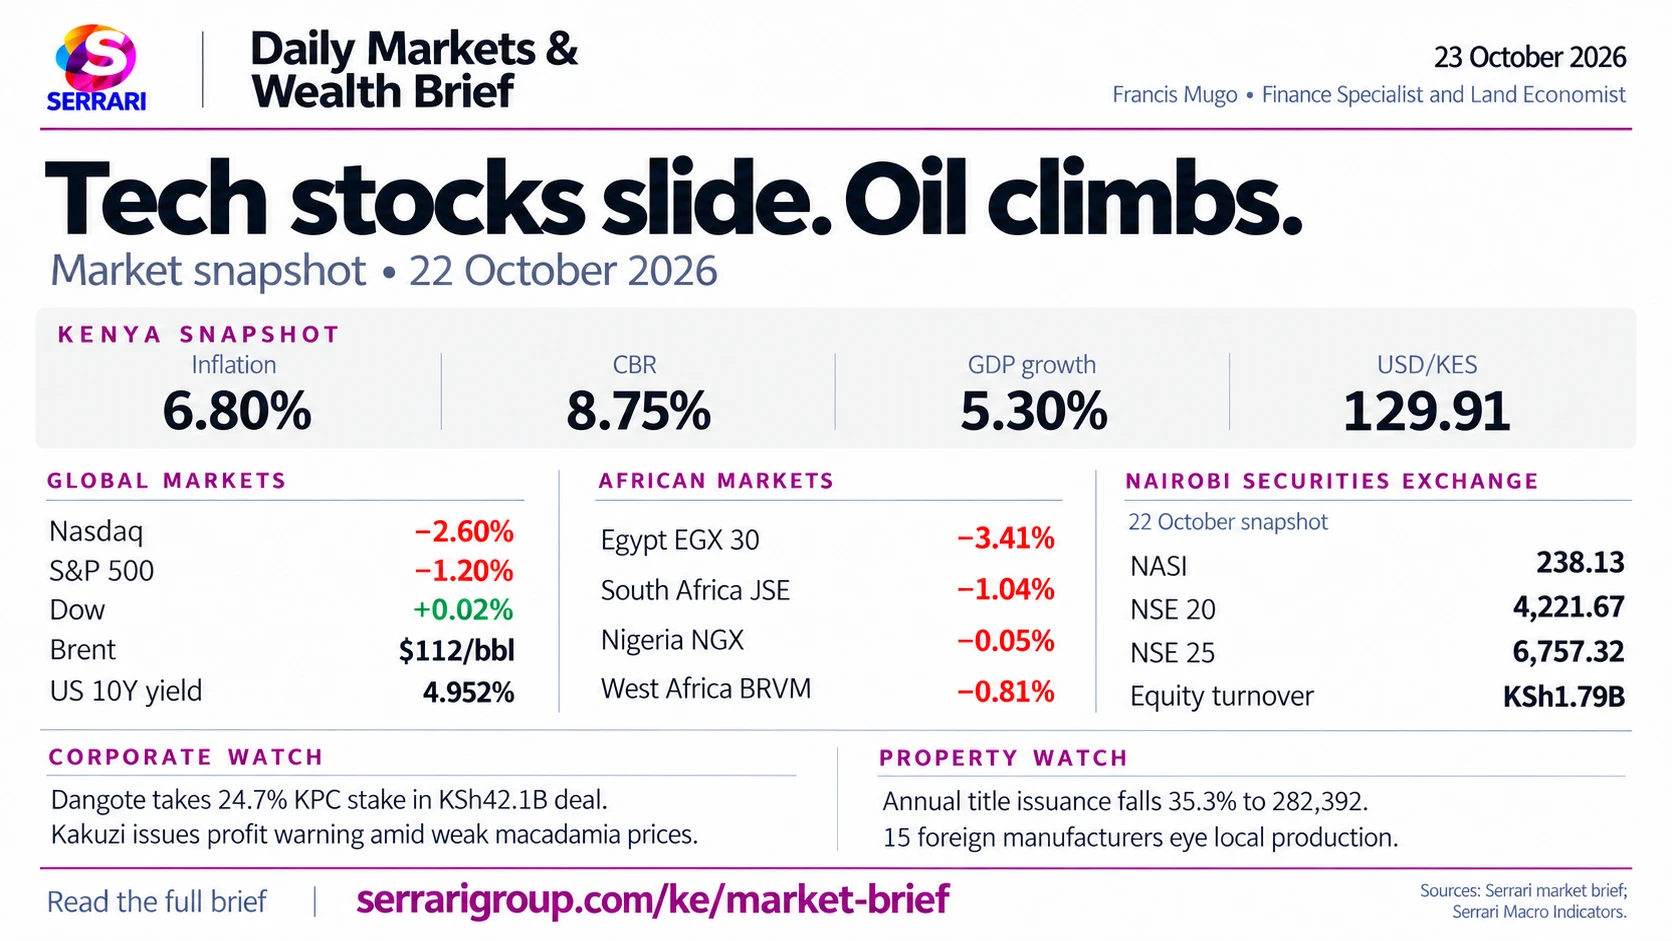
A slide in AI and chip stocks pulled the Nasdaq down 2.60%, its steepest drop since June, as attacks on Saudi oil infrastructure lifted Brent to $112, a five-month high. In Nairobi, equity turnover reached KSh 1.79 billion and Dangote Group took a 24.7% stake in Kenya Pipeline for KSh 42.1 billion.

Global Markets
Figures as at · Closing levels for Thursday 22 October 2026, as reported in this brief
A sharp correction in AI and semiconductor stocks, together with escalating conflict in the Middle East, dragged major indices lower across the US, Europe and Asia.
Major indices
| Index | Close | Change | Context |
|---|---|---|---|
| Nasdaq Composite | 26,008.86 | −694.00 (−2.60%) | Steepest drop since June on AI spending fears |
| S&P 500 | 7,663.43 | −93.74 (−1.20%) | Worst single day since July |
| Dow Jones Industrial Average | 52,867.98 | +11.89 (+0.02%) | A tiny gain, buffered by defensive sectors |
| Russell 2000 | 2,784.03 | +3.01 (+0.11%) | Smaller companies held minor gains |
| Euro Stoxx 50 | 6,095.00 | −118.00 (−1.90%) | Falling further from its August record |
| Stoxx 600 | 637.74 | −6.46 (−1.00%) | Steepest drop in three weeks; bank shares fell 4.2% |
| UK — FTSE 100 | — | −0.46% | Slid after hotter-than-expected UK inflation |
| South Korea — KOSPI | 5,666.00 | −3.52% | The region’s steepest fall on tech spending cuts |
| Japan — Nikkei 225 | 64,621.24 | −2.65% | Down 5% over the week |
| China — CSI 300 | — | −1.84% | Down 15% this year, its lowest since July 2025 |
| India — Nifty 50 | — | −0.82% | Moderate selling tracking global cues |
Geopolitics and energy
- Conflict escalation: Sentiment turned risk-averse after intelligence reports that the US and Israel may resume targeted attacks on Iran next month, and reports of an attack on a Saudi oil field.
- Oil and inflation: Crude spiked on Middle East supply risks, renewing inflation worries that weighed on bonds and stocks.
Big tech reality check
- Meta: Fell 2.7% after setting a 2026 capital spending outlook of $135 billion to $145 billion. A third straight quarter of negative free cash flow raised wider concern about when heavy AI investment will pay off.
- Tesla: Slid 4% early in the session. Earnings beat estimates, but automotive revenue fell year on year and battery supply constraints have left its largest vehicle backlog in four years.
- IBM and Texas Instruments: IBM fell nearly 6% as quarterly revenue growth slowed to 4.7% from 9.5% earlier in the year. Texas Instruments beat guidance on industrial and automotive demand, softening the chip sell-off slightly.
Bonds and pockets of strength
- Bond sell-off: Yields rose across the US, UK, Europe and Japan, and a hotter-than-expected UK inflation print reinforced the view that central banks will stay cautious on rate cuts into the winter.
- Lockheed Martin and Spotify: Lockheed Martin rose 4% after raising its fiscal 2026 guidance on sustained defence spending. Spotify jumped 7% on better-than-expected subscriber growth and wider gross margins.
- Roche: Nine-month sales rose 6% (7% in US dollars), led by pharmaceuticals and diagnostics.
- Emerging sectors: New research pointed to fast growth in peptide synthesis, driven by GLP-1 weight-loss drugs, and in urban air mobility (eVTOL), projected to grow at a 20.9% compound annual rate.
Forex
- USD/JPY: 156.96, down 0.75% to 0.84%, as the yen strengthened on safe-haven buying and fears of Bank of Japan intervention near 160.
- EUR/USD: 1.1222, down 0.09% to 0.18%, as fiscal panic over France’s budget deficit offset the benefit of falling US yields.
- GBP/USD: 1.3405, up 0.10%, supported by hot UK inflation of 3.5% and bets on a hawkish Bank of England.
- USD/CHF: 0.8211, down 0.38% to 0.42%, as the Swiss franc absorbed defensive flows out of equities.
- USD/CAD: 1.4019, down 0.21%, with the Canadian dollar cushioned by a 3% surge in crude.
- US dollar index: 101.60, down 0.08% or flat: falling US yields pulled the dollar down, but euro weakness kept the basket balanced.
Global Yields
Figures as at · Yields for 22 October 2026, as reported in this brief
A flight to safety drove down yields on US Treasuries and German Bunds, while fiscal strain held French and UK yields near multi-decade or multi-year highs.
Benchmark 10-year yields
| Bond | Yield | Change | Context |
|---|---|---|---|
| US 10-year Treasury | 4.952% | −19.3 bps | Largest one-day fall in over three years on safe-haven inflows |
| UK 10-year Gilt | 5.330% | Negligible / elevated | Near multi-year highs as 3.5% inflation cemented a hawkish Bank of England |
| Germany 10-year Bund | 3.340% | −7.0 bps | Flight-to-safety demand for the euro zone’s premier safe asset |
| France 10-year OAT | 5.082% | +6.5 bps | 24-year high (5.14% intraday) on budget gridlock and civil unrest |
| Italy 10-year BTP | 4.570% (approx.) | +10.5 bps | Euro zone contagion widened premiums over German debt |
| Japan 10-year JGB | Elevated | Steady | Tracking global “higher for longer” trends on energy prices |
Commodities
Figures as at · Closing prices for 22 October 2026, as reported in this brief
Middle East flashpoints drove energy to multi-month highs, while precious and industrial metals fell back on fears that central banks will keep rates higher for longer.
Closing prices
| Asset | Close | Change | Driver |
|---|---|---|---|
| Brent crude | $112.00 / bbl | +3.00% to +4.00% | Five-month high after drone strikes hit Saudi infrastructure |
| WTI crude | $99.47 / bbl | +2.39% | Neared $100 on Persian Gulf supply risk and large EIA inventory draws |
| Nymex natural gas | $2.798 / MMBtu | +0.29% | Low storage and Hormuz risks kept supply tight |
| Gold (spot) | $4,041.39 / oz | −2.40% | Two-month low as rising oil stoked rate-hike fears |
| Silver (spot) | $54.84 / oz | −5.40% | Slid on broader industrial and macro liquidation |
| Copper futures | — | Negative | Declined with weak equity sentiment in Asia |
| CBOT November soybeans | $12.53 / bu | +0.62% | Minor gains in volatile trading |
Africa
Figures as at · Closing levels for 22 October 2026, as reported in this brief
Major African indices
| Index | Close | Change | Context |
|---|---|---|---|
| South Africa — FTSE/JSE All Share | 108,518.52 | −1.04% | Pulled down with global indices on Middle East tensions |
| Nigeria — NGX All-Share | 245,002.85 | −0.05% | Mild consolidation; selling in large-cap banks |
| Egypt — EGX 30 | 51,052.26 | −3.41% | Broad losses wiped EGP 116 billion off market value |
| West Africa — BRVM Composite | 520.27 | −0.81% | Retraced ahead of Sonatel’s 10-for-1 stock split |
Sovereign yields
- South Africa: The local 10-year held near a one-month low at 8.75%–8.77%, up 0.06% on the day, after the mid-year budget review cut weekly fixed-rate auction volumes and proposed a formal fiscal anchor.
- Nigeria: The local 10-year stayed elevated at 17.05% after Debt Management Office auctions accepted higher stop rates amid tight bank liquidity. Dollar Eurobond yields moderated to an average of 8.61% on improved buying of shorter bonds.
- Egypt: Short-term debt yields stayed above 10.0% on a Eurobond basis, pressured by global capital outflows and Middle East energy volatility.
- Senegal: The benchmark Eurobond yield remained high at 20.8% after the debt treatments announced in September 2026.
Currencies
- South African rand: Eased 0.84% to R16.51 per dollar, R21.92 per pound and R18.45 per euro.
- Nigerian naira: Under pressure from corporate profit-taking and early holiday import demand: ₦1,339 per dollar officially and ₦1,370 parallel, ₦1,787 and ₦1,880 per pound, and ₦1,499 and ₦1,590 per euro.
- Egyptian pound: Hit a record low of EGP 55.30 per dollar as Middle East risk intensified, with EGP 74.28 per pound and EGP 62.31 per euro.
- CFA franc: Stable through its euro peg at ₣580.16 per dollar, ₣778.64 per pound and ₣655.96 per euro.
Commodities
- Brent crude: $111.98 a barrel, up 2.90%, its highest since May after a fresh wave of Houthi attacks in Saudi Arabia. The spike helps exporters such as Nigeria and Angola but strains fuel importers such as South Africa and Kenya.
- Cocoa: $5,552.95 a tonne, down 4.96%, on profit-taking and forecasts of a gradual supply recovery in Côte d’Ivoire and Ghana.
- Arabica coffee: 304.75 US cents a pound, down 3.61%, as Brazilian supply worries eased; low European stocks still support East and Central African exporters.
- Gold: $4,059.60 a troy ounce, down 1.97%. Uganda recently reported a 36% jump in export revenue, driven largely by gold processing.
- Copper: $6.38 a pound, down 2.50%, while producers in the DRC and Zambia keep scaling up logistics for the energy transition.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for Thursday 22 October 2026, as reported in this brief
Kenyan market figures are the 22 October close.
NSE indices
| Index | Close | Change |
|---|---|---|
| NSE All-Share (NASI) | 238.13 | −0.17 |
| NSE 20-Share | 4,221.67 | −28.76 |
| NSE 25-Share | 6,757.32 | −32.15 |
| NSE 10-Share | 2,637.39 | −13.83 |
| NSE Banking Sector Index | 281.65 | −1.74 |
Trading activity
- Turnover: Equity turnover reached KSh 1.79 billion on elevated volumes, with 44.31 million shares traded across 10,499 deals.
- Top gainer and loser: TPS Eastern Africa (Serena) led the gainers, and Shungwaya recorded the heaviest decline.
Government securities
- Treasury bills: The 91-day bill’s weighted average yield was 8.7478% (+0.22 bps on the week) on heavy demand for short-term safety; the 182-day 8.8591% (+0.09 bps), ending a multi-week drift lower; and the 364-day 9.0267% (+0.12 bps) as investors sought an inflation premium.
- This week’s auction: KSh 28.00 billion was offered: KSh 8.00 billion of 91-day (issue 2705) and KSh 10.00 billion each of 182-day (issue 2679) and 364-day (issue 2634) paper. Bids totalled KSh 28.83 billion and KSh 28.79 billion was accepted, a 103.0% subscription, with value date 26 October 2026.
- Bonds: The 2-year was flat at 9.089% and the 5-year at 9.214%. The 10-year eased 1.7 bps to 12.513%, well below the 14.34% priced in late 2024. The 15-year held at 13.000% and is forecast to face upward pressure to 13.58% by early 2027.
Corporate notices
- NCBA: Shares are suspended from 22 October to 2 November 2026 for Nedbank’s 66% stake acquisition.
- Kakuzi: Issued a profit warning on weak international macadamia prices and lower crop volumes.
Kenya Forex
Figures as at · Central Bank of Kenya indicative rates, 22 October 2026, as reported in this brief
- East African crosses: KES/TZS held steady at 20.3500, KES/UGX rose to 32.2600 from 31.97 earlier in the week, and KES/RWF eased to 11.3500 as regional trade demand fluctuated.
CBK indicative rates
| Pair | Rate | Context |
|---|---|---|
| USD / KES | 129.9100 | Upward pressure from strong dollar demand by oil marketers |
| GBP / KES | 173.9200 | Elevated after hot UK inflation data |
| EUR / KES | 145.8300 | Marginally up from 145.82 the previous day |
| CHF / KES | 157.4700 | Supported by global safety flows into the franc |
| ZAR / KES | 7.9200 | Modest trading within emerging-market baskets |
Kenya Tax, Economy and Commodities
Figures as at · As reported in this brief
Tax and regulation
- Total Tax Contribution Report: Treasury CS John Mbadi launched the 2025 report, which shows banks paid KSh 205.58 billion in tax.
- Multinationals: New rules introduce a 15% minimum top-up tax for multinationals with revenue above €750 million, and updated transfer pricing frameworks tighten KRA oversight of cross-border transactions.
- Fringe benefits: The KRA raised the rate used for Fringe Benefit Tax and deemed interest to 9% for October–December 2026, up from 8%.
- Digital services: Legal advisories issued on 22 October set out enforcement of the Significant Economic Presence Tax, an effective 3% tax on gross turnover for foreign non-resident digital businesses selling in Kenya.
- PAYE: After President Ruto’s Mashujaa Day plan to exempt workers earning KSh 32,333 or less from income tax, the Kenya Bankers Association issued technical demands on PAYE changes before the bill goes to the National Assembly in November.
Economy and infrastructure
- IMF outlook: The IMF’s October 2026 World Economic Outlook shows Kenya has overtaken Ethiopia as Eastern Africa’s largest economy in nominal US dollar terms.
- SGR extension: The revised budget for extending the Standard Gauge Railway to Kisumu and Malaba reached KSh 650 billion, and Kenya is considering securitised bonds backed by Railway Development Levy collections.
Commodities
- Coffee: Nairobi Coffee Exchange prices averaged $316.61 per 50 kg bag, up 27% by value, as Sale 03 volume rose 16.5% to 17,442 bags.
- Tea: The latest Mombasa auction average was $2.36 a kilo and firming, up 15% year on year, as growers face a new 0.8% export levy.
- Gold: 24-carat spot gold fell 1.55% to KSh 16,924.68 a gram on international safe-haven consolidation.
Kenya Corporate News
Figures as at · As reported in this brief
Corporate developments
| Company | Development | Impact and figures | Outlook |
|---|---|---|---|
| Kenya Pipeline Company (KPC) | Dangote Group enters the share register | KSh 42.1 billion block deal for a 24.7% stake | Shares rose 7.9%; aligned with the upcoming Lamu refinery |
| Sanlam Allianz Holdings | Leadership transition | Jacqueline Karasha named CEO; Patrick Tumbo retires | Overseeing absorption of the life subsidiary; half-year net profit rose to KSh 124.6 million |
| Quickmart | UK government funding injection | IPO block allocation | The British development finance arm acquired a 6.6% stake |
| Kakuzi | Second profit warning of 2026 | Fifth warning in five years; half-year profit fell 97.6% | Strained by depressed global macadamia markets and shipping bottlenecks |
| Limuru Tea | Company secretary exits | Advocate Leila Chebet appointed company secretary | The previous holder left after just five months |
Real Estate
Figures as at · As reported in this brief
Land and construction
- Title deeds: For the first time in five years, the Ministry of Lands recorded a fall in annual title deed issuance, down 35.3% to 282,392 for the year to June 2026. Tighter bank lending and a shift from speculative raw land towards serviced plots in managed corridors such as Ruiru, Juja and the Eastern Bypass are behind the drop.
- Local manufacturing: On the second day of the Big 5 Construct Kenya exhibition at the Sarit Expo Centre, KNCCI said 15 foreign manufacturers from countries including Italy, Turkey, China and Germany have formally expressed interest in building local factories to supply AfCFTA markets and the affordable housing pipeline.
Market shifts
- Corporate pressure: In the Central Bank of Kenya’s latest Market Perceptions Survey, 33% of real estate respondents cited industry decline and another 33% operating cost reduction as the main drivers of staffing decisions. Firms are turning to digital tools to cut overheads rather than expanding.
- Yield over land: Younger investors are treating property as a capital efficiency tool rather than holding idle land, favouring high-utility micro-units and mixed-use developments with immediate cash flow, rental yields of 7% to 10% in satellite areas and sustainable service charges.
- After the mega mall: Institutional capital is moving away from large speculative suburban malls and high-end apartments, which face oversupply and vacancies, towards well-located industrial logistics and convenience-led mixed-use retail.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.91
As at
Central Bank of Kenya indicative rate, as reported in this briefGBP / KES
173.92
As at
Central Bank of Kenya indicative rate, as reported in this briefEUR / KES
145.83
As at
Central Bank of Kenya indicative rate, as reported in this briefCHF / KES
157.47
As at
Central Bank of Kenya indicative rate, as reported in this briefZAR / KES
7.92
As at
Central Bank of Kenya indicative rate, as reported in this brief
Equities
NSE All-Share
238.13
−0.17
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,221.67
−28.76
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,757.32
−32.15
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 1.79 billion
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee decision of 7 October 202691-day Treasury bill
8.7478%
As at
Weighted average yield, Central Bank of Kenya auction, as reported in this brief182-day Treasury bill
8.8591%
As at
Weighted average yield, Central Bank of Kenya auction, as reported in this brief364-day Treasury bill
9.0267%
As at
Weighted average yield, Central Bank of Kenya auction, as reported in this briefKenya 2-year bond
9.089%
As at
Benchmark yield, as reported in this briefKenya 5-year bond
9.214%
As at
Benchmark yield, as reported in this briefKenya 10-year bond
12.513%
As at
Benchmark yield, as reported in this briefKenya 15-year bond
13.000%
As at
Benchmark yield, as reported in this brief
At a glance
- 1Dangote Group entered Kenya Pipeline’s share register through a KSh 42.1 billion block deal for 24.7%, a move aligned with its planned Lamu refinery. KPC shares rose 7.9%.
- 2Kakuzi issued its second profit warning of 2026 and its fifth in five years, after first-half profit fell 97.6% on weak global macadamia prices, lower crop volumes and shipping bottlenecks.
- 3Title deed issuance fell 35.3% to 282,392 in the year to June 2026, the first contraction in five years, as bank credit tightened and buyers moved from speculative land to serviced plots.
Sources
- Serrari Group desk compilation, 23 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data