
22 October 2026
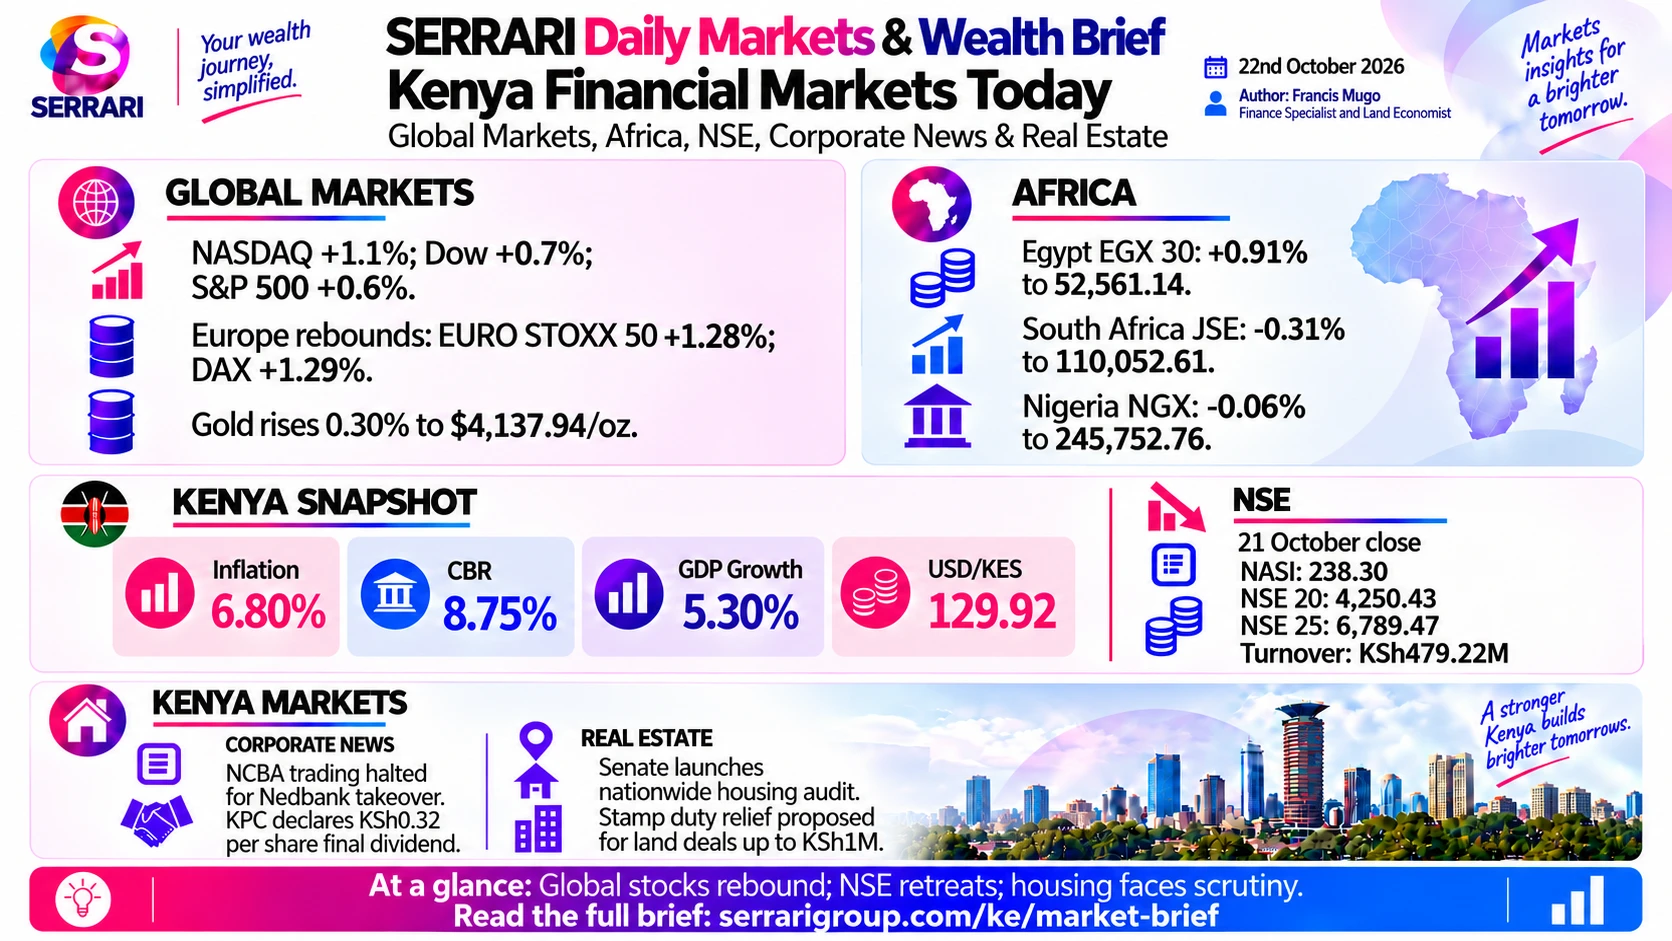
SpaceX’s results and talk of a Tesla merger lifted Wall Street, with the Nasdaq up 1.1%, while France’s 10-year yield crossed 5% for the first time since 2002. In Nairobi, NCBA shares were suspended for Nedbank’s takeover and Aliko Dangote said his group had bought 25% of Kenya Pipeline.

Global Markets
Figures as at · Closing levels for Wednesday 21 October 2026, as reported in this brief
SpaceX’s results and merger talk with Tesla revived tech stocks, and record-low US housing data eased fears of aggressive Fed policy. In Europe, France’s budget and political crisis pushed its 10-year yield past 5%, while Asia recovered sharply from a multi-day AI sell-off.
Major indices
| Index | Close | Change | Context |
|---|---|---|---|
| Nasdaq Composite | 26,702.86 | +1.1% | +278.04 points |
| Dow Jones Industrial Average | 52,856.09 | +0.7% | +360.21 points |
| S&P 500 | 7,757.17 | +0.6% | +44.60 points |
| Russell 2000 | 2,781.02 | +0.3% | +7.60 points |
| Euro Stoxx 50 | 6,200.20 | +1.28% | Broad macro relief rally and solid corporate earnings forecasts |
| Germany — DAX 40 | 25,632.00 | +1.29% | Led European gains as bond markets steadied after the oil price retreat |
| France — CAC 40 | ~8,190.00 | +0.12% | Lagged as political unrest pushed the 10-year yield to a 24-year high of 5% |
| UK — FTSE 100 | ~8,310.00 | −0.10% | Slipped late ahead of UK inflation data |
| Japan — Nikkei 225 | 64,621.24 | +0.85% | Shrugged off weaker trade data to track the US tech bounce |
| South Korea — KOSPI | 2,674.34 | +2.70% to +3.0% | Technical rebound in AI names such as Elice Group |
| Hong Kong — Hang Seng | 23,651.87 | −0.90% | Cooling electronics demand and a 22.9% drop in mainland smartphone shipments |
| China — Shanghai Composite | 3,713.03 | −0.60% | Reversed opening gains on downbeat third-quarter earnings from heavyweights |
United States
- SpaceX and Tesla: SpaceX (SPCX) reported third-quarter revenue of $14.58 billion, with its internal AI infrastructure unit growing ninefold. Elon Musk confirmed that SpaceX and Tesla (TSLA) have formed special board committees to explore a full merger. Tesla shares jumped 3.5% and Super Micro Computer (SMCI) surged 10.3%.
- Housing: US pending home sales plummeted 7.3% in September to their lowest level since record-keeping began in 2001. With 30-year fixed mortgages at 7.5%, the slump cooled fears of aggressive near-term Fed policy, and the 10-year Treasury yield eased to 5.09%.
- Energy: Fresh drone attacks on merchant shipping near the Strait of Hormuz kept energy prices volatile. Brent crude futures rallied back toward $110 a barrel, keeping wholesale inflation worries elevated.
Europe
- The 5% threshold: For the first time since July 2002, France’s 10-year OAT yield surged past 5.0%. Violent nationwide protests over high prices and a proposed €43 billion austerity package have shaken investor confidence.
- The spread: The French–German 10-year spread widened to 150–157 basis points, a gap unseen since the euro zone sovereign debt crisis. Goldman Sachs warned that while spillover risks are lower than in 2011, France’s debt of 119% of GDP presents structural challenges that tools such as the ECB’s TPI may not easily cure.
- Corporate refinancing: High benchmark yields and volatility forced companies to postpone more than $5 billion of planned bond and loan issues this month.
Asia
- Earnings rebound: Tokyo and Seoul rallied after large after-hours earnings beats on Wall Street, led by SpaceX’s revenue and strong forward guidance from Super Micro Computer, erasing deep losses from a multi-day AI sell-off.
- South Korea: The KOSPI jumped nearly 3%. AI firm Elice Group hit its daily upper limit of 29.9%, recouping the losses from its volatile debut earlier in the week.
- China: Third-quarter growth of 4.5% year on year, at the upper bound of Beijing’s target, supported the offshore yuan and calmed demand fears in frontier markets.
Forex
- US dollar index: 101.50 to 101.71, softening to a three-week low after record-low US pending home sales and cooling oil prices.
- EUR/USD: $1.1224 to $1.1234, range-bound and soft, as political gridlock and the widening French–German spread capped any recovery.
- GBP/USD: $1.3380, up 0.60%, outperforming after an unexpected drop in UK unemployment and ahead of hot inflation data.
- USD/JPY: 157.94 to 158.00, with the yen firming after a historic 20-year government bond auction drew heavy institutional demand.
- USD/CNH: 6.6774, the offshore yuan’s strongest level since mid-2022, after China’s third-quarter growth beat expectations.
Global Yields
Figures as at · Yields for 21 October 2026, as reported in this brief
France’s 10-year yield hit a 24-year high above 5%, and the French–German spread widened to 150–157 basis points, its widest since the euro zone debt crisis.
Government bond yields
| Bond | Yield | Change | Context |
|---|---|---|---|
| US 2-year Treasury | 4.789% | +0.4 bps (stable) | Traders price an 85% probability that the Fed holds rates next week |
| US 5-year Treasury | 4.940% | Bounded | Consolidated near 5.0% as investors weighed rich valuations against carry |
| US 10-year Treasury | 5.111% to 5.12% | −0.4 bps | Below its recent 24-year peak of 5.36% as the 7.3% plunge in pending home sales cushioned selling |
| US 30-year Treasury | 5.426% | Unchanged | Flat ahead of a $13 billion 20-year bond auction |
| France 10-year OAT | 5.002% | +8.0 bps | 24-year high amid protests and gridlock over a €43 billion spending cut package |
| Germany 10-year Bund | ~3.40% | −6.0 bps | Safe-haven bid; French–German spread at 150–157 bps |
| UK 10-year Gilt | ~4.45% | Bounded | Narrow band ahead of economic data and policy updates |
| Japan 10-year JGB | 2.90% to 2.94% | Stable near high | Near three-decade peaks after Prime Minister Sanae Takaichi pledged fiscal discipline over Japan’s $7 trillion debt |
| China 10-year | ~2.18% | Unchanged | Cooling electronics demand weighed against central bank liquidity measures |
Commodities
Figures as at · Closing prices for 21 October 2026, as reported in this brief
- Oil demand easing: Crude softened from early-week spikes, with Brent trading near $110.60 a barrel. A shipping corridor under international protection in the Persian Gulf pushed exports back to pre-war levels of 24 million barrels a day, easing near-term inflation worries.
Closing prices
| Asset | Close | Change | Driver |
|---|---|---|---|
| Brent crude futures | $108.42 to $110.50 / bbl | −0.30% (late day) | Pulled back from an intraday high of $111.99 but held near multi-month peaks on Middle East shipping risks |
| WTI crude futures | $97.69 to $99.31 / bbl | −0.13% | Retraced on news that some sanctions and tariffs on Russian exports are being modified |
| Gold (spot) | $4,137.94 / oz | +0.30% | Rebounded off a one-week low as yields eased ahead of next week’s FOMC meeting |
| Silver (spot) | $57.73 / oz | −0.40% | Under technical pressure after breaking below its short-term baseline |
| Seaborne iron ore (61%) | $90.40 / dmt | Softening | Traders await a turn in Chinese finished-steel orders |
| LME nickel futures | $16,310.00 / t | +4.10% | Three-week high on the prospect of coordinated supply cuts by top producers |
| US wheat futures | $6.40 / bu | −2.0% | Two-month low on renewed hopes of a Russia–Ukraine deal |
Africa
Figures as at · Closing levels for 21 October 2026, as reported in this brief
Major African indices
| Index | Close | Change | Year to date |
|---|---|---|---|
| Egypt — EGX 30 | 52,561.14 | +0.91% | +23.1% |
| South Africa — JSE All Share | 110,052.61 | −0.31% | −6.3% |
| Nigeria — NGX All-Share | 245,752.76 | −0.06% | +59.2% |
| West Africa — BRVM Composite | 524.52 | −0.94% | +1.7% |
Sovereign yields
- South Africa: The 10-year fell 12.5 basis points to 8.77%, a one-month low, as investors chased debt after a disciplined medium-term budget update.
- Nigeria: The 10-year stood at 16.94% to 17.05%, up 46 basis points on the week, a regional outlier as primary auction stop rates climbed with the Debt Management Office accepting higher bids.
- Egypt: The 10-year was flat at 23.44%, a fresh high for the year, with the curve deeply inverted by short-term cash needs.
- West Africa: Regional 10-year BRVM paper held at about 6.55%, anchored by the regional central bank framework and stable liquidity.
Currencies
- South African rand: Stable at R16.37 to R16.42 per dollar, closing at R16.3749 on the interbank market after the National Treasury announced cuts to weekly fixed-rate debt auctions.
- Nigerian naira: Held in a tight ₦1,332.64 to ₦1,334.99 corridor at the official window, with parallel street rates near ₦1,380.
- Egyptian pound: Softened slightly to EGP 54.34 to EGP 54.44, near multi-month highs; the Central Bank of Egypt’s final average rate was EGP 54.4377.
- CFA franc: Bounded at about ₣584.18 per dollar, moving with the euro through its peg.
Commodities and Africa
- Brent crude: $110.85 a barrel, up 1.90%: it lifts foreign cash inflows for Nigeria but worsens Egypt’s import bill.
- Gold: $4,139.10 an ounce, flat within a narrow band for South Africa and Egypt and down 5.2% year on year as traders brace for interest rate moves.
- Cocoa: US cocoa futures fell 2.00% to $5,679.50 a tonne as seasonal West African main-crop deliveries reached ports.
- South African coal: Export coal was $109.60 a tonne. Prices remain firm, but local output volumes are down more than 12% year on year because of rail logistics problems.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for Wednesday 21 October 2026, as reported in this brief
Kenyan market figures are the 21 October close. Every NSE index closed lower.
NSE indices
| Index | Close | Change |
|---|---|---|
| NSE All-Share (NASI) | 238.30 | −3.38 |
| NSE 20-Share | 4,250.43 | −13.40 |
| NSE 25-Share | 6,789.47 | −76.47 |
| NSE 10-Share | 2,651.22 | −44.86 |
| Banking Sector Index | 283.39 | −0.73 |
Session aggregates
- Market capitalisation: KSh 3.999 trillion, down KSh 56.76 billion from the previous session.
- Equity turnover: KSh 479.22 million on 14.71 million shares traded across 13,302 deals.
- ETFs: The ABSA NewGold ETF recorded 43 deals and turnover of KSh 2,239,579.
Government securities
- 91-day bill: 8.750%, unchanged and anchored to the 8.75% Central Bank Rate.
- 182-day bill: 8.860%, stable, with healthy demand capping upward pressure.
- 364-day bill: 9.038%, down marginally, as oversubscribed bidding keeps the yield near 9.04%.
- 2-year bond: 9.200%, bounded, with the curve showing normal convexity as longer paper pulls a premium.
- 10-year bond: 12.530%, flat and well below its historical peaks, against lows of 11.20% early in the year.
- Infrastructure bond: IFB1/2021/021 (16-year) compressed to about 12.737%, chased heavily by the KSh 340 billion National Infrastructure Fund to clear banking liquidity.
Kenya Forex
Figures as at · Closing rates for 21 October 2026, as reported in this brief
The shilling held steady against the dollar at 129.9200 after touching minor resistance at 129.95, and gained against the pound and the euro.
- East African crosses: The Ugandan shilling exchanged officially at 32.17, the Tanzanian shilling settled at 20.39 and the Burundian franc closed at 23.08.
Closing rates
| Pair | Rate | Context |
|---|---|---|
| USD / KES | 129.92 | Stable after touching minor multi-month resistance at 129.95 |
| GBP / KES | 173.76 | Shilling gained from the week’s open of 174.60 |
| EUR / KES | 145.82 | Shilling gained, erasing early-session pressure to settle at 145.8200 |
| ZAR / KES | 7.91 | Shilling softened as the rand rallied on South Africa’s budget supply cuts |
Kenya Economy, Energy and Commodities
Figures as at · As reported in this brief
Macroeconomy and currency
- Fuel and inflation: The Central Bank of Kenya said high global energy prices, worsened by Middle East tensions, are creating domestic price pressure. Inflation stands at 6.8%, pushing up distribution and transport costs for key farm products.
- CBK indicative rates: The Central Bank of Kenya’s indicative rates showed a steady baseline, with the US dollar at KES 129.24, the British pound at KES 174.60 and the euro at KES 151.23.
- Largest in East Africa: The IMF’s latest World Economic Outlook shows Kenya has overtaken Ethiopia as East Africa’s largest economy in nominal US dollar terms, with GDP estimates of $140–$151 billion after major exchange-rate adjustments.
Energy and infrastructure
- Turkana crude: President William Ruto announced that Kenya will begin exporting high-wax crude from the Turkana Lokichar Basin in December 2026, 14 years after the discovery. Dangote Group has broken ground on a 700,000-barrel-a-day refinery at Lamu port.
- Big 5 Construct Kenya: The ninth edition opened at the Sarit Expo Centre, with more than 150 companies from 25 countries pitching to Kenya’s housing and infrastructure pipeline, alongside the launch of the National Buildings Decarbonization Roadmap.
Export commodities
- Tea: Black CTC averaged $3.10 a kilo at the Mombasa auction, holding around $3.102, but a new local export levy and Middle East shipping delays pushed unsold inventory to near-record levels of 23% to 27%.
- Coffee: Clean beans sold for $293.00 to $336.25 per 50 kg bag at Nairobi Coffee Exchange Sale 2 of the 2026/27 crop year. Top Grade AA lots averaged $336.25, and auction volumes topped KSh 695 million.
- Cut roses: Premiums of KES 15 to KES 35 a stem. Export earnings are up 16.7% this year, but air freight has risen from $3.10 to nearly $5.00 a kilo because of geopolitical constraints, squeezing margins.
Kenya Corporate News
Figures as at · As reported in this brief
Corporate actions
| Company | Action | Value | Books closure | Payment / effective |
|---|---|---|---|---|
| NCBA Group | Trading suspension | — | 21 October 2026 | 2 November 2026 |
| Kenya Pipeline (KPC) | Final dividend | KES 0.32 | 30 November 2026 | To be announced |
| BOC Kenya | Interim dividend | KES 4.00 | 21 September 2026 | 19 October 2026 |
Deals and leadership
- Dangote and Kenya Pipeline: Aliko Dangote confirmed at the Financial Times Africa Summit in London that his group has acquired a 25% stake in Kenya Pipeline Company. That names the buyer behind the KSh 42.5 billion block trade of 4.5 billion shares earlier in the week. The government offloaded a 65% public stake through an IPO earlier this year, and the purchase complements Dangote’s $16 billion refinery project in Lamu.
- Nedbank and NCBA: NCBA Group shares are suspended on the NSE from 21 October until 2 November 2026. The nine-day halt allows register reconciliation as Nedbank Group completes its KSh 110 billion (R13.9 billion) purchase of a 66% controlling stake. NCBA will operate as a Nedbank subsidiary but keep its NSE listing and local brand, with a 34% free float.
- Sanlam Allianz: Jacqueline Karasha will become chief executive of Sanlam Allianz Holdings (Kenya) on 1 November 2026, succeeding Dr Patrick Tumbo, who retires after eight years. The group is transferring its entire life insurance business into the NSE-listed parent.
- Kenya Pipeline dividend: KPC declared a final dividend of 32 cents a share, KSh 5.9 billion in total, with books closing on 30 November 2026.
Industry trends
- Insurance: Analysts at AAR Insurance Group expect a wave of consolidation, as tighter international accounting standards and solvency rules push smaller, under-capitalised insurers towards buyouts or mergers.
- Hotels: Central Bank of Kenya data show forward hotel bookings of 59% for October and 56% for November, well ahead of 2025, driven by local conferences, regional government functions and international business travel.
Real Estate
Figures as at · As reported in this brief
Average annual price movements by segment
| Asset | Strata / location | Annual change | Quarter on quarter |
|---|---|---|---|
| Standalone units | Nairobi upper-end | +4.5% to +13.6% | +0.7% |
| Standalone units | Nairobi middle / satellite | Easing | Softening |
| Apartment units | Nairobi upper and other | Modest gains | +3.6% |
| Apartment units | Nairobi middle-income | −1.1% (index drop) | Stagnant |
| Regional land market | Outside municipalities | Softening activity | Low transactions |
Policy and tax
- Stamp duty: Following President Ruto’s Mashujaa Day directive, the National Treasury is preparing amendments to exempt all property transactions of KSh 1 million or less from stamp duty, saving low-income buyers up to KSh 40,000 per urban transaction. To offset the cost, a progressive structure would replace the flat rate for luxury and high-value property.
- Housing audit: The Senate Housing Committee has opened an inquiry into the Affordable Housing Programme, seeking project-by-project audits across all 47 counties of construction spending against estimates, the occupancy of completed blocks and how beneficiaries are selected. It follows a 20% mandatory price increase by the State Department for Housing earlier in October.
Prices and demand
- KNBS index: Home prices rose a modest 2.2% over the year. Standalone houses rose 3.1% on demand for maisonettes, villas and townhouses, led by Nairobi’s upper market. Apartments rose just 0.1%: upper-market units gained, but the index for Nairobi’s middle-income areas and towns outside the capital fell on oversupply and cooling demand.
- Commercial property: Asset managers at the Nairobi Realtors Summit said office demand remains subdued by high vacancies, and institutional capital is rotating into retail (21%), hotels and leisure (18%) and data centres (17%).
Development and land
- Lamu: After the groundbreaking of the KSh 2 trillion refinery at Lamu Port, planners have set aside 9,000 acres for a smart coastal city and a manufacturing special economic zone.
- Njiru: The estate of the late Gerishon Kirima reissued warnings to buyers, developers and investment groups against paying for or transferring titles to parcels in the contested 1,000-acre Njiru block in Nairobi East.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.92
As at
Closing rate, as reported in this briefGBP / KES
173.76
As at
Closing rate, as reported in this briefEUR / KES
145.82
As at
Closing rate, as reported in this briefZAR / KES
7.91
As at
Closing rate, as reported in this brief
Equities
NSE All-Share
238.30
−3.38
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,250.43
−13.40
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,789.47
−76.47
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 479.22 million
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KSh 3.999 trillion
−KSh 56.76 billion
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee decision of 7 October 202691-day Treasury bill
8.750%
As at
Closing yield, as reported in this brief182-day Treasury bill
8.860%
As at
Closing yield, as reported in this brief364-day Treasury bill
9.038%
As at
Closing yield, as reported in this briefKenya 2-year bond
9.200%
As at
Closing yield, as reported in this briefKenya 10-year bond
12.530%
As at
Closing yield, as reported in this brief
At a glance
- 1Aliko Dangote confirmed his group has bought 25% of Kenya Pipeline, naming the buyer behind this week’s KSh 42.5 billion block trade of 4.5 billion shares. KPC declared a final dividend of KSh 0.32 a share, KSh 5.9 billion in total, with books closing on 30 November.
- 2NCBA shares are suspended from 21 October to 2 November while Nedbank completes its KSh 110 billion purchase of a 66% stake. The NSE retreated, with the NASI down 3.38 to 238.30 and market capitalisation down KSh 56.76 billion to KSh 3.999 trillion.
- 3The Treasury is drafting a stamp duty exemption for property deals of KSh 1 million or less, and the Senate has opened a project-by-project audit of the Affordable Housing Programme across all 47 counties.
Sources
- Serrari Group desk compilation, 22 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data