
21 October 2026
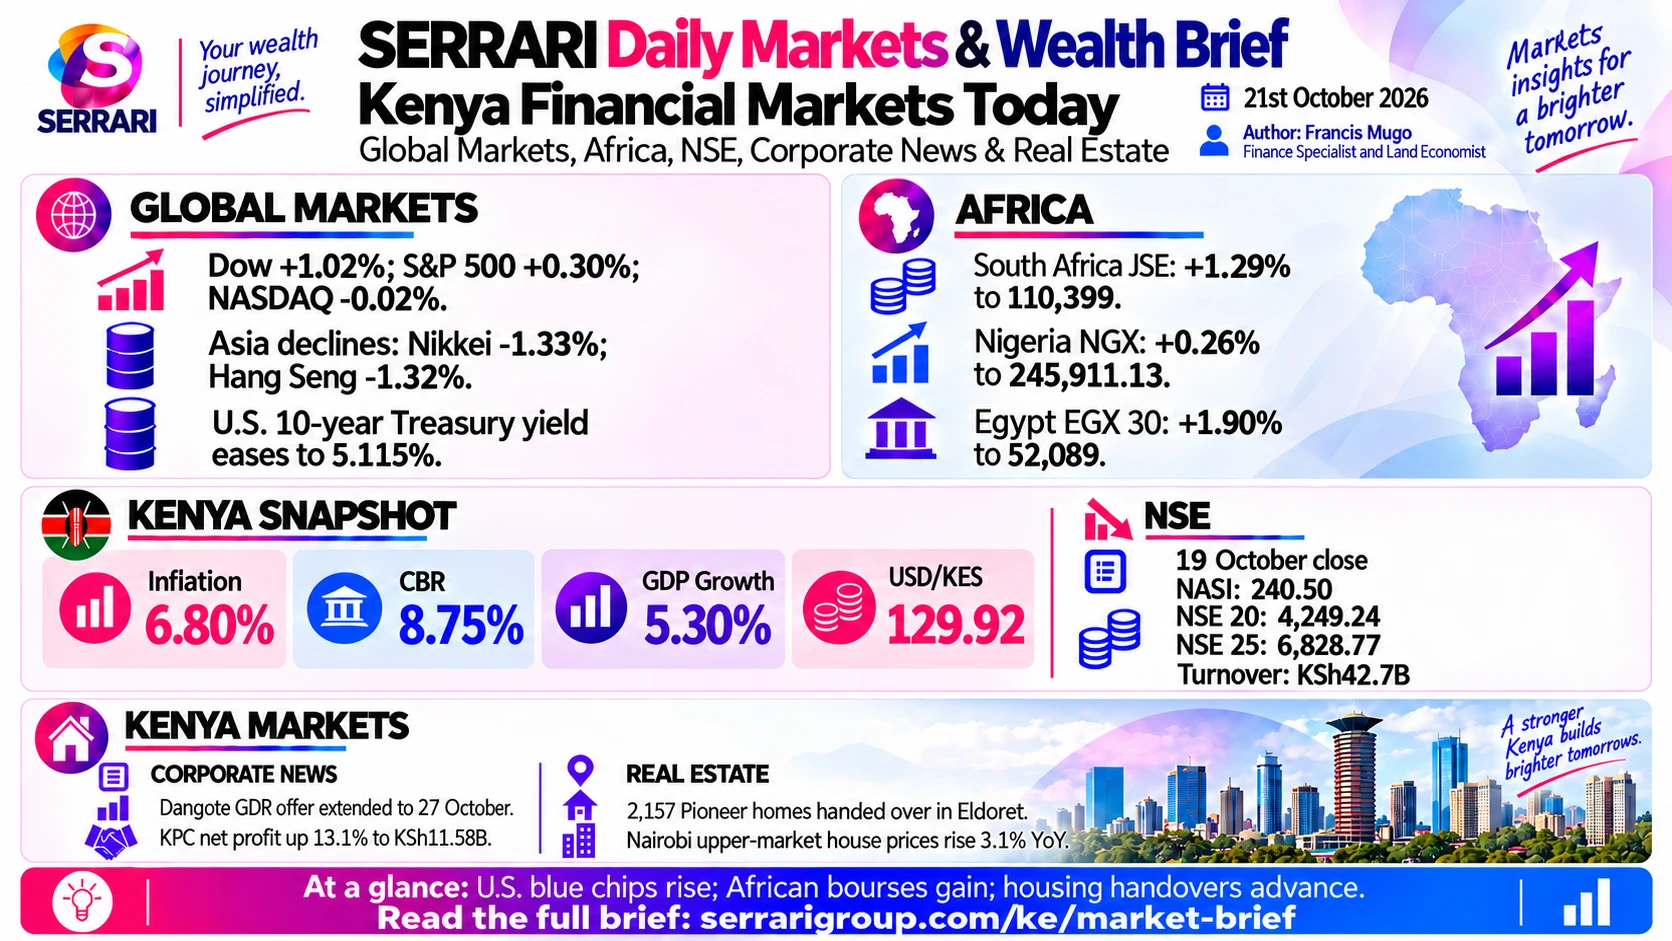
Blue chips led Wall Street higher, with the Dow up 1.02% on strong earnings, while an AI sell-off dragged Asia lower. In Nairobi, a KSh 42.5 billion block trade in Kenya Pipeline shares lifted turnover to KSh 42.7 billion as Nedbank completed its takeover of NCBA.

Global Markets
Figures as at · Closing levels for Tuesday 20 October 2026, as reported in this brief
Strong earnings lifted US blue chips, while a sell-off in AI hardware dragged Asia lower. Analysts described a move from "buy everything AI" to "question everything AI", with money rotating out of mega-cap tech into healthcare and small caps. European markets fell further as violent protests in France led to curfews in major cities.
Major indices
| Index | Close | Change | Context |
|---|---|---|---|
| Dow Jones Industrial Average | 52,495.88 | +1.02% | Strong industrial earnings; 3M up nearly 6% |
| S&P 500 | 7,712.57 | +0.30% | Rebounded late as energy costs eased |
| Nasdaq Composite | 26,424.82 | −0.02% | Profit-taking in mega-cap tech |
| Euro Stoxx 50 | 6,121.66 | −0.38% | Bank selling and French political worries |
| Nikkei 225 | 64,075.42 | −1.33% | Rotation and tech valuation nerves ahead of earnings |
| Hang Seng | 23,867.74 | −1.32% | Regional AI risk aversion |
Deals and earnings
- Salesforce and Braze: Salesforce agreed to buy Braze for $5.66 billion in cash, sending Braze shares up 51.70%.
- SpaceX and Tesla: Elon Musk said both companies have set up special committees to explore a merger. SpaceX shares rose 6% after its third-quarter revenue doubled.
- Industrials and defence: 3M jumped nearly 6% after beating earnings forecasts and raising its full-year guidance, and Northrop Grumman gained more than 4.5%.
- An AI debut that fell: South Korean data-centre and AI developer Elice Inc. fell as much as 32%–35% on its first day of trading in Seoul.
Energy, rates and safe havens
- Oil: The IEA warned that energy markets remain highly vulnerable to overlapping Middle East crises and will not normalise before the end of 2027. Brent traded above $110 a barrel early in the session before easing.
- The Fed: Bank of America kept its contrarian call for a Federal Reserve hike at the October meeting, citing a worsening core PCE inflation outlook, even though markets price low odds of one.
- Gold and bitcoin: Gold futures slipped about 0.5% to near $4,140 an ounce as the dollar index firmed around 101.73. Bitcoin held near $82,400.
Forex
- EUR/USD: 1.0820, down 0.35%, as the widening French–German yield spread drove capital out of the euro zone.
- USD/JPY: 149.25, down 0.21%, with the yen strengthening below 150 on strong demand for domestic bonds and talk of Bank of Japan tightening.
- GBP/USD: 1.2942, up 0.12%, on sticky UK inflation that leaves the Bank of England less room to cut.
- USD/CNY: 7.1350, up 0.05%, held steady by state bank dollar sales and tight liquidity controls.
- AUD/USD: 0.6654, down 0.41%, falling with the broader commodity sell-off and cooler Brent prices.
Global Yields
Figures as at · Yields for 20 October 2026, as reported in this brief
The French–German spread widened to 148 basis points, the widest since the 2012 euro zone crisis.
Benchmark 10-year yields
| Bond | Yield | Change | Context |
|---|---|---|---|
| US 10-year Treasury | 5.115% | −3.1 bps | Off a 24-year high after weak October housing data |
| Germany 10-year Bund | 3.44% | +1.0 bps | Safe-haven demand amid regional instability |
| France 10-year OAT | 4.94% | +7.0 bps | Spread to Bunds at 148 bps, the widest since 2012 |
| Italy 10-year BTP | 4.57% | +2.0 bps | Followed France on fiscal contagion and austerity protests |
| Japan 10-year JGB | 2.90% | −2.0 bps | Eased on political pledges of debt discipline |
| China 10-year | 1.64% | −2.0 bps | Eased on continued policy support |
Commodities
Figures as at · Closing prices for 20 October 2026, as reported in this brief
- Oil early in the session: The IEA warned that energy markets remain highly vulnerable to overlapping Middle East crises and will not normalise through 2027. Brent traded above $110 a barrel early on before futures cooled.
- Gold futures and bitcoin: Gold futures slipped about 0.5% to near $4,140 an ounce on a firmer dollar, and bitcoin held near $82,400.
Closing prices
| Asset | Close | Change | Driver |
|---|---|---|---|
| Brent crude | $79.14 / bbl | −2.31% | Soft October housing data in major Western markets weakened demand projections |
| WTI crude | $75.32 / bbl | −2.18% | Fell with global benchmarks; inventory builds added to selling |
| Henry Hub natural gas | $2.84 / MMBtu | +1.43% | Early winter heating forecasts across North America |
| Gold (spot) | $2,684.50 / oz | +0.42% | Safe-haven buying as euro zone fiscal stress deepened |
| Silver (spot) | $31.65 / oz | −0.15% | Industrial drag offset gold’s momentum |
| LME copper | $9,412.00 / t | −1.12% | Manufacturing and tech rotation fears in Asia |
| Chicago wheat | $5.76 / bu | −0.86% | Strong southern hemisphere harvests improved supply |
Africa
Figures as at · Closing levels for 20 October 2026, as reported in this brief
Major African indices
| Index | Close | Change | Driver |
|---|---|---|---|
| South Africa — JSE All Share | 110,399.00 | +1.29% | Financials led ahead of next week’s medium-term budget |
| Nigeria — NGX All-Share | 245,911.13 | +0.26% | Recovered ₦410.86 billion of market value; heavy UBA volume |
| Egypt — EGX 30 | 52,089.00 | +1.90% | Institutional buying; Banque du Caire’s 30% IPO prospectus approved |
| West Africa — BRVM Composite | 524.52 | −0.94% | Portfolio rotation; Sonatel announced a 10-for-1 stock split |
Sovereign yields
- South Africa: The 10-year held at 8.89%, near a one-month low, ahead of the medium-term budget update.
- Nigeria: The 10-year rose to 16.94%, up 19 basis points on the week, after a ₦2.02 trillion primary bond auction at which the Debt Management Office accepted higher long-term stop rates.
- Egypt: The 10-year rose 1 basis point to 23.44%, near record highs.
- West Africa: Regional 10-year BRVM paper held flat at about 7.25%–7.50%.
Currencies
- South African rand: Strengthened 0.20% to R16.4274 per dollar ahead of the Medium-Term Budget Policy Statement.
- Nigerian naira: Edged up to ₦1,333.65 at the official window, with parallel quotes steady at ₦1,365 buying and ₦1,380 selling.
- Egyptian pound: Weakened 0.86% to EGP 54.3750, past the 54 mark, under balance-of-payments pressure.
- CFA franc: Firmed 0.35% to ₣584.20 per dollar, tracking the euro through its peg.
Regional commodities
- South Africa: Gold rose 0.22% to R44,098.50 an ounce as a cautious rand amplified safe-haven buying, while platinum fell 0.65% to $984.20 on industrial and automotive rotation fears in Asia.
- Nigeria: Bonny Light crude slipped 2.24% to $79.85 a barrel, below $80, with global benchmarks. Local cocoa held flat to soft at ₦11.4 million a tonne as the main crop harvest in Ondo and Cross River gathered pace.
- Egypt: 21-carat gold rose 0.96% to EGP 3,685 a gram in Cairo as the pound weakened past 54 to the dollar.
- West Africa: Cocoa held at the official minimum of 1,850 CFA francs a kilo in Abidjan as 2026/2027 main crop arrivals picked up.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for Monday 19 October 2026, as reported in this brief
Kenyan market figures are the 19 October close.
Indices
- NSE 10-Share: Up 0.75% to 2,678.19, led by local buying in top-tier banks and utilities.
- NSE All-Share: Up 0.50% to 240.50 as large caps gained despite mixed breadth.
- NSE 25-Share: Up 0.54% to 6,828.77 on institutional accumulation.
- NSE 20-Share: Up 0.26% to 4,249.24.
A record session
- The block trade: Equity turnover jumped 8,231% to KSh 42.7 billion, about $328.9 million, almost all of it one block of 4.5 billion Kenya Pipeline shares worth KSh 42.5 billion. Local investors accounted for 99.9% of the value traded.
- Blue chips: Britam rose 2.5%, Equity Group 1.3%, Safaricom 0.9% and KCB 0.8%, while KenGen fell 0.9%.
- Foreign flows: Net foreign outflows were about $304,500, continuing this year’s trend of foreign selling.
- Bonds and derivatives: Bond turnover nearly doubled to KSh 12.9 billion, and derivatives open interest held at 25,419 contracts.
Government securities
- Treasury bills: The 91-day bill averaged 8.75% at the 19 October auction and the 182-day 8.86%, the first change in these yields for several briefs. The 364-day held at 9.0352%.
- Bonds: The 10-year was flat at 12.53% in secondary trading. The reopened 30-year FXD1/2026/030 cleared at a weighted average yield of 14.183%.
- Interbank rate: KESONIA, the overnight interbank average, held at 9.26%.
Kenya Forex
Figures as at · Central Bank of Kenya indicative rates, 19 October 2026, as reported in this brief
The dollar gained slightly over the week, with the shilling about 0.5% weaker. Commercial banks bought dollars at KSh 125.00–127.85 and sold at KSh 132.85–133.50, far wider than the official rate.
- Reserves: Gross foreign exchange reserves were reported at $12,194 million, about KSh 1.58 trillion, or 5.3 months of import cover against the statutory four-month minimum. The regional rates section separately reports a $97 million decline that brought reserves to $14.64 billion, with the shilling trading at KSh 129.86 near its monthly lows.
- East African crosses: The shilling hit a record high against the Ugandan shilling at KES/UGX 32.10, up 0.26%, as USD/UGX slid to 3,865 on corporate dollar demand. KES/TZS eased 0.23% to 20.37 after the Bank of Tanzania held its rate at 6.25%, and KES/RWF was flat at 11.24.
CBK indicative mean rates
| Pair | Mean rate | Context |
|---|---|---|
| USD / KES | 129.92 | Shilling about 0.5% weaker on the week |
| GBP / KES | 173.14 | Volatile but within its monthly band |
| EUR / KES | 145.79 | Stable on balanced local demand |
Kenya Policy, Trade and Commodities
Figures as at · As reported in this brief
Announcements from Eldoret
- Tax relief: President Ruto proposed lower income tax for workers earning under KSh 32,333, a stamp duty exemption for land deals of KSh 1 million or less, and the removal of the 25% import tax on mobile phones.
- Market claims: The administration said stock market capitalisation has doubled from KSh 2 trillion to KSh 4.2 trillion. Analysts noted that inflation, at 6.8%, is still testing those gains.
Trade and supply
- Imports from India: Imports from India rose by KSh 135 billion over the six months to August, as Middle East shipping disruption redirected supply routes.
- Milk: The Kenya Dairy Board reported formal milk deliveries down 15.6% between May and August, nearly 14 million litres, causing shortages in shops. The President announced a minimum producer price of KSh 65 a litre, up from KSh 60, plus a KSh 2 quarterly bonus.
Farm and auction prices
- Tea: Mombasa auction prices averaged $3.10 a kilo, about KSh 403, with premium East of Rift teas such as Meru reaching about KSh 670.80 a kilo.
- Coffee: Clean coffee averaged about $396.79 per 50 kg bag at Nairobi Coffee Exchange Sale 2, roughly KSh 1,026 a kilo, with top AA grades reaching $485.00 a bag.
- Maize and onions: Dry maize averaged KSh 4,243.50 per 90 kg bag at warehouse level. Red onions sold for KSh 80 a kilo in Mombasa, KSh 85 at Nairobi’s Wakulima market and up to KSh 160 in Migori.
Kenya Corporate News
Figures as at · As reported in this brief
Ownership changes
- Nedbank and NCBA: Nedbank completed its KSh 110 billion purchase of a 66% controlling stake in NCBA Group. NCBA shares are suspended from 21 October to 2 November for register reconciliation and are due to resume on 3 November. NCBA keeps its NSE listing, brand and local leadership, with 34% in public hands.
- Kenya Pipeline stake sold: State firms and public pension funds, the NSSF among them, sold a combined 24.76% of Kenya Pipeline — 4.5 billion shares for KSh 42.5 billion — to a foreign institutional investor. That is less than eight months after they backstopped the March IPO. The presidency said it shows strong global confidence in Kenya’s markets.
- Sanlam Allianz: The insurer plans to fold its wholly owned life subsidiary into the listed parent, bringing KSh 38.5 billion of assets together to cut costs.
Results and dividends
- Kenya Pipeline: Net profit for the 2026 financial year rose 13.1% to KSh 11.58 billion. The board approved a final dividend of KSh 0.32 a share, in line with its policy of paying out 50% of earnings.
- EABL: The book closed on 19 October for a final dividend of KSh 8.70 a share, payable on 31 October.
Flows and offers
- Foreign outflows: Foreign investors have withdrawn KSh 17.79 billion from the NSE since January, and the selling has erased KSh 134.41 billion in equity value over three weeks.
- Dangote receipts: The NSE extended the deadline for the Dangote Kenya Inward Global Depositary Receipt from 13 October to 27 October, matching the Nigerian timetable.
- Safaricom: Vodacom said it will keep its 55% stake in Safaricom while it appeals the High Court ruling that nullified the state’s KSh 20.4 billion share sale.
Real Estate
Figures as at · As reported in this brief
State housing
- Pioneer, Eldoret: President Ruto handed keys to 2,157 homeowners at the KSh 5.3 billion Pioneer Affordable Housing Project in Eldoret, a gated estate of 15 blocks with 104 shops, a kindergarten and pools.
- Boma Yangu: The State Department for Housing said monthly payments start only once a unit is allocated and occupied. Updated portal prices have raised some apartments by up to KSh 600,000 because building materials cost more.
Rules and tax
- Stamp duty: The proposed exemption for land deals of KSh 1 million or less would save buyers KSh 20,000 to KSh 40,000. The Treasury is to send the bill to Parliament next week, with higher rates for more expensive property.
- Parklands: The Parklands Residents Association issued a notice declaring all Nairobi County development approvals in the area from 15 October void, which halts applications for change of use, subdivision and higher density while compliance is disputed.
- Finance Act 2026: Developers are recalculating costs after the Act removed the 15% corporate tax rate for affordable housing developers and the VAT exemptions on building materials.
Prices
- KNBS index: Standalone houses in Nairobi’s upper market, such as Runda and Karen, rose 3.1% year on year. Middle-income apartments in areas such as Kilimani and Ruaka rose just 0.1% after four quarters of decline caused by oversupply, and land markets are slowing.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.92
As at
Central Bank of Kenya indicative mean rate, as reported in this briefGBP / KES
173.14
As at
Central Bank of Kenya indicative mean rate, as reported in this briefEUR / KES
145.79
As at
Central Bank of Kenya indicative mean rate, as reported in this brief
Equities
NSE All-Share
240.50
+0.50%
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,249.24
+0.26%
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,828.77
+0.54%
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 42.7 billion
KSh 42.5 billion of it was one Kenya Pipeline block trade.
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee decision of 7 October 2026Kenya 10-year bond
12.53%
As at
Secondary market yield, as reported in this brief30-year bond (FXD1/2026/030) auction
14.183%
As at
Weighted average accepted yield, as reported in this brief91-day Treasury bill
8.75%
As at
Central Bank of Kenya auction, as reported in this brief182-day Treasury bill
8.86%
As at
Central Bank of Kenya auction, as reported in this brief364-day Treasury bill
9.0352%
As at
Central Bank of Kenya auction, as reported in this briefKESONIA overnight rate
9.26%
As at
Kenya Shilling Overnight Interbank Average, as reported in this brief
At a glance
- 1Nedbank completed its KSh 110 billion purchase of a 66% stake in NCBA Group. NCBA shares are suspended from 21 October to 2 November while the register is reconciled; the bank keeps its NSE listing, brand and local leadership, with 34% still in public hands.
- 2State firms and pension funds, the NSSF among them, sold a 24.76% stake in Kenya Pipeline — 4.5 billion shares for KSh 42.5 billion — to a foreign institutional investor, less than eight months after backstopping its March IPO.
- 3President Ruto proposed exempting land deals of KSh 1 million or less from stamp duty, cutting income tax for workers earning under KSh 32,333 and scrapping the 25% import tax on mobile phones. In Eldoret, 2,157 families received keys to the Pioneer affordable housing estate.
Sources
- Serrari Group desk compilation, 21 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data