
19 October 2026
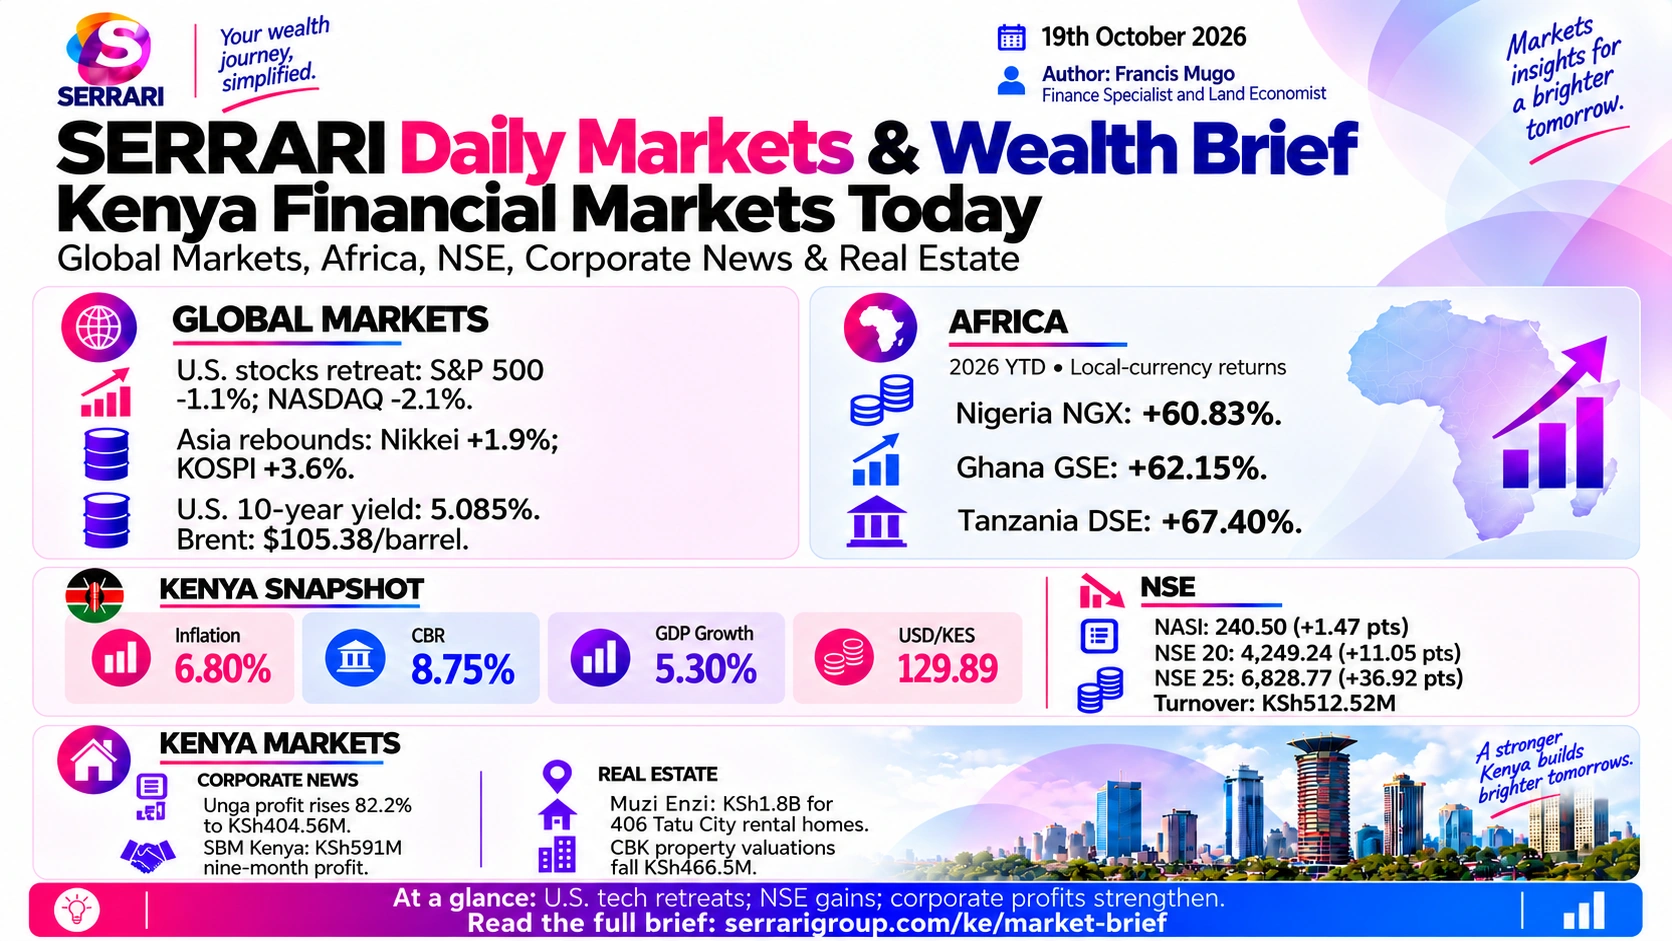
US technology shares retreat while Asian markets rebound and the NSE All-Share advances to 240.50. Unga and SBM Kenya report stronger profits as Tatu City adds a KSh 1.8 billion rental housing project.

Global Markets
Figures as at · Serrari Group desk compilation supplied for 19 October 2026; session data for 16 October 2026
United States
- S&P 500: Closed at 7,659.44, down 84.62 points or 1.1%; down 1.9% for the week.
- Nasdaq Composite: Closed at 26,140.03, down 572.99 points or 2.1%; down 4.5% for the week.
- Dow Jones: Closed at 52,002.41, down 175.28 points or 0.3%; up 0.7% for the week.
- Russell 2000: Closed at 2,721.37, down 45.90 points or 1.7%; down 3.0% for the week.
- Technology: Scrutiny of AI infrastructure financing weighed on semiconductor shares: Micron lost 5.6% and Intel 5.8%.
Europe and Asia
- Europe: The STOXX 600 added 0.72% on Friday. London’s FTSE 100 gained 0.38% on the day and 3.1% for the week.
- Japan and South Korea: The Nikkei 225 rebounded 1.9% to 65,658.59 and the Kospi jumped 3.6%, with Samsung Electronics up 4.2% and SK Hynix up 3.5%.
- Indonesia: Equities plunged after MSCI announced plans to remove Indonesia from its emerging-market indexes, according to the submission.
Bonds and currencies
- Sovereign yields: Developed-market yields stabilised or edged higher on Friday but ended the volatile week materially lower as investors rotated away from AI investments. The brief reports expectations of a Federal Reserve hold at the 28 October meeting.
- US Treasury curve: The 2-year yield was 4.715%, the 10-year 5.085% and the 30-year 5.434%, with the 10Y–2Y spread at +0.35 percentage points. The 10-year fell nearly 14 basis points over the week.
- European bonds: The UK 10-year yield stood at 5.369% and Germany’s at 3.421%, after a five-week intraday low of 3.352% on Thursday.
- Major currency pairs: EUR/USD closed at 1.1253, up 0.4%; GBP/USD at 1.3324, up 0.41%–0.51%; USD/JPY at 157.99, down 0.02%; and AUD/USD at 0.6919, stabilising above support at 0.6910.
Commodities
Figures as at · Serrari Group desk compilation supplied for 19 October 2026; session data for 16 October 2026
Energy
- Oil: Brent settled at $105.38 a barrel, down $0.54 on the day but higher over the week. WTI fell 2.20% to $95.39 despite a reported 8.56 million-barrel drop in US inventories.
- Natural gas: The November contract traded around $3.24/MMBtu, supported by a 67 Bcf storage injection against expectations of 75 Bcf.
Metals
- Precious metals: Gold closed at $4,182.06 an ounce, up 0.27%, and silver at $57.80, up 0.74%.
- Industrial metals: Aluminium rose 1.41% to $3,015.10 a tonne. Iron ore rebounded within its range as Chinese spot import margins reached 6.01 yuan/mt and mills maintained needs-based purchases.
Agriculture
- Grains: Wheat fell 1.42% to 660.50 cents a bushel on seasonal US harvest pressure. Soybeans and corn also declined, with soybeans finishing at $1,261.25 as quoted in the submission.
- Soft commodities: Cocoa fell 3.19% to $5,645 a tonne as high port arrivals competed with an expected 17% Ivory Coast crop deficit linked to El Niño. Coffee rose 4.85% intraday on tighter export projections.
African Markets
Figures as at · Serrari Group desk compilation supplied for 19 October 2026; session data for 16 October 2026
| Market | Benchmark | Close | 2026 YTD, local currency |
|---|---|---|---|
| Nigeria | NGX All-Share | 247,707.13 | +60.83% |
| South Africa | JSE All Share | 108,378.40 | −6.44% |
| Egypt | EGX 30 | 53,298.14 | +27.42% |
| Ghana | GSE Composite | 14,221.20 | +62.15% |
| WAEMU | BRVM Composite | 547.91 | +58.47% |
| Tanzania | DSE All Share | 4,623.56 | +67.40% |
| Morocco | MASI | 16,892.55 | −10.37% |
Government bonds
- South Africa and Kenya: South Africa’s 10-year yielded about 8.855%–8.86% and its 30-year 9.175%. Kenya’s 10-, 15- and 20-year yields were 12.53%, 13.00% and 13.50%.
- Regional yields: Nigeria’s 2–30-year range was 14.56%–16.09%, with the 10-year quoted around 15.4%–16.2%; Uganda’s 3-month–10-year range was 9.94%–15.41%; Zambia’s 2–15-year range was 9.19%–15.75%.
- Other sovereigns: Mauritius: 4.10%–5.89%, with the 10-year around 5.51%; Morocco: 2.26%–3.92%; Namibia: 7.08%–11.75%, with the 10-year around 8.87%. Senegal’s stressed 5-year/Eurobond yields exceeded 20.8%.
Currencies
- Rates per US dollar: The rand traded at 16.52, the naira at 1,330.13, Ghana’s cedi at 11.66 and Zimbabwe Gold at 26.60. The brief highlights weaker South African manufacturing, regional inflation pressures in Nigeria, debate over Ghana’s forex handling and Zimbabwean liquidity distortions.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation supplied for 19 October 2026; session data for 16 October 2026
- Market capitalisation: Added KSh 24.71 billion to reach KSh 4,036.11 billion.
- Trading activity: Equity turnover rose KSh 117.74 million to KSh 512,515,489.19, with 10,303,130 shares traded across 9,976 deals.
- Leading stocks: The submission highlights KCB Group, Safaricom, Diamond Trust Bank Kenya and I&M Holdings as drivers of the gains.
| Index | Close | Point change |
|---|---|---|
| NSE All-Share (NASI) | 240.50 | +1.47 |
| NSE 20-Share | 4,249.24 | +11.05 |
| NSE 25-Share | 6,828.77 | +36.92 |
| NSE 10-Share | 2,678.19 | +20.06 |
| Banking Sector Index | 282.87 | +1.57 |
Kenya Government Securities
Figures as at · Serrari Group desk compilation supplied for 19 October 2026; session data for 16 October 2026
- Policy rate: The Central Bank Rate remained at 8.75%.
- Treasury bills: The 91-day rate eased to 8.750%, the 182-day to 8.860%, and the 364-day rose marginally to 9.038%.
- Liquidity: A recent reopened 30-year bond auction attracted a performance rate of 167.7%.
| Maturity | Yield |
|---|---|
| 2 years | 9.210% |
| 5 years | 9.320% |
| 7 years | 11.150% |
| 10 years | 12.530% |
| 20 years | 13.500% |
| 25 years | 13.500% |
Kenya Forex
Figures as at · Serrari Group desk compilation supplied for 19 October 2026; session data for 16 October 2026
- Regional EAC crosses: One Kenyan shilling bought 20.3600 Tanzanian shillings, 31.1700 Ugandan shillings, 23.0600 Burundian francs and 11.3500 Rwandan francs.
| Currency | KES per quoted unit |
|---|---|
| US dollar | 129.8900 |
| Pound sterling | 172.7400 |
| Euro | 145.8100 |
| South African rand | 7.8900 |
| Chinese yuan | 19.4100 |
| UAE dirham | 35.3600 |
| Canadian dollar | 91.5900 |
| Japanese yen (100) | 82.2700 |
Kenya Corporate News
Figures as at · Serrari Group desk compilation supplied for 19 October 2026; session data for 16 October 2026
Listings and restructuring
- Quickmart: Sterling Capital valued the shares at KSh 6.96 ahead of the proposed NSE listing, 7.2% below the KSh 7.50 IPO issue price, according to the brief.
- Sanlam Allianz Kenya: The group announced plans to dissolve its wholly owned life insurance subsidiary, with KSh 38.47 billion in assets, and absorb its portfolio and liabilities into the listed parent.
- Standard Group: The High Court cleared insolvency proceedings over KSh 7.54 million in unpaid employee dues. CEO Chaacha Mwita resigned effective 1 November 2026 after seven months; the firm appointed three independent non-executive directors.
- Equity Group: Victoria Cherotich was appointed Group Company Secretary following CBK approval.
Earnings and investment
- Unga Group: Net profit rose 82.2% to KSh 404.56 million for the year ended 30 June 2026, supported by sales volumes and lower financing costs.
- Kenya Pipeline Company: The brief reports a 13% rise in net profit to KSh 11.58 billion and revenue of KSh 43 billion in its first annual results as a listed company.
- SBM Bank Kenya: Nine-month net profit reached KSh 591 million, with top-line income up 33%.
- SOFY Unicharm: Unicharm and Toyota Tsusho launched a KSh 2 billion Kenyan venture to manufacture personal hygiene products locally.
Regulation and legal updates
- Tax legislation: The submission reports that the Tax Laws Amendment Act 2026 extends the concessionary 8% fuel VAT rate by 90 days and changes excise duties on tiles, sanitary ware and glass.
- Safaricom stake: The Court of Appeal expedited proceedings over Vodacom’s proposed $1.9 billion acquisition of a 15% state-backed Safaricom stake and froze the asset and transaction proceeds pending the appeal, according to the brief.
- Investment schemes: The CMA appealed for evidence concerning QVSE and Global Investment Group schemes alleged to have defrauded investors through purported US equity trading accounts.
Kenya Real Estate
Figures as at · Serrari Group desk compilation supplied for 19 October 2026; session data for 16 October 2026
Market growth
- Sector activity: Real estate grew 5.0% in 2026 versus 4.6% in the previous year and represented roughly 10% of GDP, according to the submission. Construction output rose 6.6%, while cement consumption increased nearly 18%.
- Housing and rents: Rents rose 1.4% in Nairobi suburbs and 1.1% in satellite towns. Average suburban rent exceeded KSh 200,000 a month amid an estimated national deficit of around 2 million housing units.
Projects and investment
- Muzi Enzi, Tatu City: International Housing Solutions broke ground on a KSh 1.8 billion development of 406 one- and two-bedroom rental apartments, targeting initial occupancy in 2028.
- Lamu refinery: The brief reports groundbreaking for a $16 billion, approximately KSh 2 trillion, refinery led by Aliko Dangote and President William Ruto, with capacity of 700,000 barrels a day and completion around 2030.
- Data centres: Digital infrastructure attracted 24% of wealthy Kenyan investors, according to the submission, while Raxio secured over KSh 49.4 billion in committed capital for pan-African expansion.
Institutional property
- CBK valuations: Investment property valuations fell by KSh 466.5 million following an audit.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.89
As at
As reported in the Serrari brief supplied for 19 October 2026GBP / KES
172.74
As at
As reported in the Serrari brief supplied for 19 October 2026EUR / KES
145.81
As at
As reported in the Serrari brief supplied for 19 October 2026
Equities
NSE All-Share
240.50
As at
As reported in the Serrari brief supplied for 19 October 2026NSE 20-Share
4,249.24
As at
As reported in the Serrari brief supplied for 19 October 2026NSE 25-Share
6,828.77
As at
As reported in the Serrari brief supplied for 19 October 2026
Rates
Central Bank Rate
8.75%
As at
As reported in the Serrari brief supplied for 19 October 2026Kenya 10-year bond
12.53%
As at
As reported in the Serrari brief supplied for 19 October 202691-day Treasury bill
8.750%
As at
As reported in the Serrari brief supplied for 19 October 2026182-day Treasury bill
8.860%
As at
As reported in the Serrari brief supplied for 19 October 2026364-day Treasury bill
9.038%
As at
As reported in the Serrari brief supplied for 19 October 2026
At a glance
- 1US technology weakness pulled the Nasdaq down 2.1%, while the Nikkei and Kospi rebounded 1.9% and 3.6% respectively.
- 2The NSE All-Share rose 1.47 points to 240.50, with equity turnover reaching KSh 512.52 million.
- 3Unga’s profit rose 82.2% to KSh 404.56 million; Muzi Enzi adds 406 rental homes at Tatu City in a KSh 1.8 billion development.
Sources
- Serrari Group desk compilation supplied for 19 October 2026; PDF headed Markets Snapshot – 16 October 2026
- Serrari Group supporting artwork, 19 October 2026
- Serrari published Africa macro data