
16 October 2026
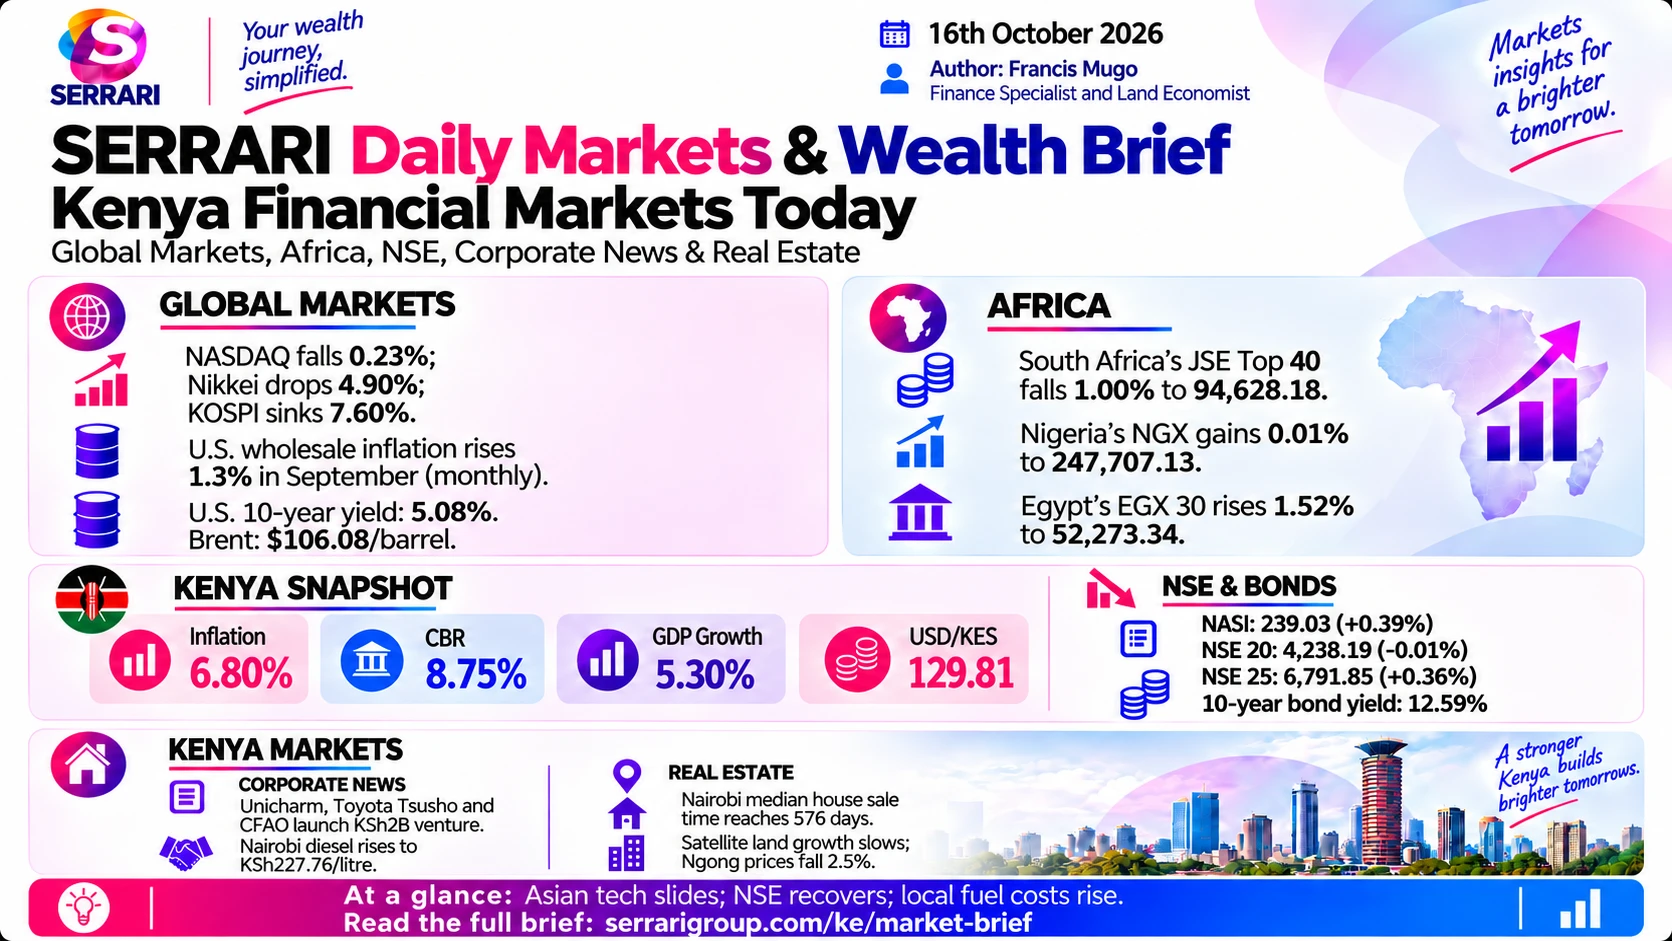
Asian tech collapsed, with the Kospi sinking 7.6% through circuit breakers and the Nikkei 4.9%, while US wholesale inflation of 1.3% month on month kept rate fears alive. Nairobi steadied, the NASI up 0.39% to 239.03, as EPRA lifted Nairobi diesel to KSh 227.76 a litre.

Global Markets
Figures as at · Closing levels for Thursday 15 October 2026, as reported in this brief
A tech rout tore through Asia, triggering circuit breakers in Seoul, while Wall Street split: money rotated into value shares and the Dow gained 533 points even as the Nasdaq extended its weekly losses. September producer prices then added to the inflation scare.
Major indices
| Index | Close | Change | Catalyst |
|---|---|---|---|
| Dow Jones Industrial Average | 52,154.48 | +1.07% | Up 533 points on a flight-to-safety rotation into value shares |
| S&P 500 | 7,713.88 | −0.07% | Healthcare and staples gains offset the technology rout |
| Nasdaq Composite | 26,631.54 | −0.23% | Extended weekly losses on heavy liquidations in AI server infrastructure |
| Nikkei 225 | 64,424.82 | −4.90% | A historic points drop on a massive tech sell-off |
| KOSPI | 2,410.22 | −7.60% | Circuit breakers triggered as tech giants collapsed more than 9% |
| Euro Stoxx 50 | 6,136.21 | −0.83% | Followed Asia lower as regional tech faced heavy selling |
| FTSE 100 | 10,692.60 | −0.07% | Cushioned by energy and defensive healthcare weights |
US wholesale inflation
- Producer prices: The Bureau of Labor Statistics reported September PPI up 1.3% on the month, the largest single-month rise since March 2022 and more than double the 0.6% consensus.
Forex
- Dollar index: Eased 0.55% to 102.30 from multi-month peaks as cooling Treasury yields slowed dollar buying.
- EUR/USD: Recovered 0.40% to 1.1165 from a 16-month low on a technical support bid.
- GBP/USD: Up 0.38% to 1.3245, clawing back ground in the late New York session as the dollar pulled back.
- USD/JPY: Slid 0.31% to 157.95, below 158, as the Nikkei’s 4.9% plunge sparked safe-haven yen repatriation.
- USD/CHF: Slightly lower at 0.8310 as the franc drew defensive capital.
Global Yields
Figures as at · Yields for 15 October 2026, as reported in this brief
Bonds rallied on the tech panic as money fled equities for safety.
Benchmark yields
| Benchmark | Yield | Change | Context |
|---|---|---|---|
| US 10-year Treasury | 5.080% | −0.109 pp | Eased from multi-decade highs on heavy safe-haven buying |
| US 2-year Treasury | 4.760% | −0.031 pp | Retreated, though 2026 hike odds stayed near 39% |
| Germany 10-year Bund | 2.87% | −0.070 pp | Tracked the global bond rally as European tech sold off |
| UK 10-year gilt | 4.38% | −0.070 pp | Pulled back with eurozone peers despite energy price concerns |
| Japan 10-year JGB | 0.96% | −0.020 pp | Slid amid heavy regional equity distress |
Commodities
Figures as at · Closing prices for 15 October 2026, as reported in this brief
Closing prices
| Contract | Close | Change | Driver |
|---|---|---|---|
| Brent crude | $106.08 / bbl | Flat | Held multi-month highs on Middle East shipping risk |
| WTI crude | $98.05 / bbl | +3.11% | A new high after a steep drawdown in US inventories |
| Gold, December | $4,141.50 / oz | +0.82% | Up $33.60 as cooling Treasury yields revived the bullion bid |
| Silver, December | $56.95 / oz | +1.97% | Pared part of Wednesday’s deep institutional liquidation |
| COMEX copper | $6.71 / lb | +0.60% | Rose as the dollar softened, despite weak factory demand |
| Chicago wheat | $6.76 / bu | +0.45% | Crept up on Black Sea logistics friction |
Africa
Figures as at · Closing levels for 15 October 2026, as reported in this brief
Major African indices
| Index | Close | Change | Driver |
|---|---|---|---|
| South Africa — JSE Top 40 | 94,628.18 | −1.00% | Global AI data-centre valuation strain and medium-term budget nerves |
| Nigeria — NGX All-Share | 247,707.13 | +0.01% | A second day of gains, cushioned by oil-hedged Oando and Aradel |
| Egypt — EGX 30 | 52,273.34 | +1.52% | EGP 7.0 billion turnover driven entirely by local net buyers |
Sovereign yields
- South Africa: The 10-year held flat at 8.91% and the 30-year at 9.24% as investors awaited next week’s medium-term budget policy statement.
- Nigeria: The 91-day bill was stable at 15.50%, a true yield of 16.14%, and the 364-day at 15.89%, a true yield of 18.89%, after a heavily oversubscribed auction.
- Egypt: The 10-year was unchanged at 23.34%, on a curve still inverted by 209 basis points.
Currencies
- South African rand: Down 0.06% at R16.63, consolidating after recent declines, with crosses at R18.42 per euro and R21.84 per pound.
- Nigerian naira: The official window held at ₦1,356.74 on strong oil buffers, with parallel rates at ₦1,410–₦1,430.
- Egyptian pound: Flat at EGP 52.28 under strict capital controls.
- Zimbabwe gold: Steady at ZWG 26.60, holding its peg at 0.619 ZWG per rand.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 15 October 2026, as reported in this brief
Indices
- NSE All-Share: Up 0.93 points, or 0.39%, to 239.03 after the previous day’s heavy large-cap selling.
- NSE 20-Share: Down 0.61 points, or 0.01%, to 4,238.19 on small moves in some blue chips.
- NSE 25-Share: Up 24.52 points, or 0.36%, to 6,791.85, led by local banks.
- NSE 10-Share: Up 13.07 points, or 0.49%, to 2,658.13, leading the recovery.
- Banking sector index: Up 1.48 points, or 0.53%, to 281.30 on strong domestic interest despite foreign selling.
The session
- Volume and value: Safaricom led on volume with 6.6 million shares, while KCB Group led on value with KSh 301 million of turnover as foreign investors sold.
- Market capitalisation: Rose KSh 15.51 billion to KSh 4,011.40 billion, recovering part of what the inflation shock had wiped off.
- Absa index: Absa’s 2026 Africa Financial Markets Index moved Kenya up to 5th in Africa, citing new dollar-denominated assets and greater capital flexibility.
- Gainers: Sameer Africa topped the board, followed by TPS Eastern Africa up 6.1%, Sasini and Umeme.
- Losers: Unga Group was the top loser on input costs, with Longhorn Publishers down 8.7%, Uchumi Supermarket and Nation Media Group.
Government securities
- 10-year benchmark: Rose 8 basis points to 12.590% as international debt repriced.
- 15-year bond: Steady at 12.970%, supported by the CBK’s recent switch-auction reopenings.
- Treasury bills: The 91-day held at 8.7615% in line with the Central Bank Rate, the 182-day at 8.8744% and the 364-day at 9.0352%.
Kenya Forex
Figures as at · Central Bank of Kenya official mean rates, 15 October 2026, as reported in this brief
The shilling eased slightly against a strong dollar while gaining on sterling and the euro, both of which weakened globally.
- East African crosses: One Kenyan shilling buys 21.57 Tanzanian shillings, 28.94 Ugandan shillings, 10.63 Rwandan francs and 22.56 Burundian francs, the same matrix as the previous brief to every decimal.
Official CBK mean rates
| Pair | Mean rate | Move vs KES | Context |
|---|---|---|---|
| USD / KES | 129.81 | −0.02% | Slipped from 129.79 on strong global dollar demand |
| GBP / KES | 171.30 | Shilling stronger | Sterling softened against the dollar |
| EUR / KES | 144.43 | Shilling stronger | The euro retreated broadly |
Kenya Corporate News
Figures as at · As reported in this brief
Fuel prices
- EPRA raises prices: From 15 October, EPRA raised maximum retail prices, citing import costs from the Middle East shipping crisis: super petrol up 6% and diesel up 4.5%. Nairobi diesel rose to KSh 227.76 a litre from KSh 217.86, and kerosene to KSh 219.87. The state extended the 8% VAT rate on fuel to January 2027 to soften the rise.
Industry and insurance
- Sofy Unicharm East Africa: Unicharm Corporation, Toyota Tsusho and CFAO Kenya launched a Sh2 billion joint venture to make and distribute sanitary products locally. Investment and Trade CS Lee Kinyanjui called it a major boost to local industry.
- Kenya Re and the IRA: Kenya Re and the Insurance Regulatory Authority are in a public dispute over a Sh3.3 billion stake in the liquidated ARM Cement. Half-year regulatory filings to June showed Kenya Re buying more shares; the reinsurer denies the trades. Filings also show insurers’ holdings in NSE-listed firms rose from Sh1.35 billion to Sh6.32 billion.
Credit and technology
- Borrowing appetite falls: TransUnion’s Consumer Pulse Study found the share of Kenyans planning to take new credit or refinance fell to 57% from 69% a year earlier, as households put tight budgets ahead of new debt.
- In-house AI: Analysis of 1,300 African entries to the 2026 CIO100 Awards in Nairobi found firms such as Sarova Hotels and Car & General replacing off-the-shelf software with in-house AI tools, and hiring specialist engineers to build them.
Real Estate
Figures as at · As reported in this brief
A slower market
- 576 days to sell: Kenya Property Centre data puts the median time to complete a house sale in Nairobi at 576 days. Buyers are taking their time and favouring homes near amenities and upgraded roads such as Thika Road and the Nairobi Expressway.
- Satellite towns soften: HassConsult data shows land in Nairobi’s outer ring rising just 1.4% over the last two quarters. Ngong fell 2.5%, and Limuru, Kiambu and Syokimau also dipped as high utility and fuel costs squeeze middle-income buyers.
Tax and compliance
- eRITS enforcement: The Kenya Revenue Authority has moved from encouragement to strict enforcement of electronic tracking of rental property under the draft residential rental income tax regulations.
- The 30% rate: Developers building more than 100 homes a year have lost the 15% preferential corporate tax rate and now pay the standard 30%.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.81
As at
Central Bank of Kenya official mean rate, as reported in this briefGBP / KES
171.30
As at
Central Bank of Kenya official mean rate, as reported in this briefEUR / KES
144.43
As at
Central Bank of Kenya official mean rate, as reported in this brief
Equities
NSE All-Share
239.03
+0.39%, up 0.93 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,238.19
−0.01%, down 0.61 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,791.85
+0.36%, up 24.52 points
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KSh 4.011 trillion
Up KSh 15.51 billion on the session.
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.59%
Up 8 basis points.
As at
As reported in this briefKenya 15-year bond
12.97%
As at
As reported in this brief91-day Treasury bill
8.7615%
As at
Central Bank of Kenya auction, as reported in this brief182-day Treasury bill
8.8744%
As at
Central Bank of Kenya auction, as reported in this brief364-day Treasury bill
9.0352%
As at
Central Bank of Kenya auction, as reported in this brief
At a glance
- 1EPRA raised maximum fuel prices from 15 October, with super petrol up 6% and diesel up 4.5%. Nairobi diesel is now KSh 227.76 a litre, up from KSh 217.86, and kerosene KSh 219.87. The state extended the 8% VAT rate on fuel to January 2027.
- 2Unicharm, Toyota Tsusho and CFAO Kenya launched a Sh2 billion joint venture, Sofy Unicharm East Africa, to make and distribute sanitary products locally and secure the regional supply chain.
- 3Selling a house in Nairobi now takes a median 576 days, according to the Kenya Property Centre. Buyers are taking their time and favouring homes near upgraded roads such as Thika Road and the Nairobi Expressway.
Sources
- Serrari Group desk compilation, 16 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data