
15 October 2026
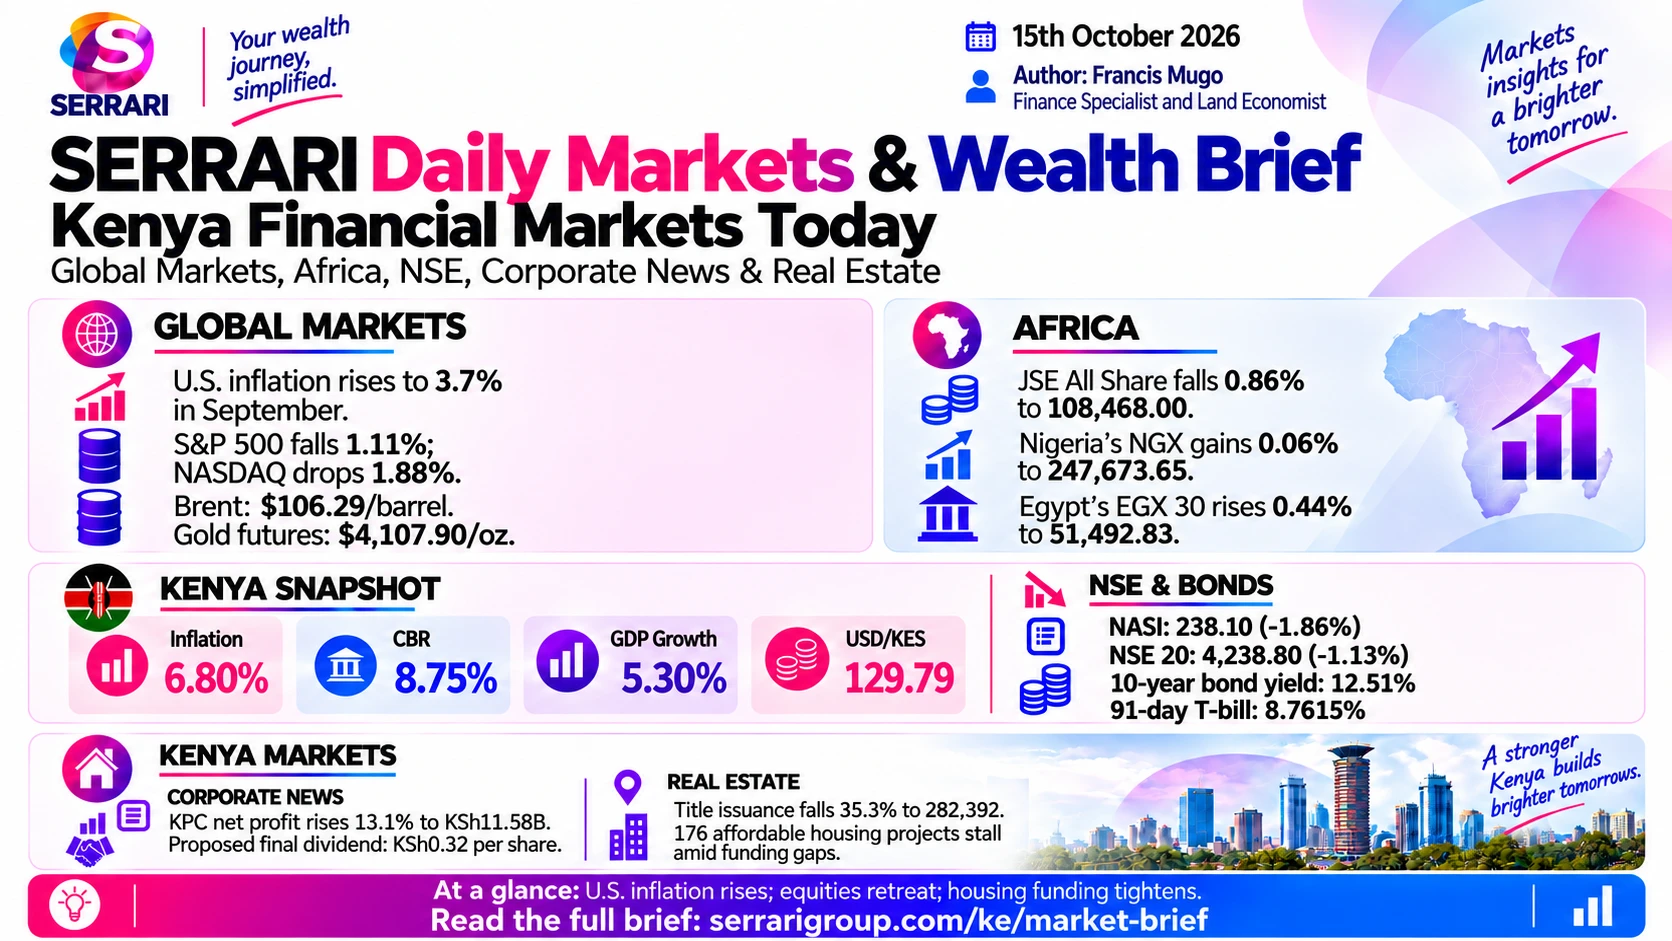
A hot US inflation print of 3.7% shattered easing hopes and handed the S&P 500 its worst session since July, with the Nasdaq down 1.88% and silver crashing 6.32%. Nairobi followed, the NASI falling 1.86% to 238.10 as Safaricom and KCB between them took 80.5% of the day’s turnover.

Global Markets
Figures as at · Closing levels for Wednesday 14 October 2026, as reported in this brief
September CPI came in at 3.7% year on year, above consensus, and hopes of an easing cycle evaporated. Traders repriced the probability of another Federal Reserve hike before the end of 2026 to about 39%, and the selling concentrated in the most richly valued artificial intelligence and semiconductor names.
Major indices
| Index | Close | Change | Catalyst |
|---|---|---|---|
| S&P 500 | 7,718.94 | −1.11% | Hot CPI sparked its worst session since July |
| Nasdaq Composite | 26,692.87 | −1.88% | Hammered by an aggressive sell-off in AI and semiconductor shares |
| Dow Jones Industrial Average | 51,621.48 | −0.09% | Buffered by defensives, health care and staples |
| Euro Stoxx 50 | 6,187.55 | +0.33% | Edged higher during its own hours, before the US slide |
| FTSE 100 | 10,700.08 | +0.47% | Lifted by lower budget borrowing expectations and defence stocks |
| Nikkei 225 | 67,744.29 | −0.05% | Closed virtually flat ahead of the late-day global tech rout |
Forex
- Dollar index: Rallied 0.57% to 102.75, marching to an 18-month high of 102.87 on widening trans-Atlantic yield spreads and safe-haven demand.
- EUR/USD: Dropped 0.70% to 1.1120, a 16-month low.
- GBP/USD: Fell 0.45% to 1.3195, wiping out morning gains that had briefly peaked at 1.3274.
- USD/JPY: Rose 0.30% to 158.45 as the Bank of Japan–Federal Reserve divergence story reignited.
- USD/CHF: Slightly higher at 0.8340, bid both on high US yields and defensive demand.
What the session turned on
- Yields: The US 10-year surged past 5.32% intraday before settling at 5.189% as capital rotated into fixed income after the late stock slide. At the IMF-World Bank annual meetings in Bangkok, economists warned that structural debt-to-GDP is threatening to reach 100% globally, amplified by multi-decade high borrowing costs.
- Energy: Escalating maritime hostilities and direct threats to vessels transiting the Strait of Hormuz injected a severe risk premium into crude. The surge cushioned energy equities but sharpened fears of a stagflationary energy loop.
- Metals: With bullion bearing a high opportunity cost against a 5.2% risk-free Treasury rate, gold fell $69.40 an ounce. Silver’s industrial and monetary safety bids cracked together, and it crashed 6.32% in heavy institutional liquidation.
Global Yields
Figures as at · Yields for 14 October 2026, as reported in this brief
The US levels follow on from the previous session. The German, British and Japanese levels in this brief sit well away from where the same benchmarks were quoted in the 13 and 14 October briefs, so read them as this submission reports them rather than as a continuation of that series.
Benchmark 10-year yields
| Benchmark | Yield | Change | Context |
|---|---|---|---|
| US 10-year Treasury | 5.189% | −0.027 pp | Spiked above 5.32% intraday after the CPI print before cooling |
| US 2-year Treasury | 4.791% | Unchanged | Sticky as short-term hike odds climbed to about 39% |
| Germany 10-year Bund | 2.94% | Slightly lower | Fell in morning trade before tracking volatile late US moves |
| UK 10-year gilt | 4.45% | Slightly lower | Retreated with European peers ahead of the US inflation print |
| Japan 10-year JGB | 0.98% | Unchanged | Reported as hovering near multi-decade highs under domestic fiscal scrutiny |
Commodities
Figures as at · Closing prices for 14 October 2026, as reported in this brief
Closing prices
| Contract | Close | Change | Driver |
|---|---|---|---|
| Brent crude | $106.29 / bbl | +0.57% | Near multi-month highs on structural supply disruption fears |
| WTI crude | $95.09 / bbl | +1.01% | A three-week high as US oil majors touched record levels |
| Gold, December | $4,107.90 / oz | −1.66% | Down $69.40 after the hot inflation reading |
| Silver, December | $55.85 / oz | −6.32% | A massive liquidation wave as industrial and monetary bids faded |
| COMEX copper | $6.67 / lb | −0.80% | Rebounded from session lows after a strike was averted at Escondida |
| Chicago wheat | $6.73 / bu | +0.60% | Edged up on tightening Black Sea logistics |
Africa
Figures as at · Closing levels for 14 October 2026, as reported in this brief
Major African indices
| Index | Close | Change | Driver |
|---|---|---|---|
| South Africa — JSE All Share | 108,468.00 | −0.86% | Dragged by global risk-off sentiment and sovereign debt tracking |
| Nigeria — NGX All-Share | 247,673.65 | +0.06% | Snapped a two-day losing streak on domestic oil and banking bids |
| Egypt — EGX 30 | 51,492.83 | +0.44% | Local buyers heavily offset global institutional selling |
Sovereign yields
- South Africa: The 10-year benchmark eased 1 basis point to 8.91% as safe-haven buying offset a slipping rand, while the 30-year crept up 1 basis point to 9.24% on long-duration fiscal scrutiny.
- Nigeria: The 91-day bill stopped at 15.50%, a true yield of 16.14% and down 80 basis points after the policy rate cut to 23.00%. The 182-day stopped at 15.80%, a true yield of 17.16%, and the 364-day at 15.89%, a true yield of 18.89%, oversubscribed by more than ten times the offer.
- Egypt: The 10-year edged 3 basis points lower to 23.34%, on a curve inverted by 209 basis points.
Currencies
- South African rand: Slid 0.80% to R16.62 after the US inflation print, with crosses closing at R18.46 per euro and R21.85 per pound.
- Nigerian naira: The official window held firm at ₦1,356.74, supported by $50 billion in external reserves and lower fuel import demand. Parallel rates sat at ₦1,410–₦1,430.
- Egyptian pound: Flat at EGP 52.28, range-bound and insulated by stringent capital management.
- Zimbabwe gold: Steady at ZWG 26.60, with the Reserve Bank holding a local peg to the rand at 0.619 ZWG.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 14 October 2026, as reported in this brief
Indices
- NSE All-Share: Fell 1.86% to 238.10, battered by valuation losses in top-tier banks and telecom. It remains up 25.32% for the year.
- NSE 20-Share: Fell 1.13% to 4,238.80 on heavy volume liquidations, still up 15.50% for the year.
- NSE 25-Share: Reported down 1.55% at 4,891.24, up 21.20% for the year. That level does not follow from the 6,900.83 this series published for the previous session, so it is given here as the brief states it rather than treated as settled.
- NSE 10-Share: Reported down 1.74% at 2,155.45, up 26.15% for the year. The same mismatch applies against the previous session’s 2,742.79.
Who was trading
- Concentration: Safaricom and KCB Group dominated the day’s liquidations, together accounting for 80.5% of the session’s entire equity turnover.
- The valuation hit: Market capitalisation is reported down KSh 41.5 billion in a single session to KSh 2.19 trillion, from KSh 2.23 trillion. That is a different order of magnitude from the KSh 4.110 trillion this series carried on 12 October.
- The domestic cushion: Foreign investors were net sellers, but local participation accounted for 59.3% of all buying activity — a structural safety net under the market.
Government securities
- 10-year benchmark: Eased 0.08 percentage points to 12.510% in volatile secondary trading.
- 25-year infrastructure bond: At 13.580%. The brief describes this as a 338 basis point spread between short and long durations; against the 10-year the gap is 107 basis points and against the 91-day bill it is 482.
- Treasury bills: The 91-day at 8.7615% on steady demand anchored by the rate hold, the 182-day range-bound at 8.8744%, and the 364-day stable at 9.0352%, heavily used by domestic institutions locking in yields.
Kenya Forex
Figures as at · Central Bank of Kenya rates, 14 October 2026, as reported in this brief
The shilling held inside its 129–130 band while sterling and the euro both lost ground globally, so the Kenyan crosses against them strengthened.
- East African crosses: One Kenyan shilling buys 21.57 Tanzanian shillings, 28.94 Ugandan shillings, 10.63 Rwandan francs and 22.56 Burundian francs. The brief’s full matrix is internally consistent this time: 1,000 Ugandan shillings at KSh 34.55 works back to exactly the 28.94 quoted.
Official CBK rates
| Pair | Buying | Selling | Mean |
|---|---|---|---|
| USD / KES | 129.29 | 130.29 | 129.79 |
| GBP / KES | 171.26 | 172.58 | 171.92 |
| EUR / KES | 144.73 | 145.85 | 145.29 |
Kenya Corporate News
Figures as at · As reported in this brief
Kenya Pipeline’s first results since listing
- Profit and revenue: In its first major investor briefing since debuting on the NSE in March, Kenya Pipeline reported net profit up 13.1% to KSh 11.58 billion for the year ending June 2026, with total revenue above KSh 42.98 billion on strong local and transit petroleum volumes.
- Dividend: The board proposed a final payout of KSh 5.81 billion, or KSh 0.32 per share, with book closure set for 30 November 2026.
Safaricom, banking and tech
- The stake sale: The Court of Appeal declined to suspend the High Court ruling that nullified the KSh 204.3 billion, or $1.9 billion, sale of a 15% state stake to Vodacom. The state now faces unwinding a completed transaction that was intended to fund development through the National Infrastructure Fund. Separately, Safaricom hosted its Cybersecurity Summit 2026, focused on using AI to strengthen enterprise defences.
- KCB: The bank issued a final notice ahead of discontinuing its old mobile banking application on Thursday 15 October, requiring customers to move to the newer app to avoid disruption.
- Microsoft: The Nairobi engineering hub at the Africa Development Centre faces potential closure. Following notices to employees, the government is engaging the company to protect local engineering jobs and anchor regional talent.
Where pension money goes
- State debt over corporates: The SanlamAllianz Retirement Benchmark Report Kenya found scheme managers still favour government paper: state securities absorb 46.6% of all pension assets against just 14.4% allocated to quoted equities on the NSE.
Real Estate
Figures as at · As reported in this brief
Titles and funding
- Title issuance falls: The State Department for Lands and Physical Planning reported title deed issuance down 35.3%, with 282,392 titles issued in the year to June 2026 against 436,212 the year before — the first contraction in five years. Analysts attribute it to shrinking bank lending to construction and buyers deferring purchases against an average lending rate near 14.34%.
- Housing projects stall: A Parliamentary Budget Office report found 176 projects, 15% of the affordable housing pipeline, have stalled because funding lags contractor obligations.
- The rent-to-own trap: The Affordable Housing Board collected KSh 212.3 million from completed units against a KSh 15.3 billion target — 1.4% of projected cash flow — because low-income buyers favour slow rent-to-own plans over outright purchase.
Prices and tax
- Satellite towns soften: HassConsult data shows land prices in Nairobi’s outer rings slowing to 1.4% annual growth, breaking nearly two decades of double-digit performance. Ngong fell 2.5%, with Limuru, Kiambu and Syokimau also correcting. Thika Road pockets — Ruiru, Thika and Ruaka — kept gaining, insulated by corporate hubs and improved bypasses.
- Corporation tax doubles: Finance Act changes removed the preferential 15% bracket for developers building at least 100 residential units a year, resetting them to the standard 30%. With VAT exemptions on heavy construction inputs also gone, costs are rising and builders are passing the premium into off-plan valuations.
- What the wealthy do: Knight Frank’s Wealth & Investment Trends Report found Kenya’s ultra-high-net-worth individuals typically own three residential properties, but fewer than 10% put their secondary or tertiary homes on the rental market, preferring exclusivity and personal use to yield.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.79
Buying 129.29, selling 130.29.
As at
Central Bank of Kenya mean reference rate, as reported in this briefGBP / KES
171.92
As at
Central Bank of Kenya mean reference rate, as reported in this briefEUR / KES
145.29
As at
Central Bank of Kenya mean reference rate, as reported in this brief
Equities
NSE All-Share
238.10
−1.86%; up 25.32% for the year
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,238.80
−1.13%; up 15.50% for the year
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
The hold is what anchors the short end.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.51%
Eased 0.08 percentage points.
As at
As reported in this briefKenya 25-year infrastructure bond
13.58%
As at
As reported in this brief91-day Treasury bill
8.7615%
As at
Central Bank of Kenya auction, as reported in this brief182-day Treasury bill
8.8744%
As at
Central Bank of Kenya auction, as reported in this brief364-day Treasury bill
9.0352%
As at
Central Bank of Kenya auction, as reported in this brief
At a glance
- 1US September inflation accelerated to 3.7% year on year, repricing the odds of another Federal Reserve hike before year-end to roughly 39%. The Nasdaq fell 1.88% in its sharpest retreat since July, gold dropped $69.40 and silver crashed 6.32%.
- 2Kenya Pipeline reported its first annual results since listing in March: net profit up 13.1% to KSh 11.58 billion on revenue above KSh 42.98 billion, with a proposed final dividend of KSh 5.81 billion, or KSh 0.32 a share, and book closure on 30 November.
- 3Title deed issuance fell 35.3% to 282,392 in the year to June 2026, the first drop in five years, while 176 affordable housing projects — 15% of the pipeline — have stalled because funding lags contractor obligations.
Sources
- Serrari Group desk compilation, 15 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data