
14 October 2026
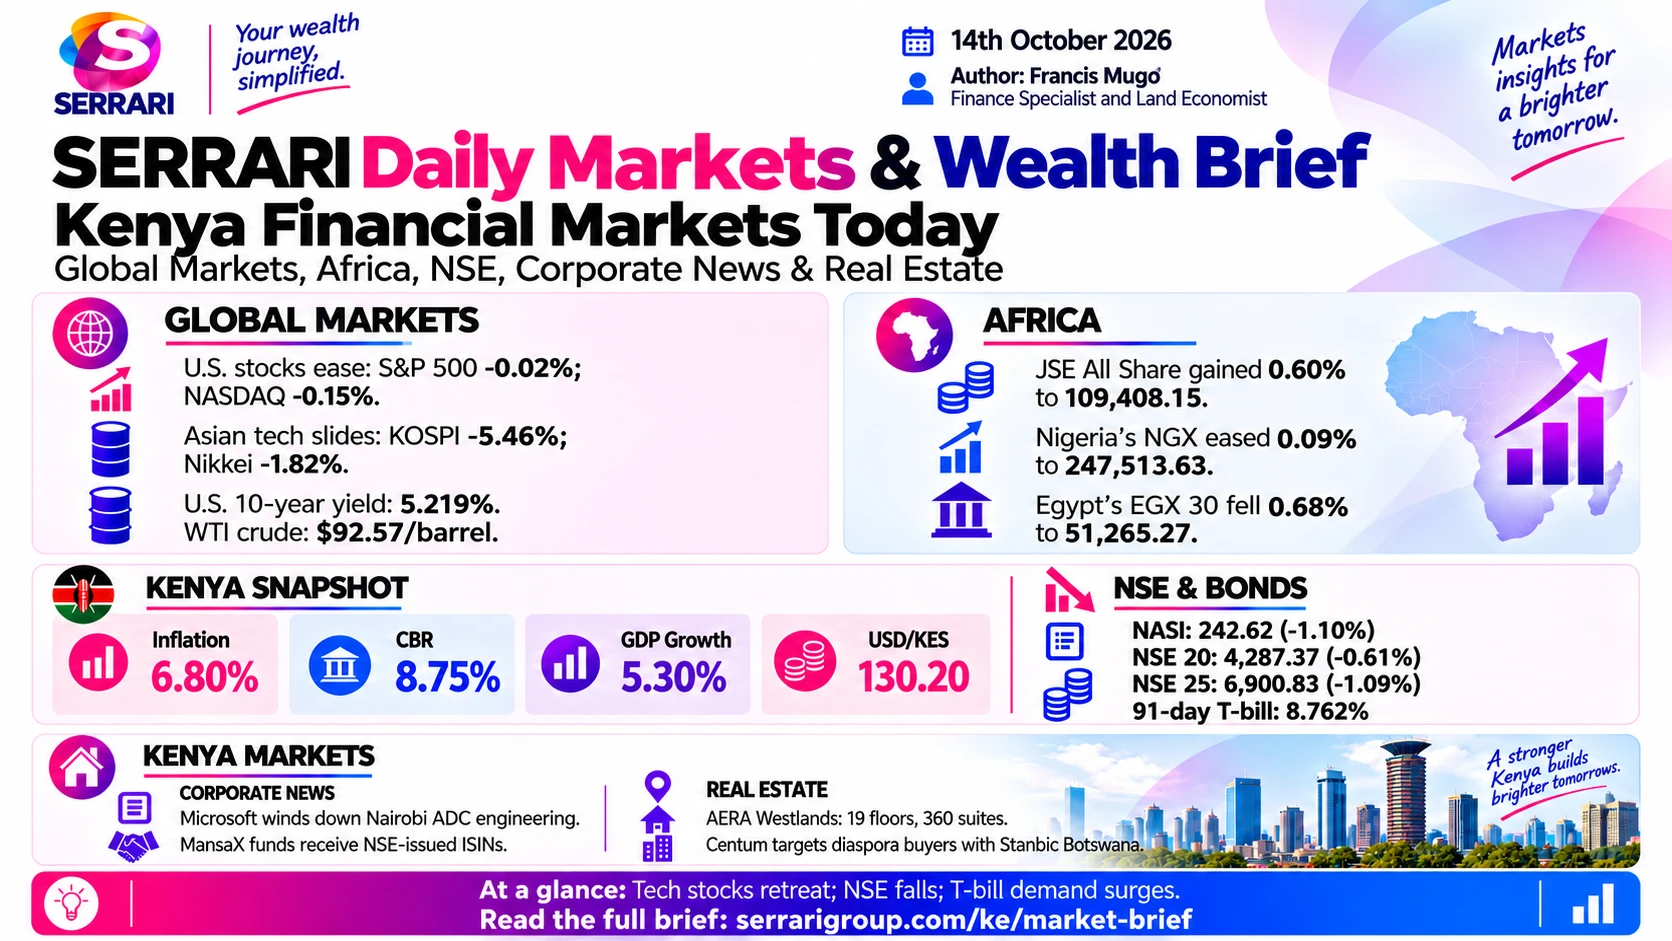
A memory-chip shock out of China drove the Kospi down 5.46% and the Nikkei 1.82%, while Wall Street drifted lower despite stronger bank profits. The shilling crossed 130 to the dollar and the NASI fell 1.10% to 242.62, even as Treasury bill bids reached KSh 75.37 billion against a KSh 28 billion target.

Global Markets
Figures as at · Closing levels for Tuesday 13 October 2026, as reported in this brief
Wall Street drifted lower even as JPMorgan Chase, Goldman Sachs, Wells Fargo and Citigroup all reported stronger profits — their shares flipped between small gains and deeper losses, with Citigroup down roughly 5.5%. The real damage was in Asian technology, where a Chinese memory-chip breakthrough triggered a rout.
US indices
| Index | Close | Net change | Change |
|---|---|---|---|
| S&P 500 | 7,805.45 | −1.79 | −0.02% |
| Dow Jones Industrial Average | 51,670.10 | −180.45 | −0.35% |
| Nasdaq Composite | 27,204.38 | −41.52 | −0.15% |
| Russell 2000 | 2,783.37 | −11.11 | −0.40% |
Europe and Asia
- Stoxx Europe 600: Fell 0.10% to 635.01.
- FTSE 100: Slid 0.10% to 10,645.62.
- DAX: Ended 0.10% lower at 25,259.90.
- CAC 40: Down 0.10% to 7,827.63, with European luxury slipping after LVMH posted weaker-than-expected third-quarter organic sales on cooled demand in mainland China.
- Kospi: Plummeted 5.46% to its lowest since July as SK Hynix fell sharply on fears of competition from China’s CXMT.
- Nikkei 225: Dropped 1.82% to 67,777.52 on downstream electronics de-risking.
- Hang Seng: Bucked the regional trend, rising 0.30% to 24,345.22.
- Shanghai Composite: Gained 0.10% to 3,800.86.
What drove the session
- The Chinese chip factor: CXMT announced plans to launch an advanced, highly competitive silicon architecture by year-end, triggering rapid global equity rebalancing across flash memory and semiconductors. Comments from Broadcom’s chief executive warning about excessive corporate AI lab spending deepened the selloff.
- Rates and energy: The 10-year Treasury yield eased back to just above 5.22%. Oil hovered near $94.45 a barrel on WTI as markets weighed an authorised diesel supply increase against Middle East tensions, and the softer crude gave relief to airline and industrial stocks — keeping Europe insulated from the harsher selloffs in Seoul and Tokyo.
Global Yields
Figures as at · Yields for 13 October 2026, as reported in this brief
Benchmark sovereign yields
| Issuer | Yield | Session change | Context |
|---|---|---|---|
| US 10-year Treasury | 5.219% | −2.4 bps | Just below last week’s 24-year high of 5.365%; up 106 basis points this year |
| US 30-year Treasury | 5.564% | −3.4 bps | Retreated from last week’s multi-decade peak of 5.733% |
| Germany 10-year Bund | Below 3.450% | Decreased | Lowest since 9 September on safe-haven flows |
Commodities
Figures as at · Closing prices for 13 October 2026, as reported in this brief
- Brent crude: Declined 0.57% to settle near $105.41–$106.04 a barrel.
- WTI crude: Fell 0.50% to close around $92.57 a barrel.
- Gold: December futures recovered to trade between $4,190 and $4,216 a troy ounce.
- Copper: Settled near $14,641 a tonne in spot terms, or about $6.80 a pound on futures desks.
Africa
Figures as at · Closing levels for 13 October 2026, as reported in this brief
Sovereign bond and bill yields
| Instrument | Yield | Context |
|---|---|---|
| South Africa 10-year bond | 8.92% | Down 5 basis points to a three-week low on safe-haven inflows |
| South Africa 30-year bond | 9.23% | Eased as long-term inflation fears softened |
| Egypt 91-day Treasury bill | 24.115%–24.189% | Near historic highs, countering a domestic liquidity crunch |
| Egypt 3-year fixed bond | 23.981% | Auction rate reflecting a deeply inverted curve |
| Nigeria 364-day Treasury bill | 15.85%–15.89% | Edged down on heavy institutional oversubscription |
| Nigeria 10-year secondary bond | About 17.00% | Anchored high by persistent central bank open-market sales |
Equities
- South Africa: The FTSE/JSE All Share rose 648.31 points, or 0.60%, to 109,408.15, inside a range of 108,752.53 to 110,050.28 on volume of 226.35 million shares.
- Nigeria: The NGX All-Share eased 222.61 points, or 0.09%, to 247,513.63. Market capitalisation fell ₦144.54 billion to ₦160.71 trillion, on 394.16 million shares across 38,660 deals worth ₦21.35 billion.
- Egypt: The EGX 30 fell 348.65 points, or 0.68%, to 51,265.27, on turnover of EGP 9.838 billion across 273,328 transactions.
What moved the region
- Global de-risking: The technology rout in US and Asian markets pushed global asset managers temporarily into high-yielding, stable emerging market debt, giving South African bonds a solid lift.
- Aggressive domestic issuance: Fiscally constrained states including Egypt and Nigeria kept offering large premiums on short-term paper, parking commercial bank liquidity in risk-free government assets rather than private sector lending.
Currencies
- South African rand: Appreciated roughly 0.2% to close near 16.50–16.54 per dollar, shrugging off mining output down 12.7% year on year, helped by a softer greenback and stabilising energy import costs.
- Nigerian naira: The official window weakened marginally to ₦1,332.97, losing ₦0.87 on the day, while the parallel market held flat at ₦1,375, with street margins around ₦1,365 buying and ₦1,390 selling.
- Egyptian pound: Softened 0.27% to 52.79 per dollar. Inverted treasury yields kept foreign institutional interest high, but heavy public debt servicing capped appreciation.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 13 October 2026, as reported in this brief
Indices and movers
- NSE All-Share: Fell 2.70 points, or 1.10%, to 242.62.
- NSE 20-Share: Fell 26.18 points, or 0.61%, to 4,287.37.
- NSE 25-Share: Fell 75.91 points, or 1.09%, to 6,900.83.
- Gainers: Mid-caps and agricultural counters showed resilience. Uchumi Supermarket led with 7.41%, followed by Kakuzi at 4.12% and Unga Group at 2.84%.
- Decliners: Heavy selling hit blue-chip telecom and financial tickers, with Safaricom, I&M Holdings and CIC Insurance all closing lower on institutional volume pruning.
- MansaX ISINs: Standard Investment Bank’s MansaX Special Funds received International Securities Identification Numbers directly from the NSE, a step designed to improve global visibility and attract international institutional inflows.
Government securities
- Record Treasury bill demand: Primary auctions drew KSh 75.37 billion in bids against a target of KSh 28 billion — a 269.2% performance rate. The 91-day alone pulled in KSh 50.2 billion.
- The yield curve: The benchmark 10-year held flat at 12.59%. Short-term pricing edged down on oversubscription: the 91-day settled at 8.762%, the 182-day at 8.874% and the 364-day at 9.035%.
- Secondary market: Turnover for government bonds is reported at KSh 53.8 billion, down 40.8%, as investors pulled back from the secondary floor to lock liquidity into primary short-term assets. Those are the same figures the 13 October brief carried.
- Sovereign exposure warnings: Moody’s, Fitch and the World Bank all warned on local bank balance sheets, with Kenyan commercial banks’ sovereign exposure at KSh 2.53 trillion — about 1.8 times their equity, which analysts say limits private-sector credit strength.
- Refinancing pressure: To bridge a targeted KSh 987 billion domestic deficit, the CBK raised its monthly primary bond sale threshold above KSh 100 billion, and is running two bond issues and a switch auction every month to manage redemption cliffs.
- The 30-year reopening: Investors finalised positioning for the KSh 50 billion re-opened 30-year fixed-coupon bond, maturing in 2056 with a 12.5% coupon, which closes for bidding on 14 October.
Kenya Forex
Figures as at · Central Bank of Kenya rates, 13 October 2026, as reported in this brief
The shilling crossed 130 to the dollar on the official mean rate. Commercial bank quotes ranged much wider, between 127.70 buying and 132.70 selling.
- East African crosses: The brief quotes KES/TZS at 21.05, KES/UGX at 28.60, KES/RWF at 10.55 and KES/BIF at 22.42. These figures have moved inconsistently across recent briefs and are reported here as published rather than treated as settled.
Official CBK rates
| Currency | Mean | Buying | Selling |
|---|---|---|---|
| US dollar | 130.20 | 129.70 | 130.70 |
| Euro | 145.72 | 145.10 | 146.34 |
| British pound | 173.65 | 172.92 | 174.38 |
Kenya Corporate News
Figures as at · As reported in this brief
The Safaricom stake sale is blocked
- Court of Appeal: The court rejected the government’s application to freeze a previous High Court order, permanently blocking the state’s KSh 204.3 billion sale of its 15% stake in Safaricom to Vodacom. The judges ordered the 6 billion ordinary shares returned immediately to state ownership and scheduled further directions for 23 October 2026.
Technology and capital markets
- Microsoft: The company has told employees it is winding down engineering at its Africa Development Centre in Westlands, placing between 400 and 500 specialised software engineering roles at risk. It ends a $100 million, seven-year initiative to build international products from Africa, and stems from global corporate consolidation rather than local conditions. ICT Cabinet Secretary William Kabogo has met delegations to lobby for local talent preservation.
- Dangote receipts: The Capital Markets Authority confirmed a two-week extension of the Dangote Petroleum Refinery offer to 27 October 2026, with the entry minimum for the underlying depositary receipts on the NSE set at KSh 53.50 per unit.
Agriculture
- Litein tea protest: Operations at Litein Tea Factory were paralysed for six hours as farmers protested and issued a seven-day ultimatum demanding management resign, over a KSh 18 bonus payout announced by the Kenya Tea Development Agency.
Real Estate
Figures as at · As reported in this brief
Building up
- Kibra skyscraper: After the county dropped building height caps, Beyond Imagination Construction Co. Limited filed to build an ultra-modern mixed-use residential skyscraper in the Kibra growth corridor off the Ring Road-Kilimani intersection.
- AERA Westlands: Sales accelerated for the newly unveiled 19-floor residential tower of 360 suites near Sarit Centre, targeting premium rental yields from expatriate markets.
- Masokani: Commercial developers reported an unprecedented surge in land purchases along the Kangundo Road corridor, with buyers banking on newly expanded arterial bypass layouts.
State money and diaspora money
- KSh 800 billion in works contracts: During an inspection of the Sh128 million Gakindu ESP Market in Nyeri County, the executive said the State Housing Fund had finalised KSh 800 billion in contracts covering public markets, student hostels and institutional military and police housing across several counties.
- Diaspora inflows: Centum Real Estate partnered with Stanbic Bank Botswana on a property investment drive targeting Kenya’s KSh 6 billion monthly remittance pipeline.
A tax change developers are watching
- The 15% rate is gone: The preferential 15% corporate tax rate for entities building more than 100 residential units a year has been eliminated. Developers now pay the standard 30% rate, raising fears that standard housing units will see a secondary price rise as firms protect margins.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
130.20
Buying 129.70, selling 130.70. Commercial bank quotes ranged 127.70 to 132.70.
As at
Central Bank of Kenya mean rate, as reported in this briefGBP / KES
173.65
As at
Central Bank of Kenya mean rate, as reported in this briefEUR / KES
145.72
As at
Central Bank of Kenya mean rate, as reported in this brief
Equities
NSE All-Share
242.62
−1.10%, down 2.70 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,287.37
−0.61%, down 26.18 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,900.83
−1.09%, down 75.91 points
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
Anchored to preserve exchange rate and price stability.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.59%
Held flat.
As at
As reported in this brief91-day Treasury bill
8.762%
The 91-day drew KSh 50.2 billion of the KSh 75.37 billion in total bids.
As at
Central Bank of Kenya auction, as reported in this brief182-day Treasury bill
8.874%
As at
Central Bank of Kenya auction, as reported in this brief364-day Treasury bill
9.035%
As at
Central Bank of Kenya auction, as reported in this brief
At a glance
- 1The Court of Appeal rejected the government’s application to freeze a High Court order, permanently blocking the state’s KSh 204.3 billion sale of its 15% Safaricom stake to Vodacom. The judges ordered 6 billion ordinary shares returned to state ownership, with further directions on 23 October.
- 2Microsoft is winding down engineering at its Africa Development Centre in Westlands, putting 400 to 500 specialised software roles at risk and ending a $100 million, seven-year initiative to build international products from Africa.
- 3Treasury bill auctions drew KSh 75.37 billion against a KSh 28 billion target — a 269.2% performance rate, with the 91-day alone pulling in KSh 50.2 billion — as investors moved liquidity out of the secondary bond floor.
Sources
- Serrari Group desk compilation, 14 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data