
13 October 2026
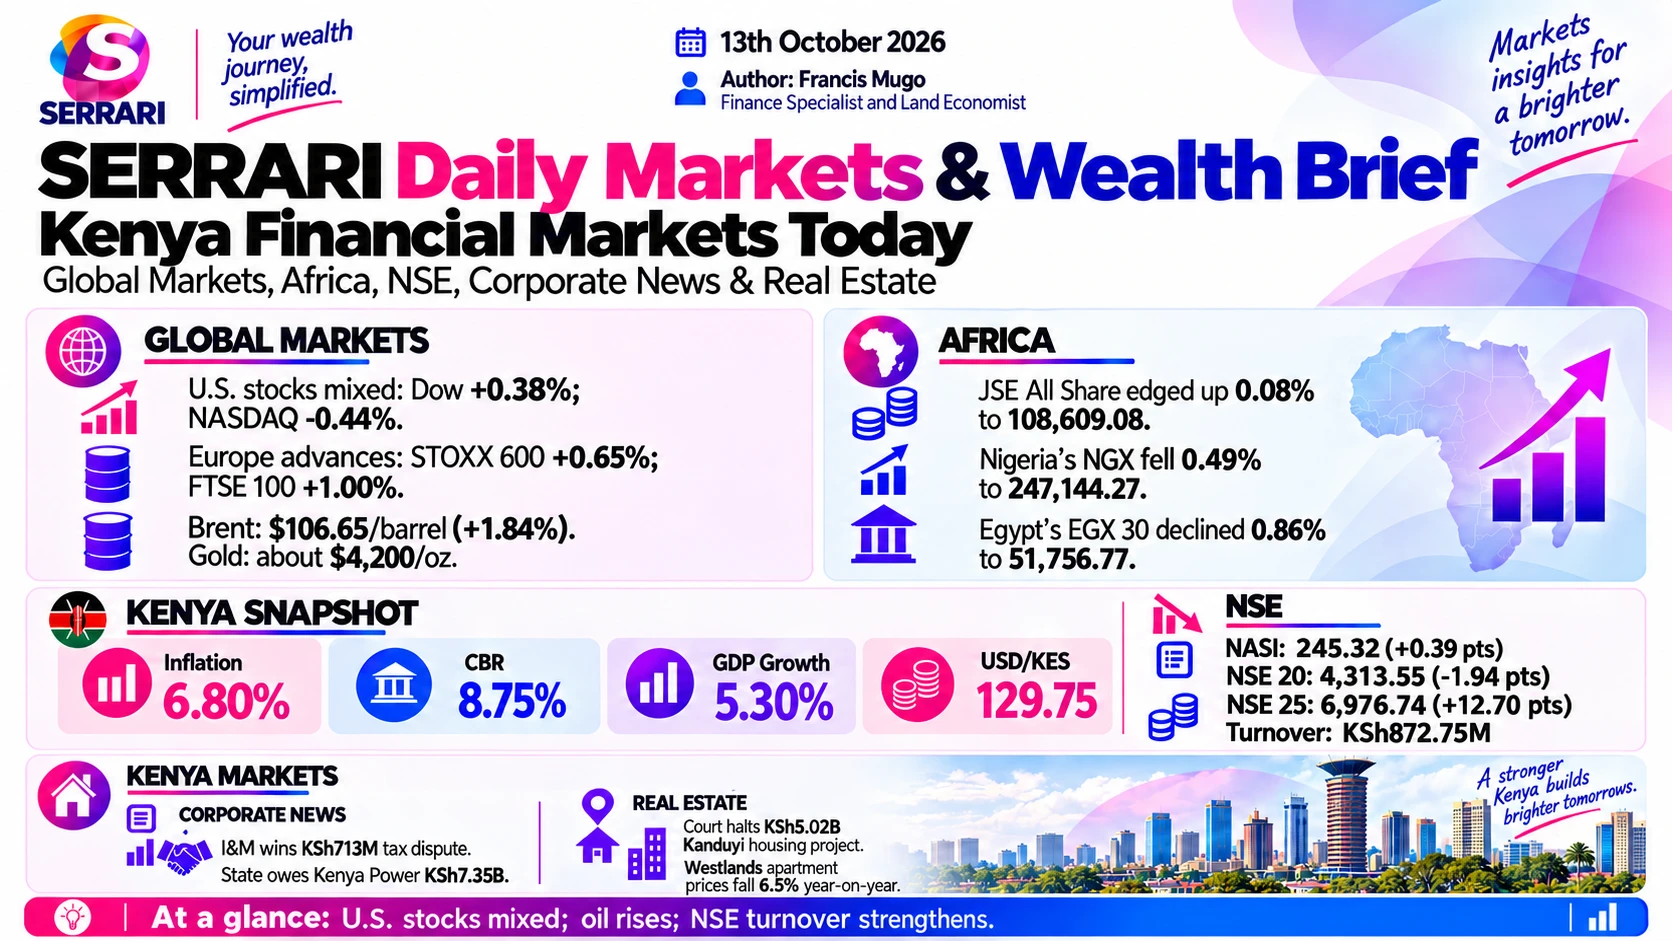
US stocks split as the Dow gained 0.38% while the Nasdaq fell 0.44% on an intensifying memory-chip price war, and Brent climbed 1.84% to $106.65 a barrel. Nairobi turnover reached KSh 872.75 million even as offshore selling took KSh 40.06 billion off market value over two weeks.

Global Markets
Figures as at · Closing levels for Monday 12 October 2026, as reported in this brief
Wall Street split, with value rotation lifting the Dow while a memory-chip price war dragged the Nasdaq down. Europe took a second consecutive winning day as falling bond yields lifted equities, and Asian chipmakers took heavy losses.
Major currency pairs
| Pair | Close | Change | Driver |
|---|---|---|---|
| EUR/USD | 1.1172 | −0.27% | Near 17-month lows as French fiscal deficit concerns undermined the euro |
| USD/JPY | 158.66 | +0.22% | The dollar gained through a Japanese holiday on wide US–Japan rate differentials |
| GBP/USD | 1.3224 | −0.08% | Sterling drifted lower ahead of critical domestic growth data |
| AUD/USD | 0.6966 | −0.27% | Commodity pressure and global tech risk aversion weighed on the Aussie |
| USD/CAD | 1.4266 | Stable | Steady in a holiday-thinned session, supported by crude |
| Dollar index | 102.44 | +0.22% | Closer to multi-month highs on haven appeal and hawkish Fed rate paths |
United States
- Dow Jones Industrial Average: Up 0.38%, or 195.60 points, to 51,850.55, on value rotation, strong energy gains and a prominent Salesforce upgrade.
- S&P 500: Down 0.06%, or 4.30 points, to 7,807.24. It hovered near record territory on positive breadth, but heavy tech pullbacks kept it flat.
- Nasdaq Composite: Down 0.44%, or 120.27 points, to 27,245.90, dragged by semiconductor infrastructure and an intensifying memory-chip price war.
- Russell 2000: Down 0.44%, or 12.50 points, to 2,794.48, mirroring the Nasdaq after a strong prior week.
Europe and Asia
- FTSE 100: Up 1.00%, or 105.73 points, to 10,656.28, on a rebound in financials and medical equipment.
- DAX: Up 0.76%, or 179.91 points, to 23,803.96.
- CAC 40: Up 0.38%, or 33.40 points, to 8,879.46, held back by LVMH.
- STOXX 600: Up 0.65% to 635.65, a second consecutive winning day as falling bond yields lifted equities.
- Kospi: Plunged 3.65% to 2,900.50 as major chipmakers took heavy single-day losses.
- Shanghai Composite: Down 0.43% to 3,797.24 as broader tech anxieties offset local gains.
- Hang Seng: Up 0.25% to 24,271.20, bucking the mainland trend.
Global Yields
Figures as at · Yields for 12 October 2026, as reported in this brief
US and Japanese cash desks were closed, so those levels are frozen rather than traded. European yields eased on a reported Russia-Ukraine energy ceasefire.
Benchmark 10-year sovereign yields
| Issuer | Yield | Context |
|---|---|---|
| United Kingdom (gilt) | 5.45% | Up 3 basis points; the 30-year hovered near 28-year highs above 6% on fiscal anxiety before the Autumn Budget |
| United States (Treasury) | 5.23%–5.24% | Frozen with cash desks closed, near multi-decade highs ahead of September CPI |
| Germany (Bund) | About 2.85% | Eased as a reported Russia-Ukraine energy ceasefire brought temporary relief to eurozone inflation expectations |
| Italy (BTP) | 4.54% | Eased from recent multi-year peaks; the BTP-Bund spread narrowed to 106.8 basis points |
| Japan (JGB) | 3.00% | Frozen for a holiday, just below the 3.10% milestone — the highest 10-year coupon Tokyo has issued since 1996 |
Commodities
Figures as at · Closing prices for 12 October 2026, as reported in this brief
- Brent crude: $106.65 a barrel, up 1.84%, on Middle East escalation and Ukrainian energy grid strikes. Note that the brief’s Africa section separately refers to Brent dropping toward $103 on the same day; both figures are reported where the source places them.
- Gold: Spot held around $4,200 an ounce, stable at sustained historical highs on structural risk hedging.
Africa
Figures as at · Closing levels for 12 October 2026, as reported in this brief
Benchmark sovereign yields
| Issuer | Instrument | Yield | Note |
|---|---|---|---|
| South Africa | 10-year bond | 8.960% | Up 1 basis point on global energy inflation anxieties |
| South Africa | 30-year bond | 9.310% | Rising alongside the 10-year |
| Egypt | 1-year (364-day) T-bill | 25.853% | Inverted curve persists; high bids hit 29.9% |
| Nigeria | 364-day T-bill | 15.890% | Lowest in nearly a year after the 350 basis point cut |
Equities
- South Africa: The FTSE/JSE All Share closed at 108,609.08, up 84.31 points or 0.08%, inside a narrow band of 107,687.93 to 108,871.12. Energy and retail offered subtle support, but participation was muted and volume fell to roughly 192.05 million shares.
- Nigeria: The NGX All-Share fell 1,219.28 points, or 0.49%, to 247,144.27, wiping ₦791.67 billion off market capitalisation to ₦160.47 trillion. Profit-taking in consumer goods and industrials offset a 9.93% jump in Guinness Nigeria.
- Egypt: The EGX 30 fell 448.24 points, or 0.86%, to 51,756.77 after opening at 52,206.70. Breadth was firmly negative, with 184 decliners against 22 gainers.
Auctions and dispatches
- Egypt: The Central Bank of Egypt drew over EGP 144 billion in bids for 364-day paper alone, pushing the weighted average stop rate to 25.853%, with high bids reaching 29.9% amid a domestic liquidity crunch. The curve stays inverted against a 10-year at 23.370%.
- Nigeria: After the central bank’s 350 basis point cut to 23.00%, institutional investors scrambled for longer tenors. The 364-day stop rate dropped to 15.890%, its lowest in nearly a year, with the 182-day at 15.800%.
Currencies
- South African rand: USD/ZAR at R16.51, up 0.08%, retaining support from firming spot gold, with a retail range of R16.50–R16.55.
- Nigerian naira: The official market closed at ₦1,331.16, up 0.09%, while parallel counters quoted ₦1,370–₦1,390 for tuition and travel allocations.
- Egyptian pound: USD/EGP at 52.63, up 0.10%, in a range of 52.53 to 52.73.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 12 October 2026, as reported in this brief
Indices and activity
- NSE All-Share: Closed at 245.32, gaining 0.39 points.
- NSE 20-Share: Closed at 4,313.55, shedding 1.94 points.
- NSE 25-Share: Closed at 6,976.74, up 12.70 points.
- NSE 10-Share: Closed at 2,742.79, gaining 8.19 points.
- Turnover: Equity turnover stood at KSh 872.75 million, with 18,676,076 shares changing hands.
Movers and flows
- Gainers: Kenya Airways rose 7.64%, Sameer Africa 6.31% and Nairobi Business Ventures 5.51%, with I&M Holdings and EABL also among the notable advancers.
- Losers: Uchumi Supermarket, Kenya Re-Insurance, Williamson Tea Kenya and Britam Holdings were the counters under pressure.
- Foreign flows: Offshore investors have returned to heavy selling, pressuring major banking and telecommunications weights. The exchange has shed KSh 40.06 billion in market value across two consecutive weeks, largely on offloading of large caps.
- Dangote GDRs: Local retail and institutional investors have until 5:00 PM EAT on Tuesday 13 October to apply for the Dangote depositary receipt programme, ahead of a trading debut on 8 December 2026.
Government securities
- 10-year benchmark: Closed at 12.590%.
- Secondary market: Total secondary bond trading volume has crossed KSh 2.503 trillion for the year, putting the market on course to challenge the highs recorded in 2025, despite a week-on-week dip in volumes.
- Treasury bills: The 91-day weighted average yield sits at 8.7615% on a 272% subscription rate, the 182-day at 8.8744% on 73% performance, and the 364-day at 9.0352% on 28% — still under-subscribed as investors avoid longer duration.
- October issuance: The CBK has published prospectuses for the next leg of long-term funding, with secondary trading in SDB1/2011/030 and FXD1/2026/030 due to start on 19 October 2026.
Kenya Forex
Figures as at · Central Bank of Kenya mean rates, 12 October 2026, as reported in this brief
Importers face tighter liquidity as the spot rate trended toward 129.74 intraday, raising raw material costs against the previous week. The shilling held its position against East African counterparts, buffered by reserves and diaspora remittances.
- East African crosses: KES/UGX at 31.85 with the Ugandan shilling weakening, KES/TZS at 20.35 and stable, and KES/RWF at 11.37 and slightly soft. The Ugandan slide to 4,132 per dollar has the Bank of Uganda watching interbank liquidity, with manufacturers expecting a spike in input costs.
Official CBK rates and typical bank quotes
| Pair | CBK mean | Typical buying | Typical selling |
|---|---|---|---|
| USD / KES | 129.75 | 129.25 | 130.25 |
| GBP / KES | 171.67 | 171.10 | 172.24 |
| EUR / KES | 145.32 | 144.80 | 145.85 |
Kenya Corporate News
Figures as at · As reported in this brief
Banking, energy and the courts
- I&M Bank: The High Court ruled in the lender’s favour in a KSh 713 million tax dispute with the Kenya Revenue Authority, centred on tax deductions for bad debts.
- Kenya Power: Outstanding electricity bills owed by government ministries, departments and state agencies have climbed to KSh 7.35 billion, squeezing the utility’s working capital.
- Kenya Pipeline: The High Court struck out a petroleum workers’ union petition challenging the appointment of Faith Bett Boinett as chairperson, dismissing it on jurisdictional grounds and holding that employment grievances belong before the labour relations court.
Retail and multinationals
- Quickmart: The retailer terminated multi-million shilling contracts held by its original founders, a restructuring described as a clean-up before its public listing.
- Microsoft: After a meeting with EMENA executives, the government pressed the company to protect local engineering jobs at its Nairobi Development Centre, as it rebalances its global workforce to redirect capital into artificial intelligence infrastructure.
Real Estate
Figures as at · As reported in this brief
Courts and policy
- Kanduyi halted: The Environment and Land Court in Bungoma halted the KSh 5.02 billion Kanduyi Airstrip Affordable Housing Project. Justice Kossy Bors ruled the smart city scheme unconstitutional over a failure of public participation and inadequate environmental clearance. It was to build 2,034 units.
- Kiambu rate waiver: Governor Kimani Wamatangi announced a final 100% waiver on interest and penalties for outstanding land rates. Owners have until 31 October 2026 to clear principal balances before penalties resume.
Where buyers are moving
- Westlands: Rapid high-rise oversupply has driven a 6.5% year-on-year price decline for apartments, according to the HassConsult Property Index. Buyers are scrutinising cramped high-density units and favouring larger spaces over prime location.
- Masokani: Speculators and developers are buying deeper into Machakos County along the Koma-Kenol and Nairobi-Kangundo Road corridor. Standard 50-by-100-foot plots near the main tarmac now trade at a minimum of KSh 1.5 million as commercial property takes shape.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.75
Typical bank quotes 129.25 buying, 130.25 selling.
As at
Central Bank of Kenya mean rate, as reported in this briefGBP / KES
171.67
As at
Central Bank of Kenya mean rate, as reported in this briefEUR / KES
145.32
As at
Central Bank of Kenya mean rate, as reported in this brief
Equities
NSE All-Share
245.32
Up 0.39 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,313.55
Down 1.94 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,976.74
Up 12.70 points
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 872.75 million
Across 18.68 million shares.
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
Held on 7 October for a fourth consecutive meeting.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.59%
Unchanged from the level published on 12 October.
As at
As reported in this brief91-day Treasury bill
8.7615%
272% subscription rate.
As at
Central Bank of Kenya auction, as reported in this brief182-day Treasury bill
8.8744%
73% performance rate.
As at
Central Bank of Kenya auction, as reported in this brief364-day Treasury bill
9.0352%
28% performance rate; still under-subscribed.
As at
Central Bank of Kenya auction, as reported in this brief
At a glance
- 1The Environment and Land Court in Bungoma halted the KSh 5.02 billion Kanduyi Airstrip affordable housing project, ruling it unconstitutional over failed public participation and inadequate environmental clearance. It was to deliver 2,034 units.
- 2I&M Bank won a KSh 713 million tax dispute against the Kenya Revenue Authority over deductions on bad debts, while unpaid government electricity bills owed to Kenya Power reached KSh 7.35 billion.
- 3Equity turnover reached KSh 872.75 million on 18.68 million shares, but offshore selling of large caps has taken KSh 40.06 billion off NSE market value across two consecutive weeks.
Sources
- Serrari Group desk compilation, 13 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data