
12 October 2026
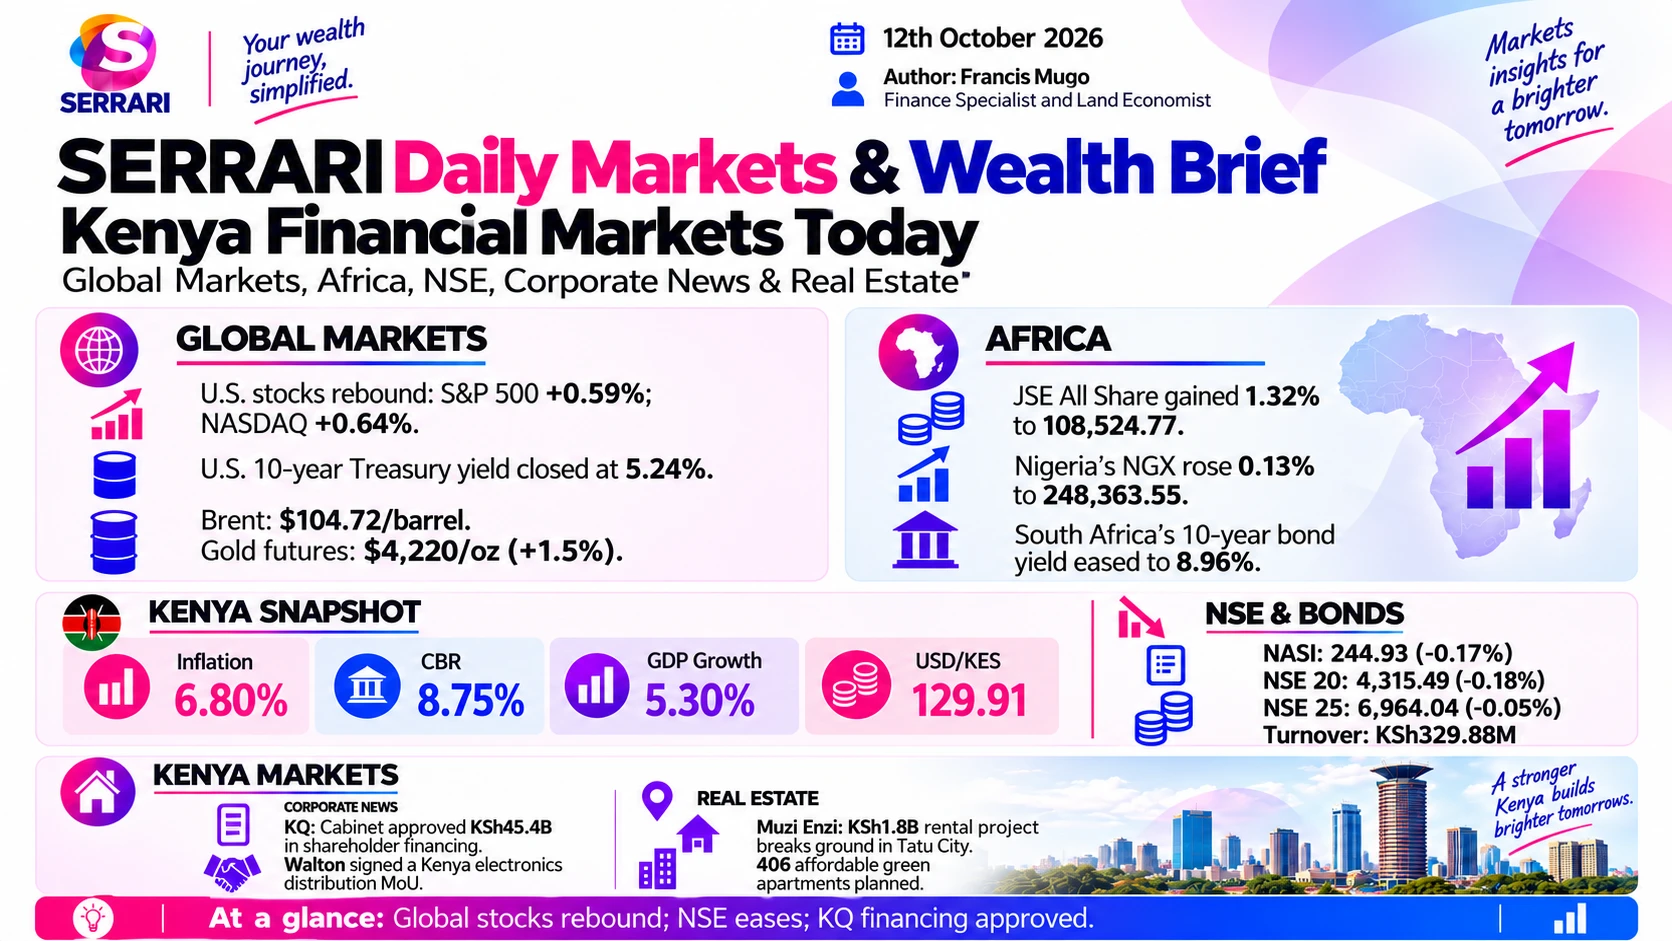
US stocks rebounded into the weekend, with the S&P 500 up 0.59% and the Nasdaq 0.64%, while the 10-year Treasury yield closed at 5.24% and snapped a five-week run of increases. Nairobi eased across the board as the NASI slipped 0.17% to 244.93, and the Cabinet approved KSh 45.4 billion in shareholder financing for Kenya Airways.

Global Markets
Figures as at · Closing levels for Friday 9 October 2026, as reported in this brief
US stocks rallied sharply as technology recovered from the week’s sell-off. Investors shrugged off a report that OpenAI’s annualised revenue missed projections and looked ahead to third-quarter bank earnings. European benchmarks erased most of their losses from earlier in the week; Asia was mixed.
Major currency pairs
| Pair | Close | Change | Context |
|---|---|---|---|
| EUR/USD | 1.1204 | −0.13% | Multi-month lows, down over 3.5% in a month on growth disparities and energy risk premiums |
| USD/JPY | 158.26 | +0.24% | The yen kept sliding, highly sensitive to long-term US yields |
| GBP/USD | 1.3237 | −0.05% | A tight sideways channel, pressured by the dollar but supported by Bank of England tightening expectations |
| AUD/USD | 0.6690 | +0.15% | Modest support from a late-week commodities rebound |
| USD/CAD | 1.3685 | −0.10% | The Canadian dollar edged up as oil stabilised near $104 after the temporary diesel supply agreement |
United States
- Dow Jones Industrial Average: Up 0.83%, or 423.31 points, to close at 51,654.95.
- S&P 500: Up 0.59%, or 46.18 points, to 7,811.54 — close to its record high.
- Nasdaq Composite: Up 0.64%, or 172.83 points, to 27,366.17. Tech and pharmaceutical gains propelled the market.
Europe
- STOXX Europe 600: Gained 0.75% to close at 625.51.
- DAX: Up 0.6% to 24,806.97.
- CAC 40: Up 0.5% to 7,729.69.
- FTSE 100: Up 0.3% to 10,441.60.
Asia-Pacific
- Nikkei 225: Closed up 0.6% to 69,030.92.
- Hang Seng: Rose 1.4% but logged a net weekly loss, as rising US bond yields dragged on tech and financial majors.
- Shanghai Composite: Dropped 2.6% to 3,770.66, pressured by a retreat in domestic semiconductor names amid fears of US export limits and structural competition.
- KOSPI: Closed for a holiday, alongside Taiwan, which thinned regional fixed-income volatility.
Global Yields
Figures as at · Yields for 9 October 2026, as reported in this brief
United States
- 2-year Treasury: Climbed 4 basis points to 4.80%, continuing to price a higher-for-longer framework with the federal funds rate at 3.75%–4.00%.
- 10-year Treasury: Up about 1 basis point to 5.24%, snapping an aggressive five-week run of rising yields.
- 30-year Treasury: Slid under a basis point to finish at 5.60%.
Europe and Asia
- Germany: The 10-year Bund settled near 3.50%, reflecting a mild decompression of the energy shock premiums that have burdened eurozone growth projections since early 2026.
- United Kingdom: The 10-year gilt traded firmly around 5.46%, under stubborn domestic inflation and broader term premium expansion.
- France: The 10-year OAT stayed elevated on doubts over the government’s structural ability to pare down its deficit amid widespread demonstrations.
- Japan: The 10-year JGB eased 7 basis points to close at 3.016%.
- China: The 10-year bucked the global trend, with yields sliding lower.
Commodities
Figures as at · Closing prices for 9 October 2026, as reported in this brief
- Brent crude: Settled up 0.42%, or $0.44, at $104.72 a barrel.
- WTI crude: Rose 0.39%, or $0.36, to finish at $91.85 a barrel.
- Gold: Futures surged 1.5% to settle at $4,220 an ounce.
- Silver and platinum: Silver edged higher to trade around $60 an ounce, and platinum led the complex with a jump of 3.67% during the session.
- Copper: Futures advanced 1.90% to close at $6.69 a pound.
Africa
Figures as at · Closing levels for 9 October 2026, as reported in this brief
Major African indices
| Exchange | Close | Change | Year to date |
|---|---|---|---|
| South Africa — FTSE/JSE All Share | 108,524.77 | +1.32% | Modest gain in local terms, recovering from monthly lows |
| Nigeria — NGX All-Share | 248,363.55 | +0.13% | Bounced from a seven-day losing streak; leads Africa at about 60% |
| Egypt — EGX 30 | 53,265.16 | −0.06% (7 Oct close) | Steady near September highs, up about 43.5% year on year |
Sovereign yields
- South Africa: The 10-year local government bond strengthened 7 basis points to 8.96%, as easing Middle East oil supply concerns supported the rand.
- Egypt: The 10-year was flat at 23.37%, sitting at one-month and one-year highs after recent macro tightening.
Currencies
- South African rand: USD/ZAR at R16.62, steady to slightly firmer, supported by recovering local equities and cooling crude.
- Nigerian naira: ₦1,331.77 official and ₦1,390.00 parallel, held in a stable corridor by central bank intervention and reserves.
- Egyptian pound: USD/EGP at 52.37, a touch stronger at −0.06%, hovering near historic stabilisation levels after major liquidity management.
- Ghanaian cedi: USD/GHS at 11.45 and weakening, on persistent corporate foreign-currency demand.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 9 October 2026, as reported in this brief
Indices and liquidity
- NSE All-Share: Down 0.41 points, or 0.17%, to 244.93.
- NSE 20-Share: Down 7.77 points, or 0.18%, to 4,315.49.
- NSE 25-Share: Down 3.34 points, or 0.05%, to 6,964.04.
- NSE 10-Share: Down 2.41 points, or 0.09%, to 2,734.60.
- Market size: Capitalisation settled at KSh 4.110 trillion on turnover of KSh 329.88 million across 8.51 million shares.
Movers
- Gainers: Kenya Airways rose 7.34%, National Bank of Kenya 4.43%, Stanbic Holdings 3.63% and Home Afrika 3.28%.
- Losers: Profit-taking pulled BOC Kenya down 9.09%, Eveready East Africa 8.00% and Stanlib Fahari I-REIT 6.88%.
Fixed income
- 10-year benchmark: Climbed 28 basis points to 12.59% on global frontier market spillovers.
- Treasury bills: Drew KSh 75.4 billion in bids, with the short-term curve still heavily bid for liquidity.
- Secondary market: Turnover in all government securities fell 40.8% to KSh 53.8 billion, a sharp slowdown from KSh 90.9 billion the week before.
- Eurobonds: The brief reports the 2032 yield up 109 basis points to 8.752% and the 2034 up 107 basis points to 9.202%. Those are the same levels and the same daily moves the 6 October brief carried, so they read as a repeated block rather than a fresh 9 October quote and are not treated as current on the snapshot above.
Kenya Forex
Figures as at · Central Bank of Kenya mean rates, 9 October 2026, as reported in this brief
The shilling weakened slightly against a resilient dollar, with the dollar index above 102. The Central Bank mean rates below are quoted to four decimals in the source; the snapshot above rounds them to the two decimals the cards use.
- USD/KES: KSh 129.9135, weaker by 0.12% on the week.
- GBP/KES: KSh 172.0435, weaker on aggressive offshore corporate dollar demand.
- EUR/KES: KSh 145.9235.
- East African crosses: KES/UGX at 27.57, KES/TZS at 19.27 and KES/RWF at 11.15 — units of the neighbouring currency per Kenyan shilling.
Kenya Corporate News
Figures as at · As reported in this brief
State interventions
- Kenya Airways: On Friday 9 October the Cabinet approved $350 million, about KSh 45.4 billion, in shareholder financing. It will be disbursed in tranches to cover urgent operating obligations, fund long-term aircraft maintenance and return grounded commercial planes to service.
- State appointments: A Kenya Gazette notice on 9 October carried a wave of appointments across state corporations and regulatory agencies, including Job Chirchir reappointed to chair the Water Services Regulatory Board.
Banking and credit risk
- Sovereign concentration: Banks’ cumulative holdings of government Treasury bills and bonds have reached KSh 2.53 trillion, drawing heightened scrutiny from Moody’s and Fitch. Analysts warn the exposure anchors bank balance sheets directly to sovereign risk.
- Deficit headwinds: The National Treasury updated its projections on 9 October, estimating the budget deficit will widen to 5.9% of GDP and raising crowd-out risk for private borrowers.
- Middle East Bank: Regulatory filings on 11 October showed former Principal Secretary Esther Koimett reversed an earlier attempt to hold her 18.24% stake through a nominee vehicle, increasing her direct holding amid broader ownership changes at the small-tier lender.
Retail and manufacturing
- Walton Hi-Tech: Announced on Sunday 11 October, the global electronics manufacturer signed a memorandum of understanding with Nairobi-based North Light Holdings, establishing a channel to sell, market and supply its electrical products and consumer electronics across Kenya.
Real Estate
Figures as at · As reported in this brief
International Housing Solutions Kenya broke ground on Muzi Enzi, a Sh1.8 billion rental project inside Tatu City. It will add 406 affordable green apartments aimed at entry and mid-level corporate workers in Kiambu County.
Quarter-on-quarter property metrics, Nairobi metropolitan area
| Segment | Median sale asking price | Median monthly rent | Land prices, year on year |
|---|---|---|---|
| Nairobi suburbs | KSh 12.9 million (apartments) | KSh 140,000 | +5.0% in prime nodes such as Karen and Lavington |
| Satellite towns | KSh 15.0–22.0 million (Kiambu) | KSh 35,000–60,000 | +15.6% in rapid expansion nodes such as Ruiru |
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.91
Mean rate 129.9135; weaker by 0.12% on the week.
As at
Central Bank of Kenya mean rate, as reported in this briefGBP / KES
172.04
Mean rate 172.0435.
As at
Central Bank of Kenya mean rate, as reported in this briefEUR / KES
145.92
Mean rate 145.9235.
As at
Central Bank of Kenya mean rate, as reported in this brief
Equities
NSE All-Share
244.93
−0.17%, down 0.41 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,315.49
−0.18%, down 7.77 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,964.04
−0.05%, down 3.34 points
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 329.88 million
Across 8.51 million shares.
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KSh 4.110 trillion
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
Held on 7 October for a fourth consecutive meeting.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.59%
+28 basis points on the day
As at
As reported in this brief
At a glance
- 1The Cabinet approved $350 million — about KSh 45.4 billion — in shareholder financing for Kenya Airways, to be released in tranches for operating obligations, aircraft maintenance and returning grounded planes to service.
- 2Kenya’s benchmark 10-year climbed 28 basis points to 12.59% on frontier market spillovers, while secondary market turnover in government securities fell 40.8% to KSh 53.8 billion from KSh 90.9 billion the week before.
- 3Banks’ holdings of Treasury bills and bonds have reached KSh 2.53 trillion, drawing scrutiny from Moody’s and Fitch, as the Treasury raised its budget deficit projection to 5.9% of GDP.
Sources
- Serrari Group desk compilation, 12 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data