
9 October 2026
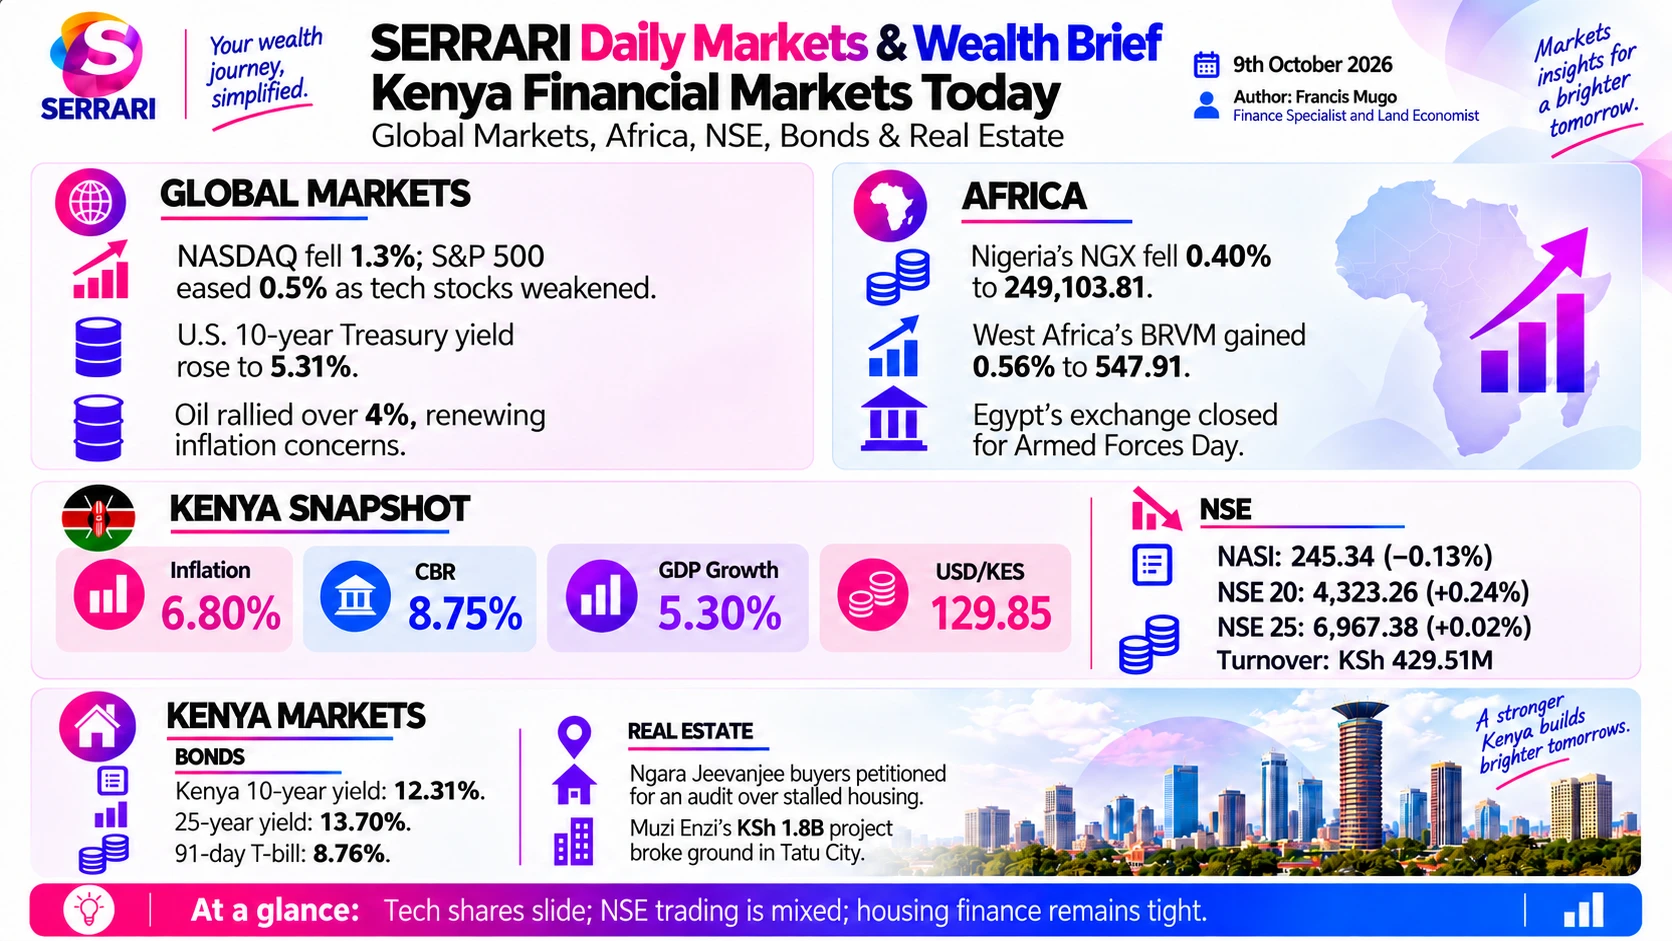
Oil rallied more than 4% and the Nasdaq fell 1.3% as the artificial intelligence trade stumbled, pushing the US 10-year Treasury yield to 5.31%. In Nairobi the exchange was mixed — the NASI eased 0.13% to 245.34 while the NSE 20 gained 0.24% — on turnover of KSh 429.51 million.

Global Markets
Figures as at · Closing levels for Thursday 8 October 2026, as reported in this brief
The Nasdaq led Wall Street lower as the artificial intelligence trade stumbled, while the Dow edged higher after a session of fluctuation. European shares fell broadly on a banking sell-off and French fiscal worries, and Asia declined on inflation fears stoked by high oil.
United States
- S&P 500: Fell 36.41 points, or 0.5%, to close at 7,765.36.
- Nasdaq Composite: Dropped 345.35 points, or 1.3%, to 27,193.34.
- Dow Jones Industrial Average: Rose 51.77 points, or 0.1%, to 51,231.64.
- Russell 2000: Inched up 0.92 points, under 0.1%, to 2,794.13.
Europe
- Stoxx Europe 600: Fell 0.75% to 624.24, with banking touching a three-month low.
- Germany (DAX): Dropped 1.18%.
- France (CAC 40): Declined 0.51% amid persistent concern over the fiscal outlook.
- United Kingdom (FTSE 100): Slipped 0.16%.
- Switzerland (SMI): Fell 1.24%.
Asia-Pacific
- Japan (Nikkei 225): Dropped 991.68 points, or 1.42%, to 69,042.11.
- Hong Kong (Hang Seng): Fell 344.71 points, or 1.43%, to 23,785.79.
- China (Shanghai Composite): Slipped 0.79% to 3,811.90 as investors returned from the Golden Week holiday.
- South Korea (KOSPI): Declined sharply by 2.6%. Samsung Electronics fell despite record profits, having missed consensus expectations.
- Australia (S&P/ASX 200): Dropped 0.8% to 8,665.
Forex
- EUR/USD: Near multi-month lows at 1.1160–1.1245 on fiscal and political uncertainty in France.
- GBP/USD: Under steady selling pressure, testing 1.3200 against a stronger dollar.
- USD/CAD: The dollar extended a five-week rally against the Canadian dollar, despite rising oil.
- EUR/GBP: Range-bound at 0.8450–0.8510 as both European currencies struggled against the dollar.
- USD/CHF and EUR/CHF: The franc weakened slightly against the dollar near 0.8735, while the euro slid to historical support near 0.9780 against it.
- USD/JPY: The yen weakened past major technical ceilings to around 157.81, cushioned only partly by a current account surplus of ¥4.062 trillion. GBP/JPY hovered near 208.89.
- USD/CNH and AUD/USD: The offshore yuan weakened to about 7.1450 as markets reopened after Golden Week, and the Australian dollar dropped toward 0.6720 on regional risk-off sentiment.
Global Yields
Figures as at · Yields for 8 October 2026, as reported in this brief
United States
- The curve: Borrowing costs hovered just shy of the 24-year highs set mid-week, and the curve flattened slightly after Federal Reserve Governor Christopher Waller said further hikes could still be needed to stamp out inflation.
- 2-year Treasury: Eased slightly to 4.77%.
- 10-year benchmark: Rose to 5.31%, after touching 5.36% earlier in the week.
- 30-year Treasury: Flat to slightly higher at 5.67% as investors prepared for upcoming long-term auctions.
Europe
- Germany: The 10-year Bund retreated slightly to 3.46%–3.49% but stayed near multi-decade highs.
- France: The 10-year OAT rose to 4.89% after spiking to 4.97% intraday — its highest borrowing cost since 2002. Euro zone finance ministers publicly urged France to pass its 2027 budget to calm markets.
- United Kingdom: The 10-year gilt held a high average of 5.46%.
Asia
- Japan 10-year: Stabilised just under 3.10% after the government offered a coupon above 3% to steady demand. Selling pressure followed the Bank of Japan’s autumn tightening and anxiety over Prime Minister Sanae Takaichi’s expansionary fiscal plans.
- Japan 30-year: Cleared an auction yield of 4.11% on newly issued ultra-long-term debt.
Commodities
Figures as at · Closing prices for 8 October 2026, as reported in this brief
Crude posted an aggressive daily rally of more than 4%, hitting multi-month highs and weighing heavily on global equity sentiment.
- Brent crude: Surged past $104.66–$108.33 a barrel, gaining roughly $3.59 in a single session.
- WTI crude: Jumped to settle between $91.49 and $91.75 a barrel.
- Natural gas: US Henry Hub slipped 1.1% to $3.17 per MMBtu.
- US retail gasoline: Averaged above $4.30 a gallon, up 46% from pre-war baseline levels.
- Gold and silver: Spot gold recovered 0.5% from nine-week lows to $4,117–$4,133 a troy ounce as investors sought an inflation hedge, though soaring bond yields capped gains. Silver dropped 1.9% to $58.98–$59.14.
- Platinum and palladium: Platinum was flat to slightly higher at $1,637.41–$1,651.00 an ounce, and palladium inched up 0.1% to $1,126.00.
- Agriculture: December corn declined to $4.99¾ a bushel and November soybeans fell 7.5 cents to $12.90, while cocoa edged up 0.6% to $5,617 a metric ton.
Africa
Figures as at · Closing levels for 8 October 2026, as reported in this brief
Benchmark 10-year government bond yields
| Country | Yield | Trend | Primary catalyst |
|---|---|---|---|
| Egypt | 23.370% | Edging higher | Global inflationary pressure and regional supply risk keep defensive yields elevated |
| Nigeria | 15.95% | Gradual downward shift | Responding to the central bank’s 350 basis point cut, to 23% |
| South Africa | 9.06% | Up 6 bps, over 50 bps in a month | Pushed past 9% by fuel price spikes, though a strong auction drew heavy coupon reinvestment |
Equities
- South Africa: The FTSE/JSE All Share closed around 106,767.48, down roughly 0.31% to 0.45% on the day, extending a difficult stretch after a major September rout.
- Nigeria: The NGX fell 992.94 points, or 0.40%, to settle at 249,103.81.
- West Africa: The BRVM composite advanced to 547.91, a daily gain of 0.56%.
- Egypt: The EGX suspended all trading on Thursday 8 October for Armed Forces Day and resumes on Sunday 11 October.
Currencies
- South African rand: USD/ZAR at 16.6650, up 0.33% on the day and weaker by 3.93% over the month as investors moved toward safer US assets amid energy price spikes.
- Kenyan shilling: USD/KES flat to stable at 129.85, range-bound after the CBK held the benchmark rate at 8.75%.
- Nigerian naira: ₦1,332.60 official and ₦1,383.00 parallel, resuming a minor depreciation after the central bank cut rates to 23%.
- Egyptian pound: USD/EGP at 52.4000, up 0.06% on the day and down roughly 2.36% on the month on heavy import bills, shielded somewhat by Egypt’s validation on the FTSE Russell Secondary Emerging Market index.
- Ugandan shilling: At record lows and depreciating, under extensive corporate dollar demand.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 8 October 2026, as reported in this brief
Indices
- NSE All-Share: Closed down 0.32 points, or 0.13%, at 245.34.
- NSE 20-Share: Gained 10.23 points, or 0.24%, to 4,323.26.
- NSE 25-Share: Rose 1.17 points, or 0.02%, to 6,967.38.
- NSE 10-Share: Declined 0.90 points, or 0.03%, to 2,737.01.
- Banking sector index: Advanced 0.33 points, or 0.11%, to 288.71.
- Turnover: Equity turnover reached KSh 429.51 million on a selective rotation that favoured larger banking counters while weighing on overvalued equities.
Movers
- Gainers: WPP Scangroup and CIC Insurance Group paced the advancers alongside NCBA Group, with Centum Investment and Car and General also positive.
- Losers: Eveready East Africa and Kenya Re-Insurance Corporation led the pullbacks, with KCB Group, Family Bank and Kenya Power finishing lower on profit-taking.
Bonds and Treasury bills
- 10-year benchmark: Eased 0.02 percentage points to 12.310%. The yield has contracted by 12 basis points over the past month as local pricing stabilises.
- 25-year bond: Held steady around 13.700%, with analysts projecting defensive long-term steepening into late 2026.
- Treasury bills: Short-term yields continue to track the policy rate tightly, averaging 8.7615% on the 91-day paper and 8.8744% on the 182-day and 364-day instruments.
Kenya Forex
Figures as at · Central Bank of Kenya indicative rates, 8 October 2026, as reported in this brief
The shilling stayed range-bound after the CBK held the benchmark rate at 8.75%. The gap between the official indicative rate and commercial bank retail quotes is wide enough to matter for anyone changing money.
- East African crosses: The brief quotes KES/UGX at 31.16, KES/TZS at 20.27 and KES/RWF at 11.37 — shillings of the neighbouring currency per Kenyan shilling.
Official CBK indicative rates against commercial bank retail spreads
| Pair | CBK indicative | Bank buy | Bank sell |
|---|---|---|---|
| USD / KES | 129.85 – 129.90 | 125.00 | 133.50 |
| GBP / KES | 171.62 | 167.10 | 175.40 |
| EUR / KES | 145.37 | 135.85 | 149.20 |
| ZAR / KES | 7.80 | 7.10 | 8.40 |
Real Estate
Figures as at · As reported in this brief
Benchmark property index trajectory
| Index | Performance | Stance | Primary catalyst |
|---|---|---|---|
| KNBS RPPI — houses | +8.5% year on year | Bullish | Strong family-buyer demand for standalone units |
| KNBS RPPI — apartments | −3.0% year on year | Bearish correction | Localised oversupply in dense urban areas |
| Hass suburb rental index | +1.4% | Strong demand | Average monthly suburb rents crossing KSh 200,000 |
| KBA-HPI overall | +0.39% | Consolidating | General pricing stabilising close to cycle baselines |
Stalled housing and tight finance
- Ngara Jeevanjee: Construction at the KSh 600 million Jeevanjee Affordable Housing Project in Ngara has been stalled since 2022. Frustrated buyers filed a formal petition with the Nairobi City County Assembly demanding a forensic audit of the developer.
- Bank finance: At the groundbreaking of the KSh 1.8 billion Muzi Enzi housing project in Tatu City, developers warned that expensive commercial bank loans are squeezing housing. Average lending rates sit at 14.34% and private credit growth in real estate has dropped 2.4%, making patient-capital rental projects hard to fund.
Tax enforcement and land titling
- eRITS becomes mandatory: The Kenya Revenue Authority finalised enforcement rules for its Electronic Rental Income Tax System. Landlords must submit real-time returns by the 20th of every month, and the authority is targeting KSh 80 billion a year from the sector.
- Taita Taveta: The Ministry of Lands issued 7,690 secure title deeds to 31,318 residents across Voi, Taveta and Mwatate, resolving tenure disputes and unlocking land values.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.85
Indicative range 129.85–129.90.
As at
Central Bank of Kenya indicative rate, as reported in this briefGBP / KES
171.62
As at
Central Bank of Kenya indicative rate, as reported in this briefEUR / KES
145.37
As at
Central Bank of Kenya indicative rate, as reported in this briefZAR / KES
7.80
As at
Central Bank of Kenya indicative rate, as reported in this brief
Equities
NSE All-Share
245.34
−0.13%, down 0.32 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,323.26
+0.24%, up 10.23 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,967.38
+0.02%, up 1.17 points
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 429.51 million
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
Held on 7 October for a fourth consecutive meeting.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.31%
Down 0.02 points on the day and 12 basis points over the month.
As at
As reported in this briefKenya 25-year bond
13.70%
As at
As reported in this brief91-day Treasury bill
8.7615%
The artwork rounds this to 8.76%.
As at
As reported in this brief182 and 364-day Treasury bills
8.8744%
As at
As reported in this brief
At a glance
- 1Crude rallied more than 4% in a single session — Brent past $104.66–$108.33 and WTI to $91.49–$91.75 — reviving inflation fears and dragging equities down from Wall Street to Asia.
- 2Kenya’s bond market held steady against the global sell-off. The 10-year eased to 12.310%, down 12 basis points over the month, and the 91-day Treasury bill sat at 8.7615%, tracking a Central Bank Rate held at 8.75%.
- 3Housing finance stayed tight, with bank lending averaging 14.34% and private credit growth in real estate down 2.4%, while KNBS data split the market: houses up 8.5% year on year, apartments down 3.0%.
Sources
- Serrari Group desk compilation, 9 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data