
8 October 2026
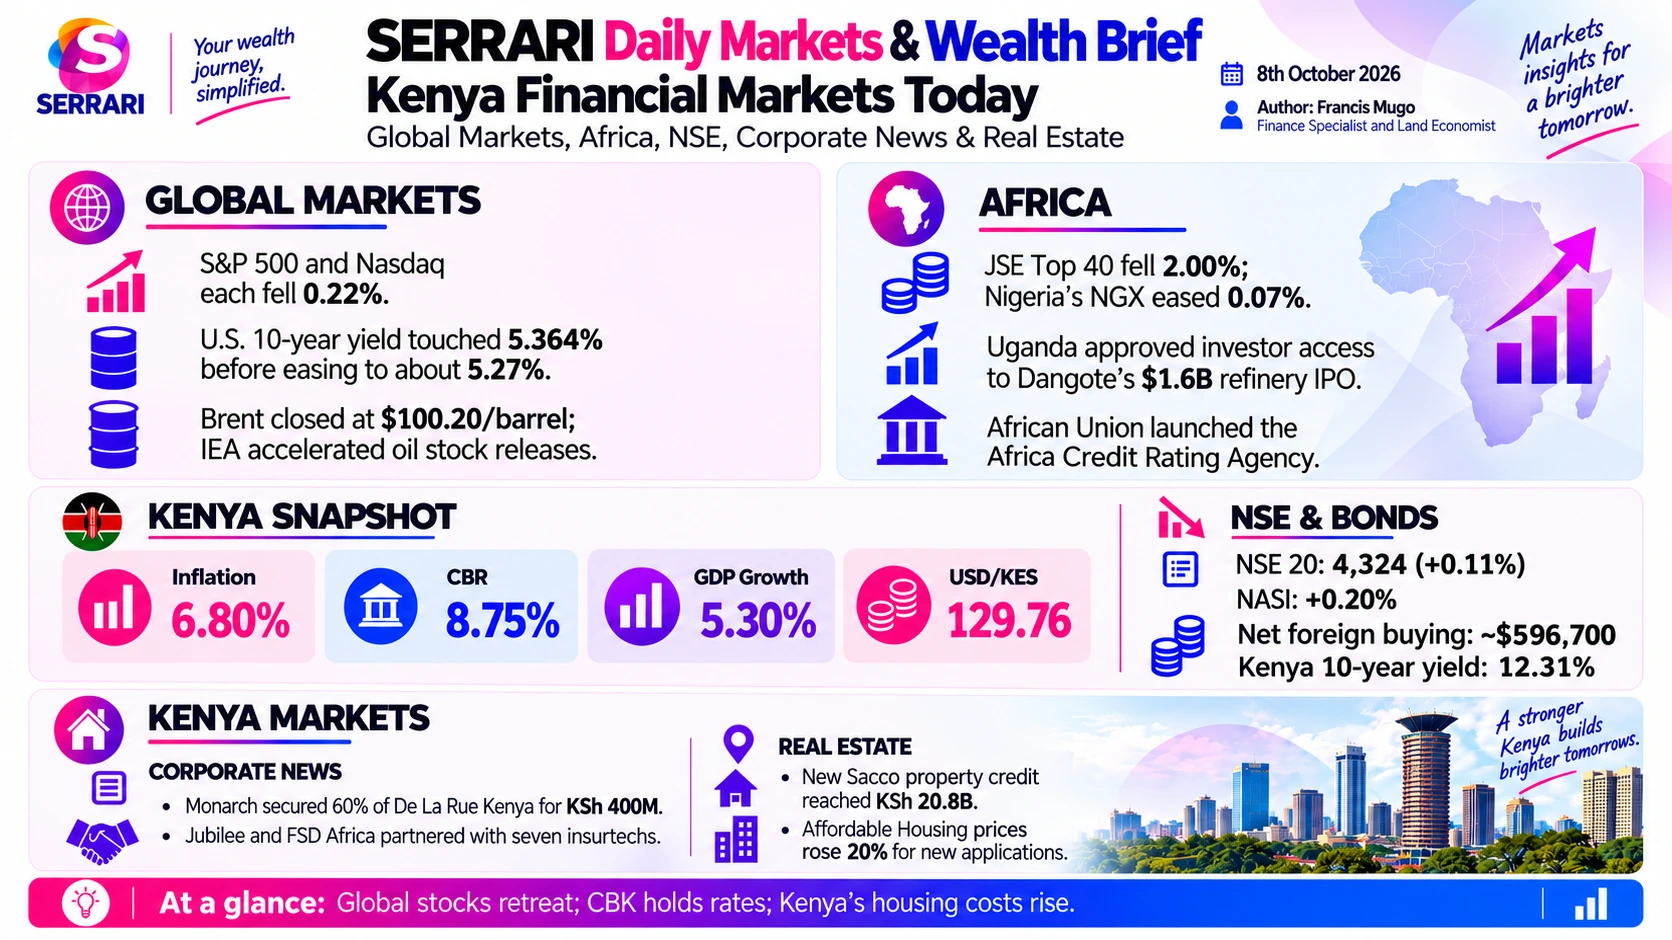
The Central Bank of Kenya held its benchmark rate at 8.75% for a fourth consecutive meeting and raised its 2026 growth forecast to 5.0%, with September inflation at 6.8%. A global bond sell-off drove the US 30-year yield to a 24-year high of 5.732% and left Kenya’s 10-year at 12.31%.

Global Markets
Figures as at · Closing levels for Wednesday 7 October 2026, as reported in this brief
Global stocks and the euro pulled back as crude hovered near $100 a barrel and long-dated borrowing costs reached levels not seen in more than two decades. Wall Street broke a short winning streak the day after the S&P 500 and Nasdaq closed at records.
United States
- S&P 500: Dropped 0.22% to close at 7,801.77.
- Nasdaq Composite: Slipped 0.22% to finish at 27,538.69.
- Dow Jones Industrial Average: Fell 0.66%, or 341.41 points, to 51,179.87, led down by a 6% slump in Caterpillar.
- Russell 2000: The small-cap index underperformed heavily, shedding 1.23% to 2,795.58.
Europe
- STOXX Europe 600: Tumbled 1.0%, with banks hit hardest at −3.3%, as the region snapped a three-session run.
- DAX: The sharpest correction among the major European indices, closing down 1.4% at 25,104.36.
- FTSE 100: Dropped 0.75%, dragged by a sell-off in commodity and mining names.
- CAC 40: Shed 0.25% as the spread between French and German bonds widened on fiscal sustainability worries.
Asia-Pacific
- Nikkei 225: Dropped 0.90% to 70,035.71, retreating from its recent push above 70,000.
- Hang Seng: Slipped 0.60% to close at 24,130.50.
- Kospi: Plunged 1.20% to 6,858.41, pressured by tech and semiconductor drawdowns.
- Nifty 50: Slipped marginally to 22,603.05 as India joined the global tightening wave.
- Shanghai Composite: Closed for a national holiday on 7 October.
Forex
- Dollar index: Advanced 0.41% to 102.33, boosted by multi-decade US bond yields.
- EUR/USD: Slumped 0.65% to 1.1185, hitting 17-month lows intraday on French budget deficits.
- GBP/USD: Held steady near 1.3215, supported by domestic wage growth expectations.
- USD/JPY: Hovered around 158.15, capped by Japan’s strong current account surplus. Views on the timing of a Bank of Japan hike remain divided.
- USD/CAD: Eased slightly to 1.4210, supported by volatile Brent crude.
- AUD/USD: Flat at 0.6960, with traders shrugging off the risk-off move in global equities.
Policy and trade
- Federal Reserve: Minutes read hawkish. The funds rate stands at 3.75%–4.00%, most officials see upside inflation risks, and the tone signalled no urgency for an October hike.
- IMF warning: Managing Director Kristalina Georgieva warned that major economies face "very tough choices" as soaring bond yields squeeze national budgets. The Fund also reached a staff-level agreement with Pakistan that could unlock $1.2 billion.
- EU and China: EU trade chief Maros Sefcovic arrived in Beijing for talks to defuse rising tensions, following a large trade deficit and pressure from France and Germany for protective instruments.
- Trade resilience: A DHL report found the artificial intelligence boom still driving global trade growth, outweighing the dampening effect of tariffs and geopolitical shocks.
Global Yields
Figures as at · Yields for 7 October 2026, as reported in this brief
Fixed income saw aggressive selling, pushing long-dated borrowing costs to levels last seen more than two decades ago before a late relief rally.
United States
- 10-year Treasury: Touched a fresh 24-year intraday high of 5.364% before cooling to finish near 5.27%, helped by strong demand at the afternoon auction.
- 30-year bond: Rocketed to a 24-year record high of 5.732% intraday before moderating.
- 2-year Treasury: Hovered stubbornly near 4.78%, sensitive to the Fed’s hawkish tone.
Europe
- United Kingdom: The 10-year gilt yield surged to 5.447% on persistent wage growth and sticky inflation. The 30-year reached a 28-year high.
- France: The 10-year OAT jumped to 4.876%, with the spread to German debt widening on budget deficit anxieties.
- Germany: The 10-year Bund climbed toward 2.90%, anchoring the region as investors braced for tighter eurozone liquidity.
Asia-Pacific
- Japan: The 10-year JGB crept toward 1.15% as markets priced in a hawkish shift and possible quantitative tightening ahead of the Bank of Japan’s next meeting.
- South Korea: The 10-year advanced to 3.82%, tracking the global sell-off as technology drawdowns hit domestic markets.
- Australia: The 10-year Commonwealth bond climbed past 4.65%.
Commodities
Figures as at · Closing prices for 7 October 2026, as reported in this brief
Prices were caught between Middle East risk premiums and a dollar backed by multi-decade sovereign yields. The IEA’s decision to accelerate emergency oil stock releases cooled an intraday spike across energy late in the session.
- Precious metals: Gold December futures closed at $4,140.00 an ounce, down 1.30%. Silver rose 0.25% to $60.18, platinum gained 2.10% to $1,665.00 and palladium added 1.60% to $1,142.86.
- Base metals: LME copper settled 0.45% lower at $10,210 a metric ton as high bond yields dented industrial sentiment, while aluminium edged up to $2,640 on data centre demand in Asia.
- Asian bitumen: Surged to multi-year regional highs in Singapore and South Korea on localised supply restrictions, opening rare arbitrage windows for Western cargoes.
- Oil policy: The IEA agreed to accelerate its emergency stockpile release, with about 100 million barrels left to deploy from a 400-million-barrel programme. The EIA raised its fourth-quarter Brent forecast to an average of $105 a barrel on Strait of Hormuz disruptions.
Energy benchmarks
| Benchmark | Region | Close | Change |
|---|---|---|---|
| Brent crude | International | $100.20 / bbl | −0.38% |
| WTI crude | United States | $89.04 / bbl | −1.28% |
| European LNG | Northwest Europe | $14.85 / MMBtu | +2.40% |
| Asian LNG | East Asia (JKM equivalent) | $13.90 / MMBtu | +1.10% |
Africa
Figures as at · Closing levels for 7 October 2026, as reported in this brief
African indices closed mostly lower on the global bond sell-off, rising oil and regional profit-taking, though several markets are holding strong year-to-date gains. The bigger news was a ratings upgrade and a new continental institution.
Major African indices
| Exchange | Close | Change | What moved it |
|---|---|---|---|
| South Africa — JSE Top 40 | 101,162.20 | −2.00% | Global bond sell-off and falling gold and PGM prices; petroleum imports weighed on the rand |
| Nigeria — NGX All-Share | 250,096.75 | −0.07% | A sixth straight losing session on risk-off sentiment, though up 60.72% year to date |
| Egypt — EGX 30 | 53,265.16 | −0.06% | Turnover of EGP 7.6 billion with local investors the only net buyers; up 27.3% year to date |
Sovereign yields
- Egypt: The 10-year government bond stayed elevated at 23.32%, rising about 35 basis points over the month as a World Bank report projected tighter domestic financial conditions.
- Nigeria: The 7-year government bond eased to 16.09%, tracking a 350 basis point policy rate cut by the Central Bank of Nigeria. The Debt Management Office opened its October savings bond at 13.07% for two years and 14.07% for three.
- Kenya: The 10-year government bond was stable at 12.31%, up 2 basis points on the day.
- South Africa: The 2035 benchmark weakened to 8.85%, up 4.5 basis points, under record local fuel price hikes and the global treasury sell-off. The Reserve Bank raised rates 25 basis points to 7.25% in late September.
Continental developments
- Moody’s upgrade: The agency raised its sovereign outlook for sub-Saharan African countries to Positive, citing fiscal reforms, commodity tailwinds and easier access to financing, and projecting 4.3% regional growth in 2026 and 2027. It warned that Kenya and Zambia will spend roughly 35% of government revenue on interest payments in 2027.
- Africa Credit Rating Agency: The African Union launched the continent’s first independent alternative to the three global agencies, aiming to ground credit assessments in African economic realities.
- Dangote refinery IPO: Uganda’s Capital Markets Authority approved local investor participation in the $1.6 billion offering, which is intended to double the refinery’s capacity to 1.4 million barrels a day.
- Corporate action: Sanlam progressed a R20.7 billion bid for full control of Santam, and Sibanye-Stillwater ended a month-long strike at its US operations with a three-year labour agreement. In Egypt, Orascom Construction and Abu Qir Fertilizers both rose 4.0%.
Currencies
- South African rand: Extended losses to R16.58 per dollar, hit both by capital flight into US assets and a domestic fuel price rise of over ZAR 3 a litre that inflated the petroleum import bill.
- Nigerian naira: Held steady at 1,485 per dollar. A World Bank Africa’s Pulse report released on 7 October noted that recent macroeconomic adjustments shielded the naira from the day’s sharpest losses.
- The wider move: Twelve of seventeen tracked African currencies depreciated against the dollar during the session, erasing the recovery recorded in August. Rising crude widened trade deficits across East and Southern Africa, forcing central banks to draw on dollar reserves.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 7 October 2026, as reported in this brief
Equities
- NSE 20 Share Index: Inched up to 4,324 points, a gain of 0.11%.
- NSE All-Share: Closed up 0.20%, with tracking indicators showing sustained net foreign buying of roughly $596,700.
- Movers: Heavyweight banking and infrastructure counters held stable, while agricultural stocks such as Eaagads eased 0.51%.
Bonds
- Local 10-year: Closed slightly higher at 12.31%, a daily rise of 0.02 percentage points.
- Eurobonds: The 2028 issue settled at 7.626%, the 2032 at 8.752% and the 2034 at 9.202%, with longer maturities feeling the pinch from rising US Treasury yields.
- The borrowing plan: The National Treasury is preparing an annual borrowing budget for a Sh105.8 billion issuance later this quarter.
- Reserves: Foreign exchange reserves stood at $15.3 billion, or 6.3 months of import cover, well above the statutory four-month minimum.
Kenya Forex
Figures as at · Official indicative rates for 7 October 2026, as reported in this brief
The shilling saw heightened intraday volatility, continuing the mild depreciation seen early in October. Commercial bank quotes moved between 1.2% and 2.9% over the week, while the official indicative benchmarks stayed relatively anchored.
- USD/KES: Exchanging at 129.76, under mild pressure from crude prices — Murban reached $95.41 a barrel — which threaten to widen Kenya’s import bill.
- GBP/KES: Trading around 174.60.
- EUR/KES: Exchanging at 151.23.
- Regional pairs: The brief also quotes UGX/KES at 27.57 and TZS/KES at 19.27.
Kenya Corporate News
Figures as at · As reported in this brief
The CBK holds the line
- Rate held at 8.75%: The Monetary Policy Committee held the benchmark steady for a fourth consecutive meeting. Governor Kamau Thugge said that despite September inflation inching up to 6.8%, the hold balances price stability against global energy risk from the Middle East.
- Growth forecast raised: The CBK lifted its 2026 GDP growth forecast to 5.0%, from 4.9%, on strong industrial and services expansion.
Manufacturing and utilities
- A KSh 390 billion EV project: The government signed a memorandum of understanding with Endelevu Enterprise Corporation to manufacture electric vehicles locally. The $3 billion initiative targets assembly plants producing 50,000 electric cars and 100,000 e-two-wheelers a year, with a solar-powered charging network.
- De La Rue Kenya: Mauritius-based Monarch Capital Limited secured a 60% controlling stake in De La Rue Kenya EPZ for Sh400 million. The Competition Authority of Kenya cleared the deal, leaving the National Treasury with 40%.
- Tata Chemicals: After a mining licence dispute and suspension, Managing Director Ramakrishnan Mukundan said the company will await a joint technical committee decision, stressing it retains its 30-year lease on the Lake Magadi ecosystem.
- Kenya Power: Launched seven "Golden Safety and Health Rules" during Customer Service Week, to standardise field operations for staff and contractors.
Infrastructure and insurance
- National Infrastructure Fund: Chief Executive James Mworia said the newly launched KSh 340 billion fund, about $2.62 billion, has begun buying domestic government bonds to free up commercial bank liquidity for private sector lending.
- Jubilee and FSD Africa: Jubilee Group partnered with FSD Africa and seven insurtech firms to build affordable, technology-driven policies for informal workers, low-income households and SMEs. Pilots roll out in November 2026.
Real Estate
Figures as at · As reported in this brief
Policy and credit
- Rates held: A fourth consecutive hold at 8.75% offers predictability for mortgage lenders and developers, against inflation that rose to 6.8% in September.
- Sacco credit surge: Land and housing have overtaken agriculture and education to dominate Sacco lending. New credit for property rose sharply to KSh 20.8 billion, supported by the Kenya Mortgage Refinance Company providing single-digit onward lending.
- Growth outlook: The World Bank revised Kenya’s 2026 growth outlook up to 4.6%, from 4.4%, pointing to resilience that should sustain demand in the mid-market residential segment.
Government housing
- Prices up: A price adjustment by the State Department for Housing took effect: Affordable Housing units rose 20% and Market Housing units 10% for all new applications, adding up to KSh 600,000 per unit for some buyers.
- A revenue mismatch: A Parliamentary Budget Office and National Treasury report found the Affordable Housing Board collected only KSh 212.3 million against a KSh 15.25 billion target — 1.4% of goal. Take-up of completed houses reached 94%, but heavy reliance on monthly tenant purchase schemes has trapped billions in cash and slowed the self-funding mechanism for later construction phases.
Courts and market trends
- Title cancellations upheld: Six investment vehicles lost a bid to overturn the cancellation of property titles across Nairobi, Kiambu and Machakos. The Environment and Land Court held that the properties, from villas in Karen to residential communities in Ruiru and Ruaka, remain in the custody of the State’s Official Receiver.
- Household sacrifices: A Habitat for Humanity survey found 89% of Kenyans cut back on basic needs over the past year to meet housing costs or fund building their own homes.
- Green and smart tech: Properties embedding PropTech, smart access control, energy efficiency and water recycling are achieving higher absorption rates.
- Satellite towns: Urban spillover continues to favour Ruiru, Syokimau, Juja and Kitengela on infrastructure expansion. At the coast, the Dongo Kundu Special Economic Zone has drawn interest from 94 major investors.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro dataForex reserves
$15.3 billion
6.3 months of import cover, against a four-month statutory minimum.
As at
Central Bank of Kenya, as reported in this brief
Foreign exchange
USD / KES
129.76
As at
Official indicative rate, as reported in this briefGBP / KES
174.60
As at
Official indicative rate, as reported in this briefEUR / KES
151.23
As at
Official indicative rate, as reported in this brief
Equities
NSE 20-Share
4,324
+0.11%
As at
Nairobi Securities Exchange, as reported in this briefNSE All-Share
+0.20%
The brief gives the day’s move, not a closing level.
As at
Nairobi Securities Exchange, as reported in this briefNet foreign buying
About $596,700
As at
Nairobi Securities Exchange tracking indicators, as reported in this brief
Rates
Central Bank Rate
8.75%
Held for a fourth consecutive meeting on 7 October.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.31%
+2 basis points on the day
As at
As reported in this briefKenya 2028 Eurobond
7.626%
As at
As reported in this briefKenya 2032 Eurobond
8.752%
As at
As reported in this briefKenya 2034 Eurobond
9.202%
As at
As reported in this brief
At a glance
- 1The CBK held the Central Bank Rate at 8.75% for a fourth consecutive meeting. Governor Kamau Thugge framed it as balancing price stability against Middle East energy risk, and the bank lifted its 2026 growth forecast to 5.0%.
- 2Moody’s raised its sovereign outlook for sub-Saharan Africa to Positive, projecting 4.3% regional growth in both 2026 and 2027 — while warning that Kenya and Zambia will spend roughly 35% of government revenue on interest payments in 2027.
- 3The global bond sell-off deepened: the US 30-year reached a 24-year high of 5.732% and the 10-year touched 5.364%. Kenya’s 10-year edged to 12.31% and the 2032 Eurobond sat at 8.752%, ahead of a planned Sh105.8 billion issuance this quarter.
Sources
- Serrari Group desk compilation, 8 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data