
7 October 2026
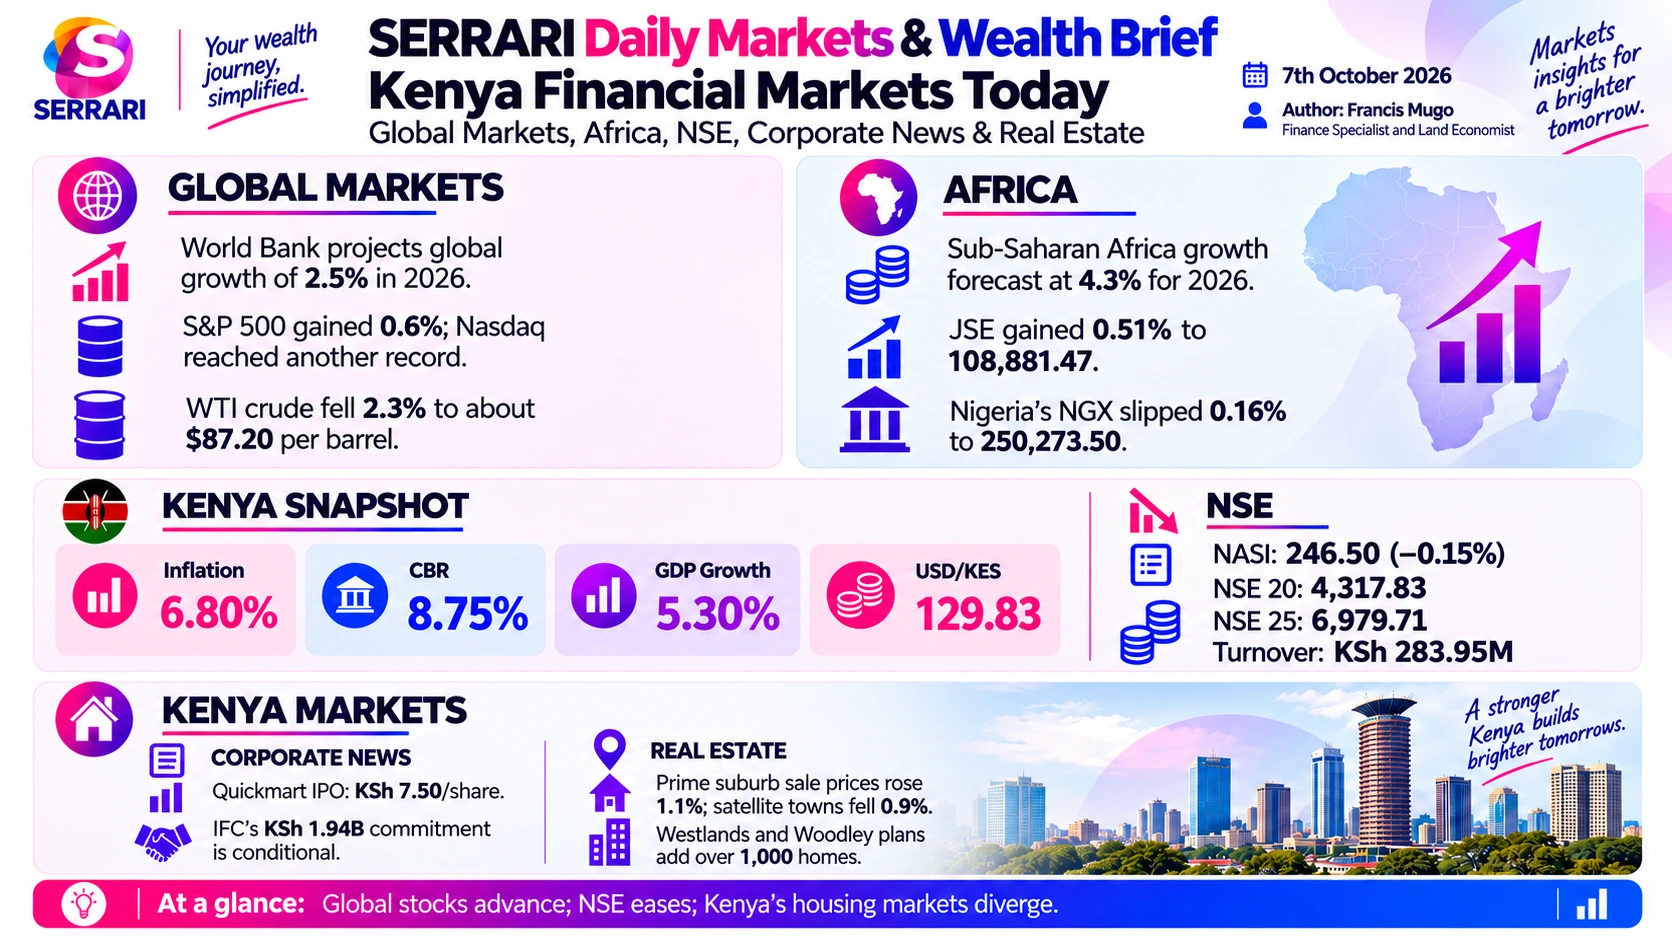
The World Bank raised Sub-Saharan Africa’s 2026 growth forecast to 4.3% while cutting its global projection to 2.5%, and the NSE drifted lower with the NASI down 0.15% to 246.50. The shilling closed at KSh 129.83 to the dollar as the CBK opened bidding on a KSh 50 billion Treasury bond auction.

Global Markets
Figures as at · Closing levels for Monday 6 October 2026, as reported in this brief
Global stocks scaled two-week highs as oil retreated and bond yields eased, with investors positioning for AI-powered corporate earnings. Underneath the rally, the World Bank marked down its global growth projection for the year.
Stocks
- Wall Street: The S&P 500 hit a fresh record, up 0.6%, and the Nasdaq notched another all-time high.
- Europe: The pan-European STOXX 600 climbed about 0.5%.
- Asia: Japan’s Nikkei 225 outperformed, rising 1.1% to finish above 70,600.
World Bank growth projections for 2026
- Global: Growth is projected to slow to 2.5% in 2026 from 2.9% the year before, held down by energy price shocks and regional spillovers from the Middle East conflict.
- South Asia: Remains the fastest-growing region at 6.9%, on internal consumer demand and resilient remittance inflows. Growth is expected to moderate to 6.7% in 2027 as climate stresses such as El Niño threaten agriculture.
- Europe and Central Asia: Soft at 2.2% across the region, though Uzbekistan’s 2026 forecast was upgraded heavily to 7.9% on deep infrastructure spending and real wage expansion.
- East Asia and Pacific: Projected to hit 4.5%, insulated by high-tech manufacturing exports matching global investment in AI infrastructure.
- Latin America and Caribbean: Forecast to moderate slightly to 2.2%, down from 2.4% in 2025.
Forex
- US dollar: Pulled back after recent highs, with the dollar index dropping around 0.25%.
- Euro: Stabilised and edged up to around 1.126 after hitting a 17-month low on French budget concerns.
- USD/CAD: Traded near 1.4257. The loonie was weighed down by a widening 133 basis point yield gap with the US and caution ahead of Canadian employment data.
- AUD/USD: Hovered near the bottom of its recent range, attempting to carve out support around 0.6950.
- Emerging markets: The South African rand stabilised at 16.56 per dollar, 21.93 per pound and 18.62 per euro, while the Thai baht hovered near 33.65 per dollar.
- Policy cues: Bank of Japan Governor Ueda hinted at potential rate hike signals, supporting the yen against a softening dollar.
Global Yields
Figures as at · Yields for 6 October 2026, as reported in this brief
- US Treasuries: Retreated from multi-decade peaks.
- 10-year yield: Hovered around 5.27% to 5.32%, still near 2002 highs.
- 2-year yield: Eased down close to 4.78%.
Commodities
Figures as at · Prices for 6 October 2026, as reported in this brief
- Crude oil: WTI dropped 2.3% toward $87.20, and Brent hovered near $97.80–$100.00 as supply anxiety eased.
- Gold: Tested support and moved around $4,120–$4,135 an ounce as yields eased.
- Grains and harvest delays: US corn and soybean futures pushed higher. A StoneX update noted that wet weather delayed the US harvest, leaving corn at 23% and soybeans at 25% complete.
- Black Sea shipping: Grain market anxieties spiked after reports that Russia targeted commercial vessels in the Black Sea, including the sinking of the Togo-flagged Alfa Watan and damage to the Palau-flagged Able.
- European natural gas: Extended its strong run of appreciation on localised winter restocking and geopolitical risk premiums.
- Precious and soft metals: Silver rose near $61.42 an ounce and platinum hovered around $1,173. In softs, sugar extended gains to retest its previous multi-year highs.
- Cocoa: Global benchmarks continued a 2.46% decline, trading down to $5,722.46 per metric ton.
Africa
Figures as at · Closing levels for 6 October 2026, as reported in this brief
The World Bank raised its 2026 growth forecast for Sub-Saharan Africa to 4.3% in the Africa Economic Update released on 6 October 2026 — a 0.3 percentage point increase on the 4.1% baseline projected in April, building on a closed estimate of 4.1% for 2025.
What is driving the upgrade
- Payoffs from reform: Improved macroeconomic management and structural adjustment are strengthening resilience in some of Africa’s biggest economies, including Nigeria, Angola, Ethiopia and Zambia.
- Private capital surge: Private capital mobilised by the World Bank Group for Africa rose nearly 150% to $22 billion in fiscal year 2026, pulling investment into energy, agribusiness and manufacturing.
- Domestic demand: Growth is increasingly supported by rebounding local consumer markets and stabilising trade dynamics.
The headwinds the report names
- Geopolitical and energy shocks: Supply chain disruption and elevated global energy prices tied to the war involving Iran weigh heavily on net oil-importing states.
- Sovereign debt distress: Debt loads have flattened to an average debt-to-GDP ratio of 57%, but roughly half the region’s countries remain in default or face severe debt-servicing strain.
- The growth-poverty gap: The World Bank warned that GDP acceleration is failing to lower poverty rates meaningfully. Regional per capita income growth is expected to reach only 1.8% this year, far too sluggish to offset population needs or close employment deficits.
Equities
- South Africa: The FTSE/JSE All-Share climbed 0.51%, up 554.69 points, to close at 108,881.47.
- Nigeria: The NGX All-Share retreated 0.16%, down 394.36 points, to finish at 250,273.50.
- Egypt: The EGX 30 fell 0.48%, down 255.27 points, to close at 53,298.14.
- Kenya: The NSE All-Share drifted lower by 0.15%, down 0.38 points, to settle at 246.50.
Sovereign bonds
- South Africa: Fixed-rate debt saw its strongest demand in four months. The Treasury’s weekly sale drew over R16.3 billion in bids against R2.55 billion on offer, even as the 10-year generic yield edged up to 8.99%.
- Nigeria: The central bank will run a ₦900 billion Treasury bill auction on 7 October, with ₦700 billion of it in 364-day paper. The 10-year government bond is stabilising around 15.95% after the policy rate was recalibrated down to 23%.
- Kenya: The CBK opened bidding on a KSh 50 billion multi-price Treasury bond auction offering two long-dated papers.
- Senegal: Targets a definitive agreement in principle with official lenders and bondholders by December 2026, covering an estimated $13 billion in unrecorded debt under the G20 Common Framework.
Currencies
- Ethiopian birr: The National Bank of Ethiopia allocated $840 million for foreign exchange auctions to tackle dollar scarcity, split into six fortnightly batches starting 13 October 2026.
- South African rand: Held firm at 16.63 against the dollar despite a stronger greenback, though falling platinum and gold prices continue to pinch the country’s terms of trade.
- Regional spots: The Kenyan shilling held a tight baseline near KSh 129 and the Nigerian naira stabilised around ₦1,332.90.
Commodities for the region
- Gold supply finance: UK-based off-take corporation SigraFi secured a $35 million credit facility through UAE and British investment groups to scale gold supply networks from artisanal mining cooperatives in the Democratic Republic of Congo.
- Energy investment: International legal experts at the Cape Town energy summit stressed that predictable regulatory frameworks remain paramount for closing multi-billion-dollar deals across South Africa’s upstream petroleum framework and the Orange Basin.
- South African petrol: Fuel prices were expected to rise sharply on 7 October, pushing retail petrol above R30 a litre for the first time.
- Precious metals: Spot gold softened to $4,140–$4,153 an ounce and platinum settled at $1,073 as high US yields dampened safe-haven demand.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 6 October 2026, as reported in this brief
Equities
- The indices: The NASI drifted 0.15% lower to close at 246.50. The NSE 20 settled 9.02 points down at 4,317.83 and the NSE 25 slipped 21.43 points to 6,979.71.
- Market size: Market capitalisation contracted slightly to KSh 4.136 trillion on equity turnover of KSh 283.95 million.
- Gainers: Kenya Airways Plc, Family Bank Limited and KenGen led the risers.
- Losers: Downside pressure came predominantly from Home Afrika Ltd, Kenya Power and Lighting Company and NCBA Group.
The KSh 50 billion primary auction
- SDB1/2011/030: A 30-year paper with 14.4 years remaining to maturity, carrying a fixed coupon of 12.00%.
- FXD1/2026/030: A fresh 30-year paper with 29.6 years remaining to maturity, carrying a fixed coupon of 12.50%.
- Bidding window: Closes on Wednesday 14 October 2026. The issue is aimed at budgetary support.
Liability management
- Switch auction: The CBK completed a liability management switch auction, accepting KSh 8.96 billion in bids. It moves 2027 and 2028 maturities into a 15-year bond maturing in May 2033 at a determined return rate of 12.61%.
Kenya Forex
Figures as at · Central Bank of Kenya official rate, 6 October 2026, as reported in this brief
- The shilling: Closed at KSh 129.83 against the US dollar, holding the multi-month trading base it has kept against the greenback.
- What is holding it: Easing domestic interest rate pressure is helping the shilling stay resilient against external headwinds, keeping fluctuation inside a narrow weekly high-to-low margin.
Kenya Commodities and Energy
Figures as at · As reported in this brief
Agriculture and softs
- Coffee: The Nairobi Coffee Exchange closed its 2025/2026 trading year with KSh 41 billion raised from the auction of 47 million kilograms. For the 2026/2027 cycle it has added Stanbic Bank as a second Direct Settlement System provider alongside Co-operative Bank, to speed up payments to farmers.
- Tea: Smallholder factories kept capturing robust demand at the weekly Mombasa auction. Mununga and Gathuthi averaged over KSh 433 per kilogram, well ahead of regional benchmarks.
- Maize: A dry June to September has triggered steep downgrades. Current projections put the potential fall in corn and maize yields at up to 36%, on rainfall deficits across the northern and western grain belts.
- Sugarcane: Deliveries surged 52.3%, pushing localised earnings to KSh 33 billion. Farmers are due structural rental bonuses from private operators this month under the progressive state lease models applied to sugar factories.
Energy and industrial inputs
- The import bill: The CBK warned that sticky fuel costs will inflate the total import bill by 8.1% to $25.62 billion this year, weighing on the current account balance.
- Pump prices: EPRA is holding retail prices fixed for the cycle ending 14 October, capping Super Petrol at KSh 214.03 and diesel at KSh 217.86 in Nairobi. Manufacturers warn that volatile crude pricing through shipping corridors remains an active risk to factory overheads.
- Steel: The Competition Tribunal quashed a KSh 62.7 million price-fixing penalty against Tononoka Rolling Mills, overturning part of an earlier anti-cartel ruling across the domestic structural steel sector.
Kenya Corporate News
Figures as at · As reported in this brief
IPOs and public offerings
- Quickmart: The retailer’s KSh 15 billion IPO is floating 2 billion ordinary shares — 50% of issued capital — at KSh 7.50 per share, ahead of a 12 November debut on the NSE. The International Finance Corporation has conditionally committed KSh 1.94 billion as a cornerstone investment.
- Dangote refinery: The Capital Markets Authority cleared retail distribution of the Dangote Petroleum Refinery IPO. Kenyan investors can buy at KSh 49 through Global Depositary Receipts on the NSE before the offer closes on 13 October.
Mergers, acquisitions and ownership
- De La Rue: Thomas De La Rue AG transferred its 60% controlling stake in De La Rue Kenya EPZ to Mauritius-based Monarch Capital Limited for KSh 400 million. The Competition Authority of Kenya cleared the transaction, which leaves the National Treasury with the remaining 40%.
- ICEA Lion: The Ndegwa family’s asset vehicle concluded a KSh 8.5 billion transaction to buy back a 24.1% minority stake in ICEA Lion Insurance from private equity firm LeapFrog Investments.
- East African Cables: The Competition Authority approved the acquisition of the company out of bankruptcy administration. It had been seized by Equity Bank in June 2025 after a prolonged loan default.
Technology, telecoms and disputes
- Airtel virtual cards: Airtel Mobile Commerce N.V. announced plans for a virtual card payment option in Kenya, designed to compete head-on with Safaricom’s M-Pesa GlobalPay.
- Starlink: The satellite internet provider entered a fourth consecutive month of frozen sales in Kenya, held back by network capacity limits as early subscriber growth ran into hardware constraints.
- Kenya Re: The High Court dismissed a petition by minority shareholders of Kenya Reinsurance Corporation, ruling that grievances over disputed board election outcomes at the June AGM belong under the Companies Act rather than constitutional petitions.
Real Estate
Figures as at · As reported in this brief
Suburbs rise as satellite towns soften
- Prime suburbs: HassConsult Property Index data shows average sale prices across Nairobi’s prime suburbs up 1.1% on healthy demand for standalone homes. Lavington led at 4.2%, followed by Spring Valley at 4.0% and Kilimani at 3.9%.
- Satellite towns: Average sale prices dropped 0.9% on sluggish sales and an ongoing oversupply of high-density apartment blocks.
- A rent milestone: With the national housing deficit above 2 million units, suburban residential rents grew 1.4%, pushing average monthly rent in upscale suburbs above KSh 200,000 for the first time.
Pipeline and infrastructure
- High-rise pipeline: Environmental assessment notices revealed plans for large high-rise residential projects in Westlands and Woodley, set to add over 1,000 new units.
- Transport: Activity across the metropolitan area is being driven by the ongoing dualling of the Muthaiga–Kiambu Town road and feasibility designs for the proposed Thika–Nairobi Expressway.
Affordability and consumer strain
- Financing: High double-digit mortgage rates continue to restrict access for middle-class Kenyans, shifting focus toward micro-savings and gradual land-buying.
- Household budgets: A Habitat for Humanity report found that 89% of Kenyans cut back on basic needs over the past year to fund high housing costs or build their homes.
- Design: Developers are widely adopting open-plan layouts with integrated breakfast nooks to maximise small floor plans. Units without them are struggling to command premium pricing.
Commercial offices and planning
- Occupancy split: Grade A commercial office occupancy climbed to 84.9% on scarcity, while broader Grade B and C registers slipped to an average of 87.7%. Prime commercial yields are holding near 8.5%.
- Development control: Developers are adjusting to the newly enacted Nairobi City County Development Control Policy 2026, which matches proposed building density and height against localised sewer, water and road infrastructure capacity.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.83
As at
Central Bank of Kenya official rate
Equities
NSE All-Share
246.50
−0.15%, down 0.38 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,317.83
Down 9.02 points
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,979.71
Down 21.43 points
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 283.95 million
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KSh 4.136 trillion
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
The MPC reviews the rate on 7 October; this is the level going into that meeting.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this brief30-year bond coupon
12.50%
FXD1/2026/030, new issue. SDB1/2011/030 reopens at 12.00%.
As at
Central Bank of Kenya auction notice, as reported in this briefSwitch auction rate
12.61%
15-year bond maturing May 2033; KSh 8.96 billion accepted.
As at
Central Bank of Kenya liability management switch auction, as reported in this brief
At a glance
- 1The World Bank lifted its 2026 growth forecast for Sub-Saharan Africa to 4.3%, up 0.3 percentage points from April, but warned that regional per capita income growth of 1.8% is far too slow to lower poverty.
- 2The CBK opened bidding on a KSh 50 billion Treasury bond auction, reopening SDB1/2011/030 at a 12.00% coupon alongside a new 30-year FXD1/2026/030 at 12.50%. Bidding closes on 14 October.
- 3Quickmart’s KSh 15 billion IPO is running at KSh 7.50 a share with a conditional KSh 1.94 billion IFC cornerstone, while the CMA cleared retail access to the Dangote refinery IPO at KSh 49 through depositary receipts before it closes on 13 October.
Sources
- Serrari Group desk compilation, 7 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data