
6 October 2026
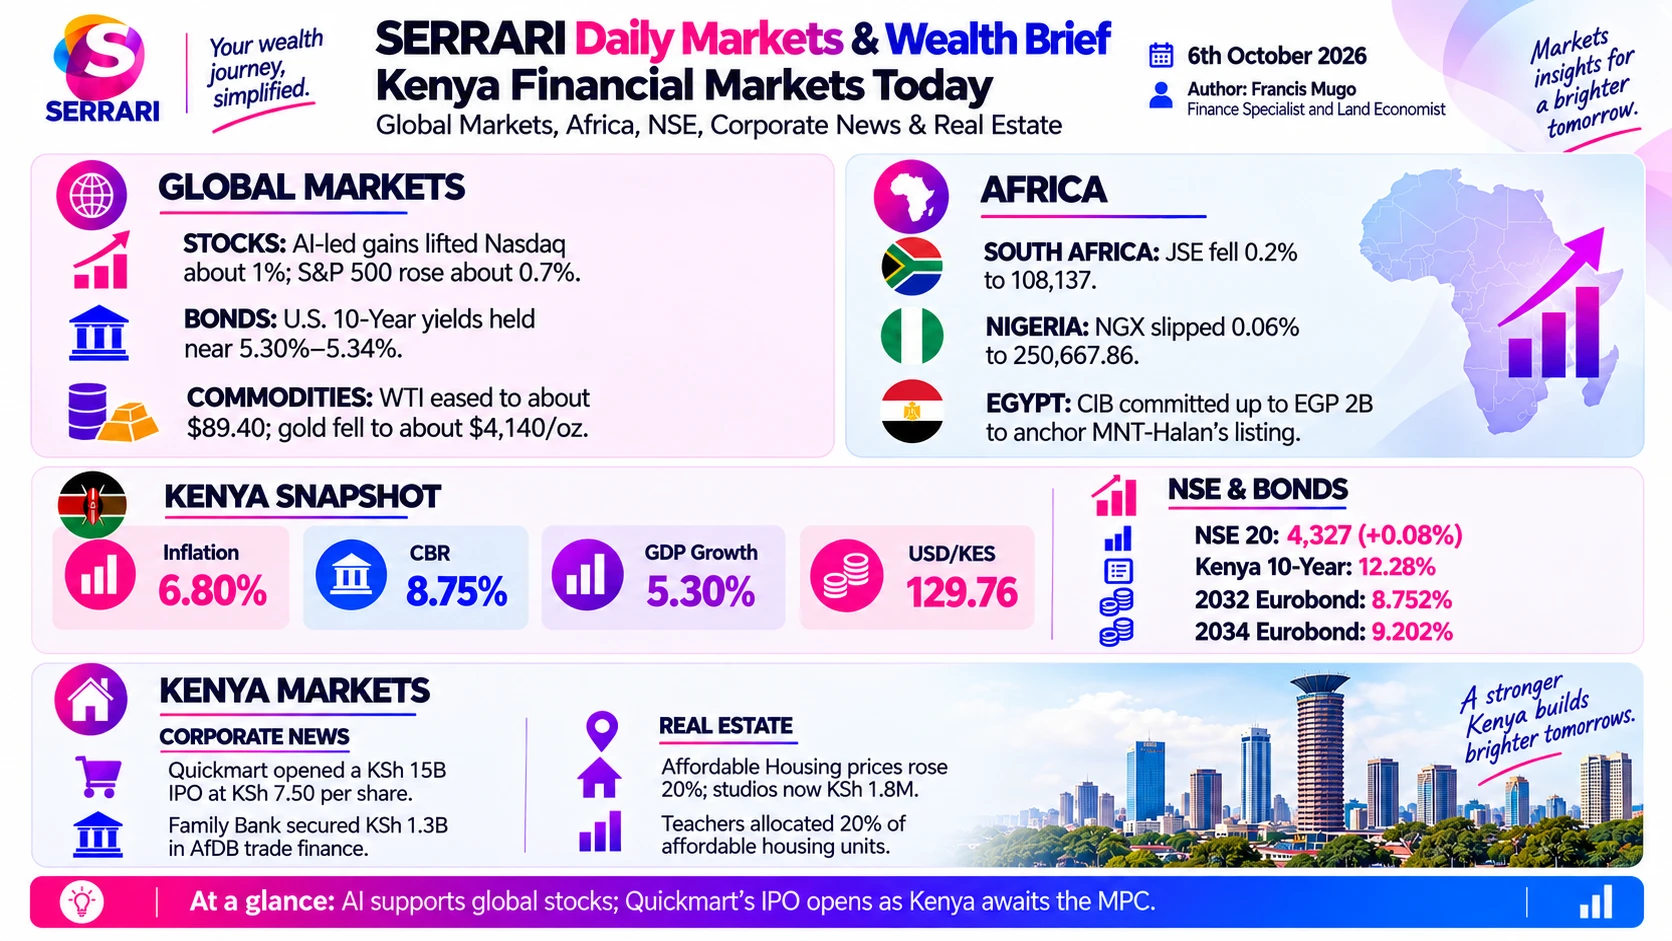
Quickmart opened a KSh 15 billion IPO at KSh 7.50 a share while Kenya’s 2032 Eurobond yield jumped 109 basis points to 8.752% in the global bond rout. AI-led gains lifted the Nasdaq to a fresh record even as the US 10-year held near 5.30%–5.34%.

Global Markets
Figures as at · Closing levels for Monday 5 October 2026, as reported in this brief
Global stocks were mixed to higher on tech-led Wall Street momentum and cooling US jobs data, while sovereign bond yields hovered near multi-year highs and the dollar strengthened. The session was a tug-of-war between an AI-led tech rally and building pressure in bond and currency markets.
Stocks
- Wall Street: The Nasdaq Composite gained about 1% to a fresh record and the S&P 500 rose about 0.7%, while the Dow was mixed near flat. Mega-cap tech — Nvidia, Meta and Microsoft — did the lifting.
- Asia-Pacific: Extended gains, led by Japan’s Nikkei 225, up roughly 2%–2.4% on chip and AI momentum.
- Europe: Mostly higher, though France’s CAC 40 hit a six-month low on lingering fiscal debt concerns.
- Brazil: The Bovespa surged in a relief rally after right-wing candidate Flavio Bolsonaro advanced to a presidential runoff with stronger-than-expected momentum.
Forex
- Dollar index: Pushed above 102.25–102.5, extending its run of weekly gains on elevated yields and European fiscal worries.
- EUR/USD: Dropped toward 1.1160, its weakest since May 2025, under pressure from French political and fiscal stress.
What drove the session
- The Fed path: Friday’s soft payrolls (+29,000 against +90,000 expected) kept working through markets. Swaps cut the implied odds of an October hike from over 50% to under 20%, which equity investors read as a narrow soft landing.
- Bear steepening: Short-term yields stabilised while long-term yields rose, with the 10-year touching 5.34%. Bond investors are demanding higher term premiums for heavy government borrowing, record corporate issuance such as Paramount Skydance’s $52 billion M&A debt package, and structural inflation risk.
- Eurozone stress: Sticky eurozone factory prices (+8.2%) and political disruption pushed French spreads wider against German Bunds, strengthening the dollar and dragging the euro to its weakest against the dollar since May 2025.
- Narrow AI leadership: Heavy AI infrastructure spending insulated mega-cap tech from multi-year-high borrowing costs. The Nasdaq’s record came on narrow breadth.
- Energy relief: Crude exports through the Strait of Hormuz recovered to roughly 80% of pre-war levels, and strategic emergency releases helped. Freight and infrastructure damage still keep delivered fuel expensive.
Global Yields
Figures as at · Yields for 5 October 2026, as reported in this brief
- US Treasuries: Held near multi-year highs, with the 10-year at about 5.30%–5.34% and the 30-year near 5.66%–5.70%.
- Japan: The 30-year JGB yield hit a record high despite the equity rally, a sign of global pressure from fiscal risk and inflation premiums.
Commodities
Figures as at · Prices for 5 October 2026, as reported in this brief
- Crude oil: Relented slightly. WTI dropped about 2% to roughly $89.40 a barrel and Brent traded softer at around $101.70–$102.10.
- Gold: Slumped roughly 3.4% to about $4,140 an ounce as the stronger dollar and high Treasury yields overwhelmed safe-haven demand.
The Week Ahead
Economic calendar, as published in this brief
This week’s calendar carries monetary policy clues and key data on trade, labour and consumer health. Times are US Eastern.
Global releases
| Date | Region | Release | Why it matters |
|---|---|---|---|
| Tue 6 Oct | Eurozone | Retail sales (Aug) | Strength of private consumption as the economy cools |
| Tue 6 Oct | Canada | Merchandise trade balance (Aug) | Cross-border trade dynamics with the US |
| Wed 7 Oct | Japan | Leading indicators and current account | Manufacturing and financial health under higher bond yields |
| Fri 9 Oct | Canada | Employment report (Sep) | Labour market health alongside global job trends |
United States
- Tue 6 Oct, 8:30 AM: International trade in goods and services — context on the widening trade deficit’s drag on Q2 growth.
- Wed 7 Oct, 2:00 PM: FOMC minutes from September — the week’s main event. Investors will look for the debate behind the 25 basis point hike to 3.75%–4.00% and for clues on the path ahead.
- Wed 7 Oct, 3:00 PM: Consumer credit — how resilient borrowing is amid persistent inflation.
- Thu 8 Oct, 8:30 AM: Weekly jobless claims — closely watched after last week’s 29,000 payrolls print.
- Fri 9 Oct, 10:00 AM: University of Michigan consumer sentiment (preliminary) — household views and longer-term inflation expectations.
Africa
Figures as at · Closing levels for 5 October 2026, as reported in this brief
African markets started the week under pressure from global risk-off sentiment. The stronger dollar battered regional currencies, and the Middle East energy shock forced historic fuel price adjustments across the continent.
Equities
- South Africa: The JSE All-Share slid 0.2% to 108,137 as macroeconomic friction and the global bond sell-off weighed on risk appetite.
- Nigeria: The NGX All-Share slipped 0.06% to 250,667.86. Profit-taking in Nestlé Nigeria (-5.2%) and insurance counters outweighed modest banking gains (+0.4%). Dangote Cement pitched London investors on a planned $1 billion London Stock Exchange listing.
- Egypt: The EGX30 fell 0.7% on low turnover of EGP 9.5 billion, though it remains up 28% year to date. Commercial International Bank (CIB) committed up to EGP 2 billion to anchor the upcoming listing of fintech MNT-Halan.
- Kenya: The NSE defied the regional downturn, extending its run as one of Africa’s top-performing bourses into October on banking resilience.
South Africa: PMI and fuel
- PMI: The private sector contracted at its fastest pace since December, throttled by supply bottlenecks and fuel costs.
- Fuel price: Petrol rose 12% to over R30 a litre for the first time, driven by the global oil shock.
Currencies
- South African rand: Fell toward R16.68 per dollar, a fifth consecutive weekly decline. Offshore investors have sold a net R12.7 billion of domestic bonds since late September, leaving the rand exposed to a break toward R17.00.
- Nigerian naira: 1,365 per dollar and 1,850 per pound in the converging official and parallel markets.
- Kenyan shilling: Slipped to KSh 129.76 per dollar as importer demand pushed it toward the KSh 130 mark.
Commodities for the region
- Brent: Around $102.82 a barrel. Crude has cooled from its peak, but freight rates into African ports keep import costs high.
- Precious metals: Gold at $4,157 an ounce and platinum at $1,722, with higher Treasury yields drawing safe-haven flows away.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for 5 October 2026, as reported in this brief
Equities
- Quickmart IPO: Quickmart Supermarket’s IPO opened for public subscription at 9:00 AM on Monday. The offer runs to 30 October 2026, with trading on the NSE scheduled to start on 12 November.
- NSE 20 Share Index: Gained 0.08% to 4,327 points. Activity across the exchange slowed compared with recent weeks.
- Gainers: Nation Media Group, Flame Tree Group, Kenya Re (lifted by its new foundation), KenGen and Co-operative Bank.
- Losers: Kenya Airways, Family Bank, Carbacid Investments and Eveready East Africa.
Bonds
- Eurobond sell-off: The global debt rout, set off by the US 10-year reaching 5.34%, spilled into Kenya’s dollar bonds. The 2032 Eurobond yield surged 109 basis points to 8.752% and the 2034 issue climbed to 9.202%.
- The planned issue: Higher risk premiums threaten to raise the cost of Kenya’s planned $815 million international bond later this quarter.
- Kenya 10-year: The local benchmark yielded 12.280%. The CBK opened secondary trading in the newly issued 15-year and 20-year infrastructure bonds.
Policy outlook
- The MPC: Ahead of Wednesday’s Monetary Policy Committee review, the Kenya Bankers Association formally urged the CBK to hold the Central Bank Rate at 8.75%, citing stable inflation and adequate forex buffers.
Kenya Forex
Figures as at · Central Bank of Kenya official rates, 5 October 2026, as reported in this brief
- Official CBK rates: KSh 129.76 per US dollar, KSh 171.76 per pound sterling and KSh 146.20 per euro.
- Shilling slippage: Back-to-back weekly declines on a dominant dollar have brought the shilling close to the KSh 130 mark.
- Agricultural exporters: High ocean freight insurance and logistics premiums kept squeezing margins for Mombasa coffee and tea blenders, though the softer shilling gave a mild cushion to hard-currency revenue.
Kenya Corporate News
Figures as at · As reported in this brief
Quickmart opens its IPO
- The offer: A KSh 15 billion IPO of 2 billion ordinary shares — a 50% stake — at KSh 7.50 per share, valuing Quickmart at KSh 30 billion.
- Timetable: Public subscription runs to 30 October 2026, with an NSE debut scheduled for 12 November.
Capital markets and regulation
- Dangote refinery access: The Capital Markets Authority approved a Global Depositary Receipt route submitted by Renaissance Capital, letting eligible Kenyan investors buy shares in the Dangote Petroleum Refinery & Petrochemicals IPO through a local cross-border structure.
- Sacco dividends: The regulator directed Saccos to restrict dividend payouts and provide for about KSh 7.67 billion tied up in the insolvent and liquidating Kuscco.
- Fraud reporting: The CBK now requires payment firms such as M-Pesa and Airtel Money to report every mobile-money theft and fraud incident immediately.
Banking and insurance
- I&M Bank: Abdi Mohamed took office as Chief Executive Officer of I&M Bank Kenya after CBK approval.
- Family Bank: Secured a KSh 1.3 billion trade finance facility from the African Development Bank to expand lending to SMEs.
- Mobile-number payments: Commercial banks are pushing customers to pay using mobile phone numbers instead of account numbers, sharpening competition with the telecom operators.
- Kenya Re Foundation: Seeded with KSh 78.47 million under Group Managing Director Dr Hillary Wachinga, the foundation will sponsor orphaned straight-A KCSE students to study at leading Ivy League universities from February 2027, and fund climate resilience work.
Real Estate
Figures as at · As reported in this brief
Government housing prices and allocation
- Affordable Housing up 20%: New prices took effect on Boma Yangu: studios rose by KSh 300,000 to KSh 1.8 million, one-bedroom units to KSh 2.4 million and two-bedroom units to KSh 3.6 million.
- Market Housing up 10%: Two- and three-bedroom units rose to KSh 3.96 million and KSh 5.28 million. The state said it has spent nearly all of the KSh 205.7 billion collected through the Housing Levy.
- 20% for teachers: At World Teachers’ Day celebrations in Kasarani on Monday, President William Ruto said the government has signed an MoU reserving 20% of affordable housing units for teachers, with financing matched to their salaries.
Regulation and market strain
- Firms struck off: A Gazette Notice from the Registrar of Companies dissolved 440 non-compliant companies. Construction and real estate was the hardest-hit sector, losing more than 80 firms.
- Investor confidence: Industry players said the private market must restore investor confidence to attract institutional financing. Developers are shifting toward middle-class housing while mortgage rates stay in double digits.
Nairobi high-rises and design trends
- New towers: Environmental assessment notices detailed a 30-storey, 697-unit residential tower in Parklands/Westlands by Stellar Bay Limited and a 19-storey mixed-use tower in Woodley.
- Open-plan premium: Agencies including Kingsville Real Estate report that apartments with open-plan kitchens and breakfast bars now sell faster and at a premium to walled-off kitchen layouts.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.76
As at
Central Bank of Kenya official rateGBP / KES
171.76
As at
Central Bank of Kenya official rateEUR / KES
146.20
As at
Central Bank of Kenya official rate
Equities
NSE 20-Share
4,327
+0.08%
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
The MPC meets on Wednesday 7 October.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.28%
As at
As reported in this briefKenya 2032 Eurobond
8.752%
+109 basis points
As at
As reported in this briefKenya 2034 Eurobond
9.202%
As at
As reported in this brief
At a glance
- 1Quickmart’s KSh 15 billion IPO opened on Monday: 2 billion shares, a 50% stake, at KSh 7.50 each, valuing the retailer at KSh 30 billion. Subscriptions close on 30 October and trading is due to start on 12 November.
- 2Kenya’s Eurobonds took the global bond rout. The 2032 yield jumped 109 basis points to 8.752% and the 2034 reached 9.202%, raising the cost of the planned $815 million issue later this quarter.
- 3The CMA approved a depositary-receipt route that lets eligible Kenyan investors buy into the Dangote refinery IPO, while the MPC meets on Wednesday with banks urging a hold at 8.75%.
Sources
- Serrari Group desk compilation, 6 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data