
5 October 2026
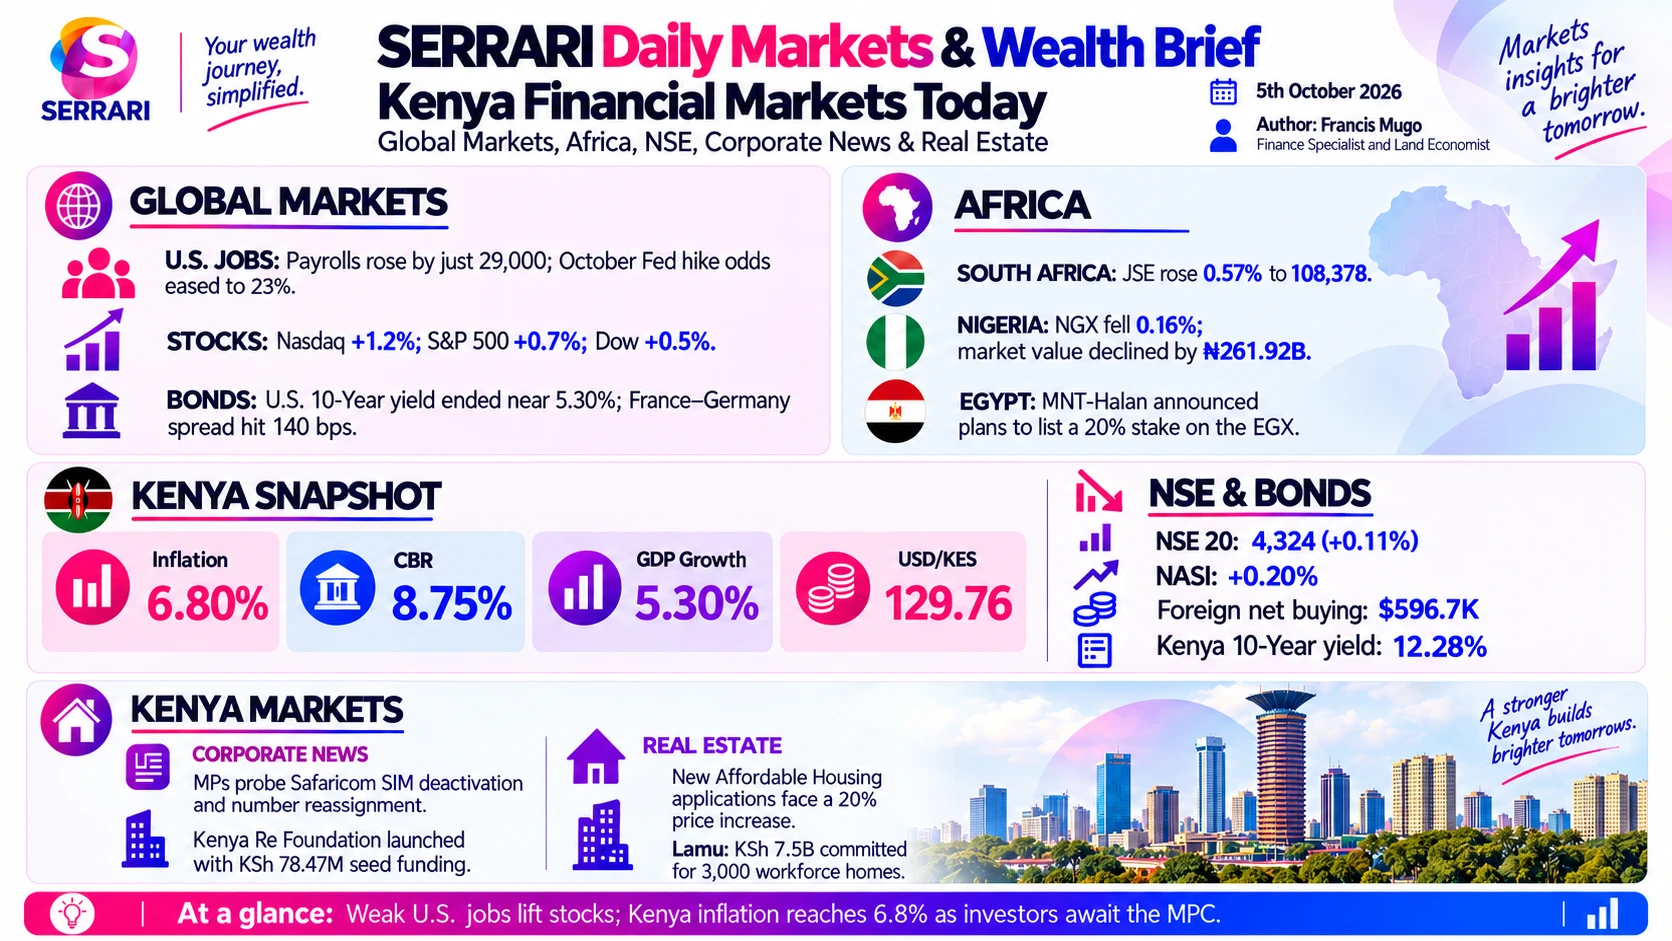
US payrolls rose by just 29,000 in September, cutting the odds of an October Fed hike to 23% and lifting the Nasdaq to a record intraday high. In Kenya, inflation reached 6.8% ahead of Wednesday’s MPC meeting, and new Boma Yangu applicants face Affordable Housing prices 20% higher.

Global Markets
Figures as at · Closing levels for Friday 2 October 2026, as reported in this brief
Global markets reacted sharply to a much weaker-than-expected US nonfarm payrolls report. The “bad news is good news” trade took centre stage, driving a rally in major equity markets as the data dampened expectations of an aggressive Federal Reserve rate hike at its late-October meeting.
Stocks
- Wall Street: Major indices closed higher on tech gains. The Nasdaq Composite surged 1.2% to a new intraday record, the S&P 500 advanced 0.7% and the Dow Jones Industrial Average closed 0.5% higher. Despite the Friday rally, the S&P 500 and the Dow both booked weekly losses.
- Europe: European indices firmed on Friday afternoon after steep declines earlier in the week on rising sovereign bond spreads and growing concern over France’s fiscal outlook.
- Asia: Mixed. Japan’s Nikkei 225 dropped 0.9% and Hong Kong’s Hang Seng tumbled 2.7% ahead of the US jobs print. Mainland Chinese markets were closed for a week-long public holiday.
Forex and crypto
- US dollar index: Fell 0.16% to close at 101.93 as traders cut bets on a Fed hike. The CME FedWatch probability of a late-October hike dropped to 23% from 64% a week earlier.
- Euro currency index: Declined sharply, falling 0.75% to close at 112.46.
- Crypto: The softer dollar and easing rate-hike pressure let Bitcoin and Ethereum move higher, closing the week on a positive note.
What drove the session
- September payrolls: The US economy added just 29,000 jobs against a consensus of roughly 90,000, and prior months were revised significantly lower. The cooler labour data dialled back fears of an aggressive Fed hike and took pressure off long-term yields.
- France’s debt strain: Paris presented plans to cut its deficit to 5.0% of GDP next year, but investors still demanded higher premiums. The France–Germany 10-year spread widened to 140 basis points, its highest since the 2012 eurozone crisis.
- Eurozone inflation: Flash inflation accelerated to 3.8%, a stagflationary headache for the ECB while regional growth stays sluggish.
- Middle East and the G7: Reports said the Pentagon was considering deploying a third aircraft carrier group and up to 10,000 additional troops to the region. In a virtual emergency meeting on Friday 2 October, G7 leaders committed to coordinated refinery maintenance schedules and temporary capacity increases to shield consumers from fuel price shocks.
- The AI capex shield: Data centre construction and corporate AI investment showed no sign of slowing. Nvidia reached a fresh intraday all-time high of $237.88, surpassing a $5.7 trillion market capitalisation.
Global Yields
Figures as at · Closing yields for 2 October 2026, as reported in this brief
- US Treasuries: Severe intraday volatility. The 10-year fell to a low of 5.16% straight after the jobs report, but buyers retreated late in the session and it finished around 5.30% — just below Thursday’s multi-decade high of 5.35%.
- Europe: Sovereign spreads stayed wide, with France’s risk premium hitting 140 basis points over German Bunds as safe-haven capital moved into Germany.
Commodities
Figures as at · Settlement prices for 2 October 2026, as reported in this brief
- Crude oil: Stabilised but ended lower on the day, with WTI near $91–$92 a barrel and Brent just under $100. Middle East risk set a floor, while record US commercial inventory builds and slower demand in China prompted minor profit-taking.
- Precious metals: Gold and silver rebounded on Friday morning as lower initial Treasury yields supported bullion. Gold traded around $4,180 an ounce but still finished the week roughly 2% lower.
Africa
Figures as at · Closing levels for 2 October 2026, as reported in this brief
Heavy capital outflows from emerging markets dominated the week as long-term US yields surged and the dollar strengthened. Friday’s weak US payrolls gave African assets an eleventh-hour cushion by stalling the sell-off.
Equities
- South Africa: The JSE All-Share climbed 0.57% to 108,378, a minor technical bounce after a 7.12% loss over the prior month.
- Nigeria: The NGX All-Share dropped 0.16% to 250,808.27, wiping ₦261.92 billion off market capitalisation. Losses in MTN Nigeria and GTCO led the decline in a week shortened by the 1 October Independence Day holiday.
- Egypt: Fintech group MNT-Halan announced plans for an IPO on the Egyptian Exchange selling a 20% stake — one of Egypt’s largest fintech listings to date.
Bonds and currencies
- Eurobonds: Rising long-term US yields forced investors to reassess risk premiums on African Eurobonds, keeping refinancing costs high for frontier issuers. South African local-currency yields also crept higher.
- South African rand: Logged a fourth consecutive weekly decline, down nearly 2% on the week, before recovering 0.2% on Friday afternoon to trade at R16.67 per dollar.
- Nigerian naira: Quoted on the parallel market at 1,375 per dollar, 1,814 per pound and 1,555 per euro to end the week.
Commodities for the region
- Oil exporters and importers: Brent just below $100 a barrel gave Nigeria and Angola vital foreign exchange inflows, while East African importers faced compounding fuel costs and import-driven inflation.
- Miners: The late-week rally in gold and silver gave mining operations in South Africa, Ghana and Tanzania a small cushion against the week’s equity sell-off.
Kenya: Inflation, NSE and Bonds
Figures as at · Nairobi Securities Exchange session data and Central Bank of Kenya weekly bulletin for 2 October 2026, as reported in this brief
September inflation was Friday’s defining domestic story. Headline inflation rose to 6.8% from 6.6% in August, moving closer to the CBK’s 7.5% upper target ceiling.
Inflation and the MPC
- Core inflation: Rose to 4.0% from 3.4%, driven by processed foods such as wheat and milk.
- The MPC: The Monetary Policy Committee meets on 7 October. The Kenya Bankers Association has publicly urged the CBK to hold the Central Bank Rate at 8.75% to protect the recovery in private-sector credit.
Equities
- NSE 20 Share Index: Advanced 0.11% to close at 4,324 points.
- NASI: Ticked up 0.20%, taking its year-to-date gain to 32.55%.
- Foreign activity: Foreign investors recorded net buying of $596,700.
- Top movers: Umeme (UMME) led gainers, up 8.71% to KSh 6.24. Express Kenya (XPRS) fell 7.12% to KSh 7.04.
Bonds and T-bills
- Treasury bond reopening: A reopening of the 15-year and 20-year bonds drew KSh 80.6 billion in bids against a KSh 50 billion target, a 161.1% subscription. Treasury bills were 170.4% subscribed.
- Kenya 10-year: Over-the-counter interbank quotes held the benchmark yield steady at 12.28%.
- Eurobonds: Kenya’s average Eurobond yield rose 22.28 basis points, with the 2028 maturity at 7.626%.
Kenya Forex and Commodities
Figures as at · Central Bank of Kenya official rates and weekly bulletin, 2 October 2026, as reported in this brief
Rates and reserves
- Official CBK rates: The US dollar at KSh 129.76, the euro at KSh 146.40 and the pound sterling at KSh 171.62. The shilling stayed resilient as the dollar softened after the US jobs data.
- Reserves: Usable foreign exchange reserves dipped to $14.93 billion, or 6.1 months of import cover, from $15.04 billion the week before.
Agricultural commodities
- Mombasa tea auction: Prices crept up on demand from Egypt and Pakistan, with high-grade black tea averaging around $2.25 to $2.30 a kilogram.
- Nairobi Coffee Exchange: Top-grade AA and AB Arabica held firmly above $280 per 50-kilogram bag, supported by tighter supply from South America.
- Horticulture: High freight and cold-chain energy costs squeezed margins, even as seasonal demand from Europe and the Middle East kept order volumes steady.
Food, metals and energy
- Maize: Wholesale prices in Eldoret and Kitale stayed soft on regional harvests, at KSh 3,200 to KSh 3,500 per 90-kilogram bag.
- Wheat and processed foods: Processed wheat and cooking oil costs advanced — the main driver of the rise in headline inflation to 6.8%.
- Gold: The post-payrolls rally pushed spot gold back toward $4,180 an ounce, lifting valuations for mining operators in western Kenya.
- Crude: As a net petroleum importer, Kenya stays exposed to Brent just under $100 a barrel, which continues to weigh on reserves.
Kenya Corporate News
Figures as at · As reported in this brief
Safaricom: parliamentary probe and emergency orders
- SIM card probe: MPs opened an investigation into Safaricom’s compliance with rules on SIM card deactivation and number reassignment, after subscriber complaints that numbers were recycled without adequate notice, complicating access to mobile money accounts.
- Early warning override: The Communications Authority ordered Safaricom, Airtel Kenya and Telkom Kenya to bypass subscribers’ “Do Not Disturb” settings for a national early warning simulation on 2 October, so El Niño preparedness alerts reach every active device.
Tech ecosystem
- Venture failures: A data breakdown of this year’s collapses in the Kenyan tech ecosystem highlighted Twiga Foods, which had raised $185.4 million, and KOKO Networks, at $100 million, alongside earlier closures such as Sendy and MarketForce.
Governance and foundations
- Kenya Re: Launched the Kenya Re Foundation with KSh 78.47 million in seed funding and a commitment to allocate 2% of annual profit after tax to it.
- Standard Group: Counter-protests took place at the media house’s Mombasa Road headquarters, where rights activists gathered to defend press freedom after demonstrators protested its political coverage.
Consumer petitions
- Lamu refinery stake: The Consumers Federation of Kenya (COFEK) petitioned against the government’s planned KSh 65 billion public investment in the Dangote East Africa oil refinery in Lamu, demanding full disclosure of the state’s commitments.
Real Estate
Figures as at · As reported in this brief
Boma Yangu raises Affordable Housing prices 20%
- New rates: From the 1 October deadline, new Affordable Housing applications cost 20% more: studios rose from KSh 1.5 million to KSh 1.8 million, one-bedroom units to KSh 2.4 million and two-bedroom units to KSh 3.6 million.
- Market Housing: Rose 10%, taking two- and three-bedroom units to KSh 3.96 million and KSh 5.28 million. Applications submitted before the deadline keep the old prices.
Coast land and the Lamu housing scheme
- Eviction ban: In Mombasa on 2 October, President William Ruto ordered that no resident be forcibly evicted from ancestral land over an unresolved title, and directed the Ministry of Lands to issue 200,000 new titles across the Coast within 90 days.
- Refinery housing: The state committed KSh 7.5 billion to build 3,000 housing units for the workforce at the Dangote refinery in Lamu.
Demolitions and auctions
- Nairobi West: The Water Tribunal issued emergency site-verification orders after demolitions reportedly continued in a Nairobi West estate despite a court injunction, leaving about 50 families facing displacement.
- Nyari auction: Phillips International Auctioneers listed a 1.06-acre Nyari estate belonging to Bishop David Kariuki Ngari (Gakuyo), tied to the Ekeza Sacco liquidation, for auction on 22 October 2026.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro dataForeign exchange reserves
$14.93bn
6.1 months of import cover
As at
Central Bank of Kenya, as reported in this brief
Foreign exchange
USD / KES
129.76
As at
Central Bank of Kenya official rateGBP / KES
171.62
As at
Central Bank of Kenya official rateEUR / KES
146.40
As at
Central Bank of Kenya official rate
Equities
NSE 20-Share
4,324
+0.11%
As at
Nairobi Securities Exchange, as reported in this briefNASI year to date
+32.55%
NASI +0.20% on the day
As at
Nairobi Securities Exchange, as reported in this briefForeign net buying
$596,700
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
The MPC meets on 7 October.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.28%
Unchanged
As at
Over-the-counter interbank quotes, as reported in this brief
At a glance
- 1A 29,000 payrolls print against roughly 90,000 expected cut October Fed hike odds from 64% to 23%. Bad news was good news: the Nasdaq hit a record intraday high and the 10-year briefly fell to 5.16%.
- 2Kenyan inflation rose to 6.8% as core jumped to 4.0% from 3.4% on wheat and milk. That sets up the 7 October MPC, where the Kenya Bankers Association wants the CBR held at 8.75%.
- 3Affordable Housing prices on Boma Yangu rose 20% for new applications from 1 October, taking a studio to KSh 1.8 million. Applications lodged before the deadline keep the old price.
Sources
- Serrari Group desk compilation, 5 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data