
29 October 2026
The Fed holds rates and US stocks edge higher, while the NSE All-Share closes at 237.80 on KSh 774.64 million turnover. Safaricom reports KSh 1.24 trillion in economic value, and ALP Industrial REIT declares a US$930,434 dividend.

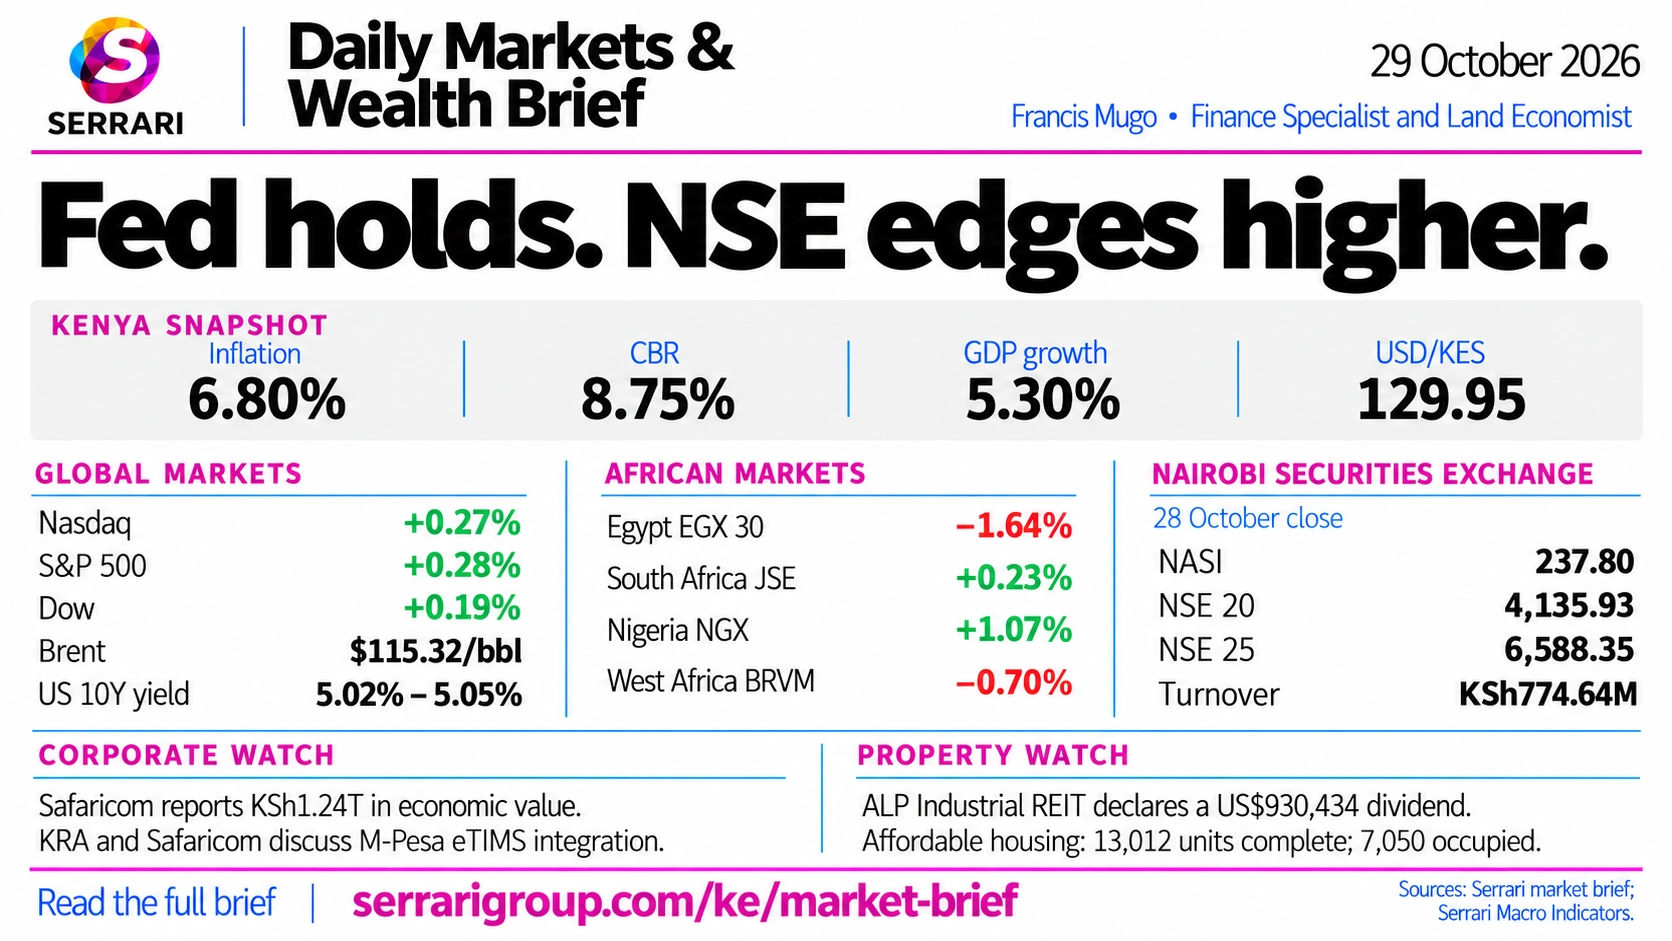
Global Markets
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
1. World Bank Commodity Outlook Report
- Overall Commodity Prices: Expected to rise 23% in 2026 before easing 7% in 2027.
- Energy Prices: Forecast to jump 32% in 2026, with Brent crude averaging $91 per barrel and global supply dropping by 5.2%. European natural gas is set to surge 58.3% to $19/MMBtu via Strait of Hormuz constraints.
- Food & Agriculture: Food prices are projected to climb 10% in 2026 and another 7% in 2027 due to weather and fuel cost pressures, with grains rising 14.1%. Fertilizers will grow 14% led by urea.
- Metals: Base metals are expected to hit record highs with a 25% increase driven by clean energy demand, while precious metals surge 40% with gold averaging $4,600 per troy ounce.
- Sub-Saharan Africa: Presents a complex, dual-track reality, creating deep economic divides between the region’s resource exporters and its resource-importing nations.
2. United States: The Fed Pause and Big Tech Divergence
- The Federal Reserve's Rate Pause: The FOMC voted 10-2 to hold interest rates steady within the 3.75%–4.00% range. While Chair Kevin Warsh acknowledged resilient economic spending and a healthy jobs market, he reiterated that inflation "remains elevated" (hovering near 3.7%). Investors are heavily pricing in an 85% probability of a 25-basis-point rate hike in December.
- Bonds React to Inflation Fears: The 10-year US Treasury yield pushed up past 5.04%. The yield curve steepened sharply as bond markets grew skeptical that the Fed could control sticky inflation without further tightening into 2027.
- Diverging Big Tech AI Capital Expenditures: Third-quarter hyperscaler earnings heavily destabilised the market. After-hours trading saw Microsoft jump over 3% due to blockbuster Azure cloud growth, while Alphabet plummeted 9-10% after missed revenue expectations and a negative free cash flow of $9.07 billion. This fueled a raging debate over whether the massive capital expenditures in AI infrastructure are yielding immediate returns.
3. Europe: Pre-ECB Caution and Fiscal Headwinds
- Energy Strains: European natural gas prices surged to a four-year high above €100/MWh, aggravated by ongoing escalations in the Middle East and the escalating US-Israeli proxy conflict with Iran.
- Monetary Policy Stagnation: Ahead of the upcoming European Central Bank (ECB) decision, markets braced for a pause. The region is grappling with weak growth forecasts (GDP +0.6% for 2026) alongside uncomfortably sticky inflation (projected at 2.7% for the year), limiting the central bank's ability to ease monetary pressure.
- Fiscal Pressures: Domestic political and fiscal vulnerabilities weighed on sentiment. This was particularly true in France, and in the UK where the government delivered a highly scrutinized new budget amid rising sovereign borrowing costs.
4. Asia: Explosive AI Chip Rebound and Currency Strains
- Blockbuster Semiconductor Earnings: Asian tech sectors staged a massive rally, tracking late-stage Wall Street AI optimism. South Korea’s KOSPI skyrocketed 6.63%, spearheaded by memory chip giant SK Hynix, which surged over 10% after reporting an astronomical 630% year-on-year operating profit increase to 83.33 trillion won ($62.8bn) due to the AI boom. Japan’s Nikkei 225 climbed 1.08% and Taiwan's TAIEX gained 2.04% under similar semiconductor momentum.
- Macro Headwinds and Monetary Deviations: Despite export-led tech gains, Chinese mainland indices bucked the trend (Shanghai Composite fell 1.3%) due to persistent weak domestic consumer demand. Regionally, currencies faced immense pressure from high U.S. bond yields. Meanwhile, the Reserve Bank of New Zealand (RBNZ) shocked local markets by unexpectedly keeping its interest rate at 2.75% in a tight 4-3 vote, triggering a sharp drop in the New Zealand dollar.
5. South America: Political Shockwaves and Commodity Booms
- Currency Volatility and Risk Exits: The Brazilian Real experienced one of its worst single-day collapses since 1994, recovering only a marginal 1% on Tuesday/Wednesday. Wall Street institutions reacted swiftly; Citigroup entirely closed its Brazilian risk exposures, and Morgan Stanley downgraded the country's equities to equal- weight amidst panic over future public spending and structural sovereign debt. Other regional tracking indices, like Colombia's COLCAP, remained flat or slightly negative (-0.03%).
- Sovereign Rating Upgrades: Despite regional domestic turbulence, Fitch Ratings noted exceptional resilience across emerging Latin American economies. Capitalizing on high oil prices, countries like Argentina, Bolivia, and Ecuador saw sovereign credit upgrades from hyper-distressed brackets.
- Global Supply Hub Inflows: South American markets are benefiting from a massive, long-term trade pivot. Countries like Brazil, Chile, and Peru are seeing robust foreign direct investment (FDI) inflows as they function as the critical resource providers (minerals, energy, and food) feeding North American and Asian tech- manufacturing corridors.
Global Equity Indices
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
Closing levels and daily moves supplied in the 28 October market snapshot.
| Region | Benchmark | Close | Daily change |
|---|---|---|---|
| United States | S&P 500 | 7,743.98 | +0.28% |
| United States | Nasdaq Composite | 26,549.85 | +0.27% |
| United States | Dow Jones Industrial Average | 52,475.10 | +0.19% |
| Europe | STOXX Europe 600 | 644.14 | +0.07% |
| Japan | Nikkei 225 | 63,954.19 | +1.08% |
| South Korea | KOSPI | 5,952.41 | +6.63% |
Sovereign Yields & Kenya Treasury Bills
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
| Treasury bill | Latest auction average |
|---|---|
| 91-day | 8.748% |
| 182-day | 8.859% |
| 364-day | 9.027% |
Global sovereign yields
- United States: 10-year yield: 5.02%–5.05%, as the Federal Reserve holds its policy range at 3.75%–4.00%.
- Germany: 10-year Bund: 3.38%; eurozone average near 3.97% ahead of the ECB decision.
- France: 10-year yield: 4.92%, amid budget and fiscal concerns.
- Japan: 10-year yield: 2.83%, ahead of the Bank of Japan meeting.
- Brazil: 10-year yield: 15.10%–15.27%, amid election-related public-debt concerns.
Kenya government bonds
- 2-year bond: 9.110%
- 5-year bond: 9.230%
- 10-year benchmark: 12.530%
- 15-year bond: The supplied brief quotes coupons around 12.34%, including FXD3/2019/015; this is a coupon reference rather than a market yield.
Global Commodities
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
US & International Energy Markets
- Brent Crude: Settled up 1% to $115.32 per barrel (intraday highs touched $117) due to compounding fears of military escalation in Iran and attacks on Saudi infrastructure.
- WTI Crude: Gained 3% to settle at $102.78 per barrel, reacting sharply to a decline in US crude inventories.
- European Natural Gas: Prices are projected to surge 58.3% for the full year 2026 to $19 per MMBtu, following depleted liquefied natural gas (LNG) shipments bypassing the Strait of Hormuz.
Precious & Industrial Metals (Global / Asia / Americas)
- Gold: Spot gold traded at $4,070.28 per ounce (with December futures at $4,051.60). While safe-haven demand remains fundamentally high for 2026, gold faced minor liquidity-driven selling pressure as North American funds rotated cash to cover losses in equities and tech. Conversely, Asian demand softened the dip as China's net imports surged 28%.
- Copper: Maintained historic highs near an annual projected average of $13,200 per metric ton ($5.90/lb). South American suppliers like Peru's and Mexico's Southern Copper saw evaluations skyrocket, fueled by severe supply bottlenecks and heavy structural demands from global power grids and AI data centers.
- Other Metals: Silver fell 1.5% to $53.15 per ounce, while aluminium and tin hovered near record highs.
Agriculture & Softs (South America & Asia)
- Grains (Wheat & Maize): Wheat prices are up roughly 28% this year as global output contracts by 3% due to continuous attacks on Black Sea grain shipping lines.
- Soft Commodities: Cocoa prices on the day fell 2.17% to $5,456 per ton, showing structural recovery signs compared to its historic late-2024 peaks.
- Weather & Fertilizers: The intense El Niño pattern threatens primary harvests across Asia and South America with floods and droughts. Combined with rising natural gas inputs, global fertilizer prices jumped 14%, impacting overall agricultural operating costs.
Africa Markets
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
| Market | Benchmark | Close | Daily change |
|---|---|---|---|
| South Africa | JSE Top 40 / SAALL (as supplied) | 110,073.00 | +0.23% |
| Nigeria | NGX All-Share | 253,990.06 | +1.07% |
| Egypt | EGX 30 | 49,281.24 | −1.64% |
| West Africa | BRVM Composite | 528.34 | −0.70% |
South Africa (Local Currency Curve)
- South African local government bonds rallied slightly towards the end of October, driven by the National Treasury's announcement to reduce weekly fixed-rate bond auction sizes and roll out buyback initiatives. Implied inflation/breakeven expectations sit at approximately 4.41%.
- 10-Year Benchmark Yield: 8.72% to 8.75% (down roughly 26 bps over the last month)
- 20-Year Yield: 9.20%
- 25-Year Yield: 9.18%
Nigeria (Dual Market Pressure)
- The Central Bank of Nigeria (CBN) pivoted toward a monetary easing cycle, initiating a 350-basis-point cut to its benchmark Monetary Policy Rate (to 23.00%). This has triggered massive excess liquidity inflows and a sharp downward repricing on short-term assets.
- Local Treasury Bills (364-Day): Yields compressed rapidly during the October 28 auction due to a bidding frenzy of over ₦4 trillion. The Debt Management Office (DMO) actively rejected higher investor bids, enforcing price discipline below the 18% mark.
- Local 10-Year Government Bond: 16.90%
- Eurobond Market (USD Nominated): Long-term hard currency borrowing costs remain stubbornly high. The Nigeria 2032 Eurobond note yielded 7.87%, while longer-dated tenors such as the 2049 Eurobond closed at 9.25%.
Egypt (Rising Currency and Fiscal Risk)
- The Central Bank of Egypt (CBE) is widely expected to hold its overnight deposit rate at 19% to combat inflationary and currency depreciation pressures, with the Egyptian pound hitting a record low against the dollar. This domestic volatility has pushed local yields to near 52-week highs.
- 5-Year Local Currency Government Bond: 23.74% to 23.88%
- Primary Auction Yields (3-Year Local Note): Weighted average yields on recent short-term issuances accepted by the CBE cleared at 24.43%.
- Eurobond Market: Reflecting fiscal buffers from major external bilateral deals (like UAE capital injections), general Eurobond yields have risen to an average of 8.75%.
West African Eurobonds (USD/EUR Issuances)
- Frontier West African countries have relied heavily on international hard-currency capital markets, raising billions to refinance maturing obligations. However, investors are enforcing a sharp divergence based on credit rating and default risk.
- Ivory Coast & Benin: Deemed the higher-quality issuers of the region, their multi-tranche Eurobonds remain comfortably heavily oversubscribed with yields holding under the 10% structural threshold.
- Senegal: Stands out as the highest-risk sovereign in the regional snapshot following a debt treatment announcement. Its Eurobond yield traded distressed at 20.8%.
1. South Africa: Precious Metals & Fuel Relief
- Precious Metals Boost: The fiscus has received a major multi-billion rand reprieve via mining taxes driven by elevated Gold (trading near $4,051.78/oz) and Platinum ($1,531.95/oz). The Minerals Council South Africa notes that these price-driven windfalls are acting as a primary shock absorber for the economy amid slow 1.2% domestic GDP growth.
- Energy & Fuel: Domestic fuel costs remain heavily vulnerable to international oil spikes. To combat severe inflationary pressure on transport, the government announced a temporary R10 billion fuel levy relief package, reducing the diesel levy by R3/litre and petrol by R1.50/litre starting November 4, 2026.
- Agriculture: Q2 agricultural exports to the U.S. dropped by 28% due to trade and tariff realignments. Domestically, the weaker Rand has kept local import parity costs high for oilseeds and summer crops despite a bumper local maize harvest.
2. Nigeria: Energy Surges & Harvest Market References
- Crude Oil & The Economy: With global Brent crude projected to average $91 per barrel for 2026, Nigeria faces a dual reality. Higher prices offer potential export revenue boosts, but significantly threaten domestic logistics, manufacturing, and consumer purchasing power due to sensitive petrol pricing.
- Naira and Inflation: Headline inflation slowed to 14.63% in late 2026 due to brief currency stability, though food inflation remains high at 19.59%.
- Local Farmgate Prices: According to updates from Commodity Nigeria, key market references stand at:
- Cocoa: ₦6,114.25 / kg
- Sesame: ₦2,300 / kg
- Cashew (RCN): ₦1,719.50 / kg
- Soybean: ₦753.39 / kg
- Maize: ₦345.10 / kg
3. West Africa: Cocoa Market Rebound
- Supply Deficits & Disease: The 2026/27 global surplus was heavily revised down by 83% to just 25,000 tonnes. Port arrivals in Côte d’Ivoire dropped 43% year-on-year to 122,453 MT for October. Below-average rainfall, minimal sunshine, and the spread of black pod disease in Côte d’Ivoire and Ghana have constrained overall bean quality and output.
- Price Movements: Trading Economics shows global cocoa futures stabilizing around $5,455 – $5,600 per metric ton. While prices are lower than the absolute historical highs of 2024–2025, they remain well above long-term historical averages due to the looming threat of a strong El Niño.
- Regional Exports: Conversely, Nigeria bucked the regional trend, recording a 33% year-on-year surge in September cocoa exports (19,343 tons) as local merchants capitalized on international price margins.
4. Egypt: Trade Expansions & Regional Manufacturing
- Inter-African Trade: Egypt's strategic focus on the African Continental Free Trade Area (AfCFTA) has yielded solid results. Trade volume with major regional partners—including South Africa, Nigeria, and Senegal—surged to $1.1 billion over the first seven months of 2026.
- Commodity Flows: According to data from the Common Market for Eastern and Southern Africa, Egypt has significantly managed its trade balance by scaling back general merchandise imports from $2.1B to $1.57B, while aggressively scaling industrial manufacturing, tourism, and fertilizer exports to the rest of the continent. However, global shipping blockades in the Middle East have driven localized fertilizer production costs up.
African currencies
- South Africa: USD/ZAR 16.66; rand down 0.22%.
- Nigeria: Official USD/NGN 1,347.53; parallel market 1,380–1,390.
- Egypt: USD/EGP 56.09; pound down 7.7% in a month.
- West Africa: USD/XOF 589.40; CFA franc pegged to the euro.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
The All-Share and NSE 25 edged higher while the NSE 20 slipped at the 28 October close.
- Market activity: 21,675,245 shares traded, with total equity turnover of KSh 774,637,452.93.
| Index | Close | Daily change (points) |
|---|---|---|
| NSE All-Share (NASI) | 237.80 | +2.04 |
| NSE 20 | 4,135.93 | −3.89 |
| NSE 25 | 6,588.35 | +0.84 |
| NSE 10 | 2,568.23 | +6.21 |
Foreign Exchange
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
| Currency | CBK indicative KES | Typical bank buying KES | Typical bank selling KES |
|---|---|---|---|
| USD | 129.95 | 127.90 | 132.90 |
| GBP | 172.73 | 167.70 | 178.70 |
| EUR | 144.49 | 140.22 | 149.57 |
Global currencies
- Global currency reference table: Units per US dollar / US dollars per currency unit: EUR 0.8965 / 1.1154; GBP 0.7503 / 1.3327; JPY 157.8000 / 0.0063; CNY 6.6667 / 0.1500; BRL 5.3473 / 0.1870.
- US and Europe: Safe-haven flows and stronger-than-expected economic indicators pushed the US Dollar into a minor rally. The EUR/USD pair slipped down to 1.1154, while the British Pound held slightly firmer at 1.3327 against the dollar.
- Asia: The Japanese Yen experienced continuing pressure from yield differentials, hovering around 157.80 JPY per USD. Meanwhile, the Chinese Yuan remained relatively stable at 6.66 CNY per USD.
- South America: The Brazilian Real felt some upward pressure relative to the previous weeks, stabilizing near 5.35 BRL per USD.
Other Kenyan currency references
- KES equivalents: ZAR 7.79 KES; CNY approximately 19.49 KES; 100 JPY 82.36 KES.
- East African currencies per KES: UGX 26.88; TZS 19.16; RWF 11.24; BIF 22.82.
Kenya Commodities
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
| Commodity | Wholesale reference | Market context |
|---|---|---|
| Dry maize | KSh 4,200–4,300 per 90 kg bag | Retail KSh 55.79/kg; stable supply |
| Sindano rice | KSh 156.00/kg | Down approximately 10% month on month |
| Red haricot beans | KSh 122.45/kg | Retail up to KSh 152.00/kg |
| Tomatoes | KSh 64.81/kg | Prices ease on high supply |
Export commodity auctions
- Tea (Mombasa Auction): Kenyan tea recorded a strong week, averaging KSh 301.86 ($2.34) per kg. Lower total auction volumes—due to seasonal bush pruning by KTDA smallholder farmers—pushed up competition. Premium factories like Mununga led trading at peaks of KSh 447.63 ($3.47) per kg.
- Coffee (Nairobi Coffee Exchange): High-quality beans attracted solid international bidding. Grade AA beans fetched the highest value averages at $358.52 per bag, while the benchmark volume moving Grade AB closed out at an average of $350.63 per bag.
Kenya Corporate News
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
Safaricom Launches 15th Sustainability Report, Highlights Sh1.24 Trillion Economic Footprint
- Safaricom PLC officially launched its 2026 Sustainable Business Report, revealing that it generated Sh1.24 trillion in total economic value for Kenya over the past financial year.
- Job Creation: The telco's operations, infrastructure investments, and supply chain supported 1.405 million jobs across the broader economic ecosystem.
- M-Pesa Value: The report highlighted that the standalone social value generated by M-Pesa reached Sh478.1 billion.
- AI Fraud Prevention: Chief Executive Peter Ndegwa noted that Safaricom now uses Artificial Intelligence to block 94% of potential fraud attempts before they can impact customers.
KRA and Safaricom in Talks Over M-Pesa eTIMS Integration
- The Kenya Revenue Authority (KRA) is negotiating a deal with Safaricom to enable M-Pesa to generate electronic tax invoices (eTIMS) automatically on behalf of micro-traders.
- The Goal: The move is designed to strip compliance headaches away from small traders, allowing them to legally and easily supply goods and services to larger corporations requiring tax expense claims.
Capital Markets & NSE Trading Surges
- Olympia Capital: The brief reports a 3.98 million-share stake accumulated by Ndindi Nyoro through Limpopo Capital, with plans to develop an acquisition vehicle.
- Kenya Pipeline Company: The brief reports Aliko Dangote’s acquisition of a 25% stake for $327 million.
- ALP Industrial REIT dividend: Approved interim distribution of US$930,434 (KSh 120.9 million), or US$0.0207 per unit, payable on 27 November 2026.
Executive Appointments
- Britam Appoints New Chair: Britam Holdings named former EY Kenya Managing Partner Celestine Munda as Board Chairperson, solidifying permanent leadership seven months after the passing of former chair Kuria Muchiru.
Central Bank of Kenya Enforces Strict Rules for Non-Deposit Credit Providers
- The Central Bank of Kenya (CBK) has operationalized the Non-Deposit Taking Credit Providers Regulations, 2026, revoking the older 2022 Digital Credit Providers framework.
- Foreign Currency Ban: The rules explicitly bar non-deposit lenders from disbursing loans in foreign currencies—a massive hit to asset financiers who rely on dollar-denominated facilities.
- AI Accountability: Any fintech or lender leveraging automated AI systems to approve or deny credit must maintain human oversight, proactively mitigate discriminatory bias, and clearly explain automated decisions to customers.
Logistics Giant CMA CGM Debuts Dedicated Rail Service
- Global shipping and logistics firm CMA CGM launched its first dedicated block train service in partnership with Kenya Railways and the Kenya Ports Authority.
- Capacity: Operating out of the Port of Mombasa directly to the Nairobi-Embakasi Inland Container Depot, the train pulls 54 wagons capable of hauling 108 containers (TEUs) at a weekly frequency.
Agricultural Alert: Kenya Halts Avocado Sea Shipments
- The Horticultural Crops Directorate via the Agriculture and Food Authority (AFA) issued a directive halting the export of four major avocado varieties by sea starting Friday, October 30, 2026.
- Impacted Varieties: The freeze applies to Hass, Fuerte, Pinkerton, and Jumbo.
- Reason: National field assessments indicated that current production volumes are temporarily too low to support massive shipping containers.
Macro & Bilateral Corporate Trends
- Russia-Kenya Business Roundtable: President William Ruto arrived in Moscow for the Third Russia-Africa Summit, pitching a Sh5.2 trillion ($40 billion) 10-year infrastructure portfolio to Russian private entities, demanding they set up local manufacturing hubs for fertilizer, engineering, and green hydrogen rather than exporting raw products.
- German Call Centre BPO Expansion: Germany's major customer service association (CCV) met with ICT leadership to position Kenya as a primary Business Process Outsourcing (BPO) hub for Europe, fast-tracking data adequacy laws to match EU frameworks.
Kenya Real Estate
Figures as at · Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
1. Capital Markets & Industrial REIT Milestones
- ALP REIT Declares Historic Interim Dividend: Africa Logistics Properties (ALP) declared its first-ever dividend distribution of $930,434 (Sh 120.9 million) for the ALP Industrial Real Estate Investment Trust. The payout represents $0.0207 per unit. This marks a major proof-of-concept milestone as Kenya’s first industrial income REIT and its first USD-denominated property vehicle listed on the NSE.
- Expansion & Distribution Model Shifts: Simultaneously, ALP launched its brand-new West Kivu warehouse units within the ALP West Logistics Park in Tilisi, Kiambu County. To set a new standard for liquidity in the local property sector, corporate leadership announced plans to transition from the typical annual payout model toward a quarterly dividend distribution framework as the portfolio scales up.
2. National Housing Policy & Infrastructure Milestones
- Affordable Housing Program Reaches 13,000+ Units: Fresh data released by the Affordable Housing Board indicates the national program has successfully completed 13,012 housing units, with 7,050 properties already fully occupied. The state's aggressive construction ramp-up has reportedly created roughly one million formal and informal jobs since 2022.
3. Market Slowdown, Valuation Rules & Distress Auctions
- KUSCCO Liquidation Triggers Mass Property Auctions: In a massive wave of real estate distress liquidations, Watts Auctions officially listed dozens of prime assets owned by the Kenya Union of Savings and Credit Co- operatives (KUSCCO) Limited. The public auction features vacant commercial plots, high-end maisonettes, family bungalows, complete rental apartment blocks, and half-built structures scattered across Nairobi, Kiambu, Machakos, Kajiado, Mombasa, Nakuru, and Kisumu.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.95
CBK indicative rate.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026GBP / KES
172.73
CBK indicative rate.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026EUR / KES
144.49
CBK indicative rate.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
Equities
NSE All-Share
237.80
+2.04 points.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026NSE 20-Share
4,135.93
−3.89 points.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026NSE 25-Share
6,588.35
+0.84 points.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026Equity turnover
KSh 774.64 million
28 October close.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
Rates
Central Bank Rate
8.75%
Prevailing policy rate from the supplied artwork.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026Kenya 10-year bond
12.530%
Benchmark bond yield.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 202691-day Treasury bill
8.748%
Latest auction average.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026182-day Treasury bill
8.859%
Latest auction average.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026364-day Treasury bill
9.027%
Latest auction average.
As at
Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
At a glance
- 1The Federal Reserve holds its policy range at 3.75%–4.00%; the S&P 500 rises 0.28% and Brent settles at US$115.32 a barrel.
- 2The NSE All-Share gains 2.04 points to 237.80, while USD/KES stands at 129.95 and equity turnover reaches KSh 774.64 million.
- 3ALP Industrial REIT declares a US$930,434 dividend; affordable housing completions reach 13,012 units, with 7,050 occupied.
Sources
- Serrari Group desk compilation, 29 October 2026; Markets Snapshot – 28 October 2026
- Serrari Group supplied artwork, 29 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — market statistics
- Serrari published Africa macro data