
30 October 2026
Technology stocks retreat as the Nasdaq falls 1.38%, while the NSE All-Share slips to 237.61 on KSh 510.88 million turnover. Kenafric launches a KSh 1.3 billion venture fund, KenGen upgrades Olkaria 1 to 60.5 MW and TRIFIC Green REIT declares US$0.02 per unit.

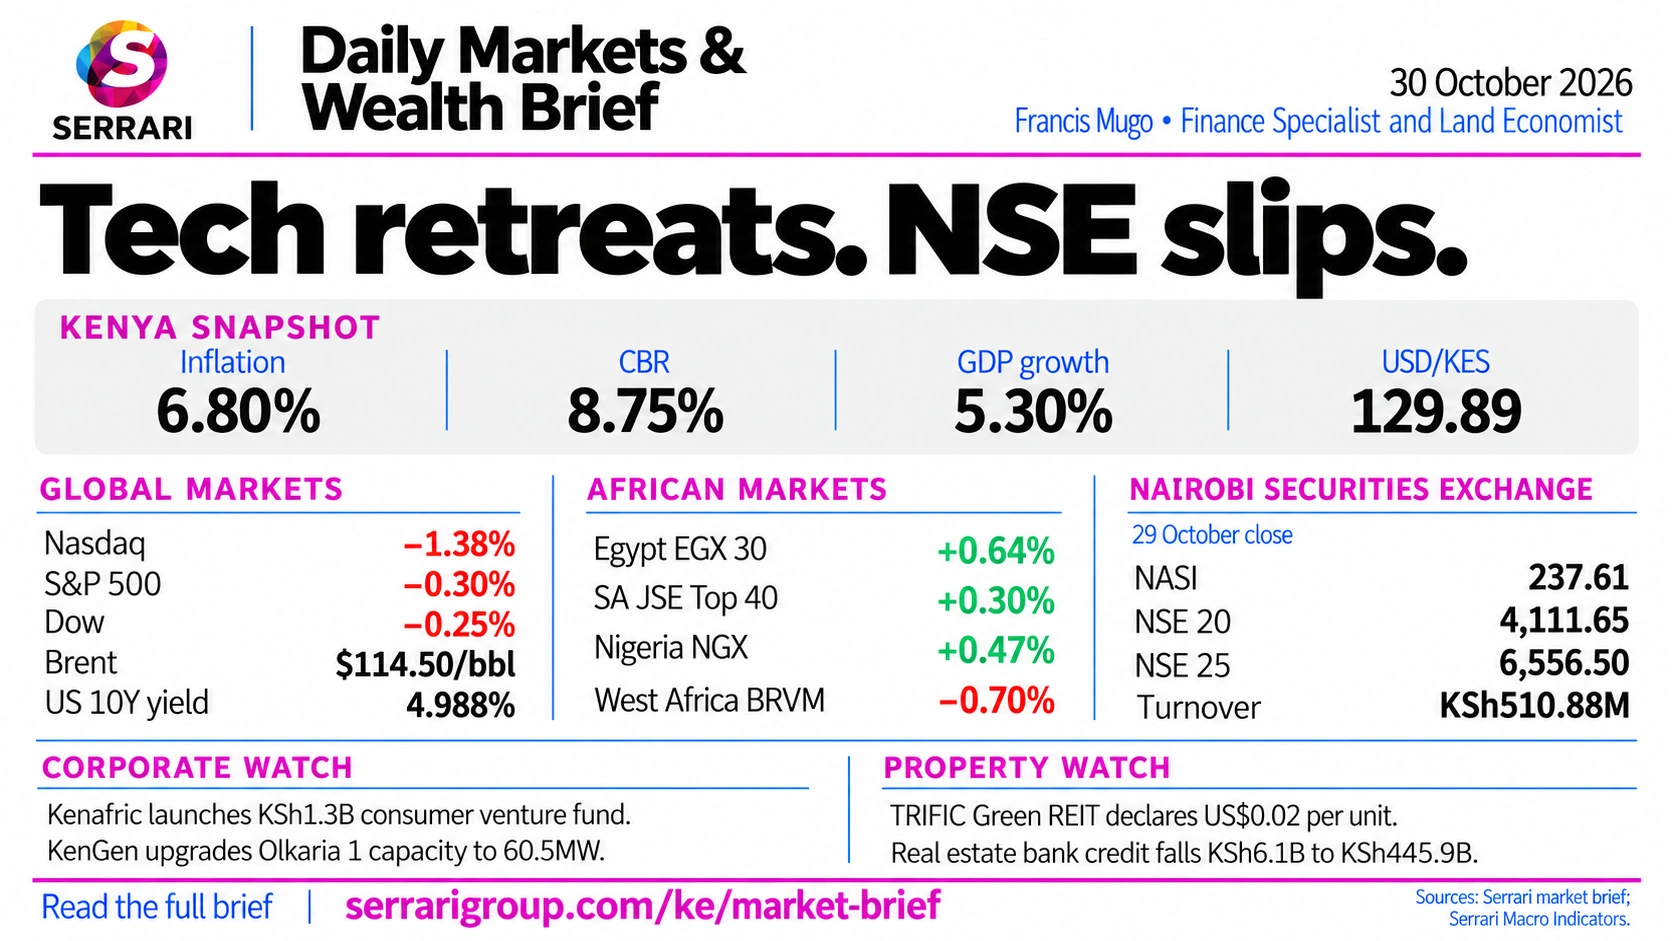
Global Markets
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
Central bank rate holds, technology earnings and diplomatic developments shaped the session, with US megacap technology losses weighing on benchmark indices.
United States & Canada
- A sharp re-evaluation of the "AI trade" penalized megacap tech giants and dragged the major benchmark indices into the red, despite broader market resilience.
- The Breadth Juxtaposition: Interestingly, over 80% of S&P 500 components (406 holdings) actually advanced. Defensive sectors like Healthcare (boosted by Eli Lilly's 6% jump) and Real Estate hit notable highs, but could not offset tech's heavy weight.
- Corporate Earnings Shock: Google-parent Alphabet plummeted 12.6%, marking its worst single-day percentage drop on record after concerns surfaced over its massive AI capital expenditure and free cash flow. Software firms ServiceNow (-25%) and Fortinet (-22%) also collapsed on disappointing outlooks. Conversely, Microsoft gained 2.6% after posting strong Azure cloud growth.
- Macro Factors: The Federal Reserve held interest rates steady at 3.75%–4.00%. Preliminary readings showed U.S. GDP expanded at a strong 3.4%. Meanwhile, in Canada, business groups expressed growing anxiety over North American trade stability ahead of cross-border data and tariff deadlines.
Europe
- European markets reacted to steady ECB rates and regional corporate results.
- Central Bank & Political Drama: The European Central Bank (ECB) kept its benchmark deposit rate steady at 2.5%. However, the major headline was ECB President Christine Lagarde announcing she will step down early in February 2027, sparking an early political race for her successor before upcoming European elections.
- Corporate Winners: In Germany, Adidas surged nearly 6% after hitting record Q3 earnings and boosting its full-year guidance. In France, Renault rose 4.8% and Air Liquide added 3.1% following strong quarterly revenues.
Asia
- Asian markets delivered mixed performances as regional tech heavyweights absorbed conflicting domestic developments and braced for the U.S. sell-off.
- Japan: The Nikkei 225 rallied 1.1% to close at 64,659.47, supported initially by the Fed's steady rate pause from the previous night and a weaker Yen.
- South Korea: The KOSPI fell 1.2%, cutting short its multi-day rally. Heavyweight Samsung Electronics slid 4.1%; despite posting surging profits, the company failed to outline clear shareholder return plans. Rival SK Hynix rose 4.6%, carrying over momentum from its massive $75 billion shareholder return plan announced earlier.
- China & Hong Kong: Mainland China's Shanghai Composite dropped 0.82% on deepening concerns regarding regional AI investment sustainability, while Hong Kong's Hang Seng index managed a modest 0.5% gain.
South America/Latin America
- Regional currencies faced downward pressure as global safe-haven flows favoured the US dollar, leaving commodity-dependent Latin American indices range-bound and volatile.
Global Equity Indices
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
29 October closing levels; European daily changes are omitted because the supplied narrative and table disagree.
| Market | Benchmark | Close | Daily change |
|---|---|---|---|
| United States | S&P 500 | 7,720.39 | −0.30% |
| United States | Nasdaq Composite | 26,184.72 | −1.38% |
| United States | Dow Jones Industrial Average | 52,342.56 | −0.25% |
| Canada | S&P/TSX Composite | 36,265.09 | +0.26% |
| Brazil | IBOVESPA | 171,006.10 | −2.68% |
| Mexico | IPC Mexico | 69,182.39 | −0.76% |
| Germany | DAX | 25,590.77 | — |
| France | CAC 40 | 7,887.14 | — |
| United Kingdom | FTSE 100 | 10,686.54 | — |
| Japan | Nikkei 225 | 64,659.47 | +1.10% |
| South Korea | KOSPI Composite | 5,937.66 | −1.24% |
| Taiwan | TSEC Capitalization Weighted | 46,368.33 | −1.42% |
Sovereign Yields & Kenya Bonds
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
| Kenya tenor | Government bond yield |
|---|---|
| 2-year | 9.20% |
| 3-year | 10.70% |
| 5-year | 9.60% |
| 7-year | 11.20% |
| 10-year | 12.53% |
International sovereign yields
- United States: 2-year 4.654% (down 0.077 percentage points); 10-year 4.988% (down 0.056 percentage points); 30-year 5.310% (down 0.050 percentage points).
- Canada: 2-year 3.406%; 10-year 3.858%, down 0.020 percentage points.
- Europe: Germany: 2-year Bund 3.000%, 10-year Bund 3.339% (down 0.050 percentage points); UK 10-year gilt approximately 4.45%.
- Japan: 2-year JGB 1.895%; 10-year 2.830% (up 0.005 percentage points); 30-year 3.880%.
- Latin America: Regional 10-year average 6.01%; Brazil approximately 12.15%; Mexico approximately 9.70%.
Kenya government bonds
- Policy and trading: Central Bank Rate 8.75%; secondary bond turnover KSh 9.80 billion.
- Curve spread: The 10-year–2-year spread is 333 basis points.
Foreign Exchange
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
| Currency | CBK indicative KES |
|---|---|
| USD | 129.89 |
| GBP | 173.58 |
| EUR | 145.34 |
North America & Canada
- The Dollar Index (DXY): Closed marginally lower at 101.99, failing to sustain its earlier weekly momentum as traders processed a 10–2 Fed vote to hold steady, paired with an annualised Q3 GDP print of 3.4%.
- USD/CAD: Slipped below the critical 1.4000 support level to close around 1.3980. The Canadian Dollar gained relative appeal after the Bank of Canada (BoC) delivered its first interest rate hike in more than three years— raising its policy rate by 25 basis points to 2.50%.
Europe
- EUR/USD: Rallied roughly 0.29% to close at 1.1187. The Euro shrugged off early minor intra-day losses following the European Central Bank (ECB) meeting. While the ECB left its benchmark deposit rate steady at 2.5%, the currency pairs found traction amid broader post-Fed dollar soft patches.
- GBP/USD: Stabilised near 1.3384, moving inside tight horizontal parameters as fragile risk sentiment restricted any breakout extension.
Asia-Pacific
- USD/JPY: Consolidating on the front foot, the pair edged slightly up to 158.04 in official spot closes, while cross-market risk volatility saw spot spikes testing towards 160.50. Traders were protective ahead of the multi-day Bank of Japan policy conclusion scheduled for Friday.
- AUD/USD: Traded flatly near 0.7008 as the Australian Dollar absorbed the structural consolidation of global commodity baskets.
- NZD/USD: Faced direct downward pressure after the Reserve Bank of New Zealand (RBNZ) unexpectedly skipped a widely anticipated rate increase, holding steady and driving a sell-off in the Kiwi dollar.
Latin America
- USD/BRL & USD/MXN: Emergent flows favoured the greenback inside developing spaces as Wall Street tech indices registered hefty losses. Structural safe-haven currency premium expansions pushed both the Brazilian Real and the Mexican Peso slightly onto the defensive against the U.S. Dollar.
East African currencies per Kenyan shilling
- CBK indicative cross-rates: KES/UGX 33.50; KES/TZS 20.39; KES/RWF 11.36; KES/BIF 23.08.
Regional US dollar benchmarks
- Uganda and Tanzania: USD/UGX 4,349.52; USD/TZS 2,625.89.
Global Commodities
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
Energy (US, Canada & Europe)
- Brent crude: US$114.50 per barrel, down 0.7%.
- West Texas Intermediate: US$101.74 per barrel, down 1.0%.
- European Natural Gas: Hovered sharply higher, maintaining a premium above €100/MWh due to localized infrastructure and fuel delivery barriers.
Precious Metals (Global)
- Gold (COMEX): US$4,035.00 per ounce, down US$16.60.
- Silver: Settled lower at approximately $33.10 per ounce (reflecting broader intraday asset consolidation).
Industrial Metals (Asia & Europe)
- LME Copper: Down 0.9% to settle at $14,352 per metric ton.
Agriculture (North & Latin America)
- Chicago wheat: US$6.03¾ per bushel, up 4.75 cents.
- US corn: US$4.51¼ per bushel, down 0.50 cents.
- US soybeans: US$12.19¾ per bushel, down 4.75 cents.
- Raw sugar (No. 11): Settled slightly higher at 19.47 cents per pound.
Africa Markets
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
| Market | Benchmark | Close | Daily change |
|---|---|---|---|
| South Africa | FTSE/JSE Top 40 | 101,876.00 | +0.30% |
| Nigeria | NGX All-Share | 254,083.02 | +0.47% |
| Egypt | EGX 30 | 49,596.14 | +0.64% |
| West Africa | BRVM Composite | 528.34 | −0.70% |
Equity Stock Indices
- South Africa (JSE): The benchmark FTSE/JSE Top 40 Index climbed 0.30% to close at 101,876.00 points. The market remains under pressure from resource sector weights despite a slight monthly gain.
- Nigeria (NGX): The NGX All-Share Index gained 0.47% to close at a record-breaking 254,083.02 points. Total equity market capitalization crossed an all-time high of ₦164.97 trillion, majorly driven by a 5.82% surge in Dangote Cement.
- Egypt (EGX): The EGX 30 Index rose 0.64% to settle at 49,596.14 points, buoyed by sustained buying pressure from foreign institutional portfolio investors.
- West Africa (BRVM): The regional BRVM Composite Index slid 0.70% to close at 528.34 points, pulling back slightly as the market digested heavy trading volumes centered around the recent Sonatel stock split.
Foreign Exchange (Forex) Rates
- Values represent the local currency cost of one US Dollar (USD).
- South African Rand (USD/ZAR): 16.45 ZAR. The rand steadied as local markets digested global monetary policy cues and commodity pricing.
- Nigerian Naira (USD/NGN): 1,346.91 NGN at the official window (NFEM). Parallel bureau de change (BDC) rates tracked slightly wider, averaging 1,390 NGN.
- Egyptian Pound (USD/EGP): 49.15 EGP.
- West African CFA Franc (USD/XOF): 604.50 XOF (pegged to the Euro).
10-Year Sovereign Bond Yields
- South Africa 10Y: 8.73%. Local fixed-income notes saw modest foreign asset manager sales as investors moved funds into equities.
- Nigeria 10Y: 16.90% for local currency naira bonds. Meanwhile, its sovereign US Dollar Eurobond yield sat at 7.93% following strong bargain hunting on oil-linked emerging market issuers.
- Egypt 10Y: 23.55% local yield. High inflation expectations and aggressive domestic spending continue to sustain elevated frontier yield pricing.
- West Africa (BRVM/BCEAO): Average yields across regional WAEMU local currency bonds traded around 6.75% – 7.25%.
Energy (Nigeria & Egypt)
- Brent Crude Oil: Settled around $114.50 – $115.40 per barrel (down roughly 0.7%).
- Nigeria: While the state-backed NNPC benefited from high seaborne crude prices, domestic fuel distribution costs faced pressure due to ongoing downstream deregulation reforms.
- Egypt: Elevated global Brent prices increased import pressures on state energy balances, prompting tighter government monitoring of local oil and gas reserves heading into the winter season.
Precious Metals (South Africa)
- Gold (Spot): Dropped 0.9% to settle around $4,030.94 per troy ounce.
- Platinum (Spot): Suffered a steeper intraday retreat, falling roughly 3.4% to close at $1,487.00 per troy ounce. Locally on the ground, spot platinum traded at approximately ZAR 24,781.84 per ounce, dragging down the mining-linked South African Rand.
Soft Commodities & Agriculture (West Africa)
- Cocoa (Ivory Coast & Ghana): Benchmark cocoa futures on the Intercontinental Exchange (ICE) flattened at $5,459.00 per metric ton.
- While down significantly from the historical 2024 spikes, prices were underpinned on October 29 by tight port arrival data from the Ivory Coast. Main-crop arrivals fell 43% year-over-year for October due to poor pod development, cloudy weather, and widespread black pod disease.
- Fears over a building El Niño weather pattern added further supply anxieties for the region's 2026/2027 harvests.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
All three reported NSE benchmarks slipped at the 29 October close.
- Market activity: Equity turnover was KSh 510.88 million across 15.06 million shares.
| Index | Close | Change (points) | Daily change |
|---|---|---|---|
| NSE All-Share (NASI) | 237.61 | −0.19 | −0.08% |
| NSE 20 | 4,111.65 | −24.28 | −0.59% |
| NSE 25 | 6,556.50 | −31.85 | −0.48% |
Kenya Commodities
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
Domestic Cash Crop Auctions
- Mombasa Tea Auction: Data released by the East African Tea Trade Association (EATTA) confirms that Kenya smallholder factories traded 5.15 million kg of made tea, securing an overall weekly return of roughly KES 1 billion.
- Average Kenyan Price: USD 2.41 (KES 310.89) per kg.
- Top Performing Factory: Mununga Factory achieved the highest evaluation at KES 447 (USD 3.47) per kg.
- Regional Comparison: Premium Rwandan tea led the floor, averaging USD 3.27 (KES 421.83) per kg.
- Nairobi Coffee Exchange (NCE): Trading at the Nairobi Coffee Exchange Official Platform yielded USD 7.8 million (~KES 1 billion) during Sale 04.
- Average Price: USD 294.26 per 50 kg bag.
- Premium Grades: Grade AA drew USD 339.90, while Grade AB averaged USD 323.36 per 50 kg bag.
- Top Volume Grade: Grade AB dominated the trading floor with 9,300 bags cleared.
Wholesale Staple & Food Prices
- Dry Maize Grains: KES 55.79 per kg.
- Rice Grains: KES 157.50 per kg.
- Tomatoes: KES 64.81 per kg wholesale (National retail averages sit closer to KES 106.44 per kg).
- Tilapia Fish: KES 415.28 per kg.
Kenya Corporate News
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
Corporate Funding, Dividends & Board Changes
- Kenafric Ventures Rollout: Local consumer goods giant Kenafric Group launched a KES 1.3 billion ($10 million) fund managed alongside S2E Africa and FSD Africa. The fund targets seed-to-growth scale investments between KES 12.9 million and KES 258 million for direct-to-consumer businesses across Africa.
- KenGen Dividend Execution: State electricity producer KenGen Plc finalized its KES 0.75 per share dividend books closure on October 29. The payout, representing KES 15.5 billion in total allocations, is set to be distributed on January 21, 2027.
- Ecobank Kenya Board Shift: Appointed Risper Alaro as a Non-Executive Director following formal regulatory sign-off by the Central Bank of Kenya. Alaro concurrently maintains her seat as Group Finance Director at Centum Investment Company PLC.
- TRIFIC Green REIT Payout: The TRIFIC Green USD I-REIT declared an interim cash distribution allocation of USD 0.02 per unit, scheduling its book closure for November 20, 2026.
Regulatory Oversight & Financial Assets
- Unclaimed Share Bottleneck: The Unclaimed Financial Assets Authority (UFAA) informed the National Assembly Finance Committee that a KES 400 billion cost barrier prevents the transfer of 2.03 billion idle shares to its custody. The Central Depository and Settlement Corporation (CDSC) current levy of KES 200 per individual share transfer has frozen the consolidation process.
- New CBK Lending Rules: The Central Bank of Kenya (Non-Deposit Taking Credit Providers) Regulations 2026 officially took effect. The law places all non-deposit-taking lenders under tight CBK surveillance, outlaws local lending in foreign currencies, and enforces full local incorporation with physical head offices
Infrastructure, Energy & Construction
- Refurbishment of Olkaria 1 Geothermal Plant: State electricity generator KenGen Plc finalized a KES 15.6 billion ($120 million) upgrade on its 45-year-old Olkaria 1 geothermal unit. The plant's generation capacity rose from 45MW to 60.5MW under a new 25-year Power Purchase Agreement approved by EPRA. The injection aims to curb expensive electricity imports from Uganda and Ethiopia, which surged 60.5% in the last year to plug generation deficits.
- Pre-Election Rural Road Building Boom: The Kenya Rural Roads Authority (KeRRA) ramped up aggressive pre-election spending, awarding KES 15.54 billion in contracts to pave 95 rural roads across the Rift Valley, Central, Coast, and Nyanza regions since July.
International Trade & Investment Partnerships
- Ruto-Kremlin Business Roundtable: President William Ruto led a high-level trade delegation to Moscow to secure industrial manufacturing partnerships with Russian companies. Pitching Kenya as the primary economic hub for the African Continental Free Trade Area (AfCFTA), the administration invited investments in local mining, fertilizer processing, and engineering plants to counter a trade deficit where Kenya imports KES 42.8 billion from Russia but exports only KES 7 billion.
- German BPO Investment Mission: Kenya's State Department for ICT hosted a delegation from the German Customer Service & Call Center Association (CCV) to drive Business Process Outsourcing (BPO) investment into the "Silicon Savannah". The talks centered on data protection compliance, expanding European digital customer support operations to local talent, and deploying ethical AI skills training.
- EU Export Bottlenecks: The Kenya Association of Manufacturers (KAM) released an export catalogue pointing out that local manufacturers exploit just 10% of their duty-free market access to the European Union due to massive information gaps regarding compliance, traceability, and sanitary certification rules.
Clean Tech & Agriculture
- Off-Grid Solar Market Consolidation: A joint financial review revealed that Kenya's off-grid solar equipment sales grew 61%, driven heavily by rural Pay-As-You-Go networks. However, sector capital is concentrating heavily within a small group of players (Sun King, d.light, and Ignite Energy Access), which locked down roughly 70% of all corporate financing.
- Coffee Sector Expansion: At the East African Coffee Market & Conference in Nairobi, regulators confirmed that new coffee frontiers like Nandi County grew production by 560%. These emerging production zones now generate 30% to 40% of national coffee output as Kenya aims to reach 150,000 metric tonnes annually by 2028 under the Coffee Act of 2026
Kenya Real Estate
Figures as at · Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
High Court Strips Ruto’s Preferential Housing Directives
- In a major legal blow to executive declarations, the High Court in Nairobi declared President William Ruto's verbal directives to reserve 20% of Affordable Housing Programme units for teachers and police officers to be of no legal effect.
- The Ruling: Justice Patricia Nyaundi Mande ruled that while the President holds the constitutional authority to coordinate executive functions, that power cannot vary, alter, or supplement statutory criteria explicitly enacted by Parliament under the Affordable Housing Act.
- The Rationale: The court agreed with petitioners that introducing arbitrary preferential treatment via executive declarations undermines transparency, accountable governance, and the rule of law, as informal sector workers and the general public share an equal right to benefit from the tax-funded scheme.
KPDA 20th Annual Conference Convenes in Upper Hill
- The Kenya Property Developers Association (KPDA) hosted its landmark 20th Annual Conference at the Radisson Blu Hotel in Upper Hill, Nairobi, under the theme "Building Legacy, Shaping Cities: Kenya's Next Decade of Development".
- Policy Predictability: KPDA Chairman Zoravar Singh emphasized that to safely navigate rapid urbanization and the country's 2-million-unit housing deficit, Kenya urgently requires greater policy predictability, simplified building approval frameworks, and alternative financing instruments.
- Market Adjustments: Leading economists at the event highlighted that developers are actively shifting away from high-end builds toward lower-to-mid-end residential segments and satellite town apartments, which maintain a strong 93.7% occupancy rate.
Credit Contraction & Slump in Land Markets
- Fresh macroeconomic data revealed structural constraints in property transactions and corporate funding:
- Lending Slowdown: Central Bank of Kenya (CBK) figures showed that net domestic bank credit extended to the real estate sector shrank by KES 6.1 billion down to KES 445.9 billion, a direct result of tighter commercial bank risk profiling.
- Land Activity Drop: According to the Ministry of Lands, overall land transaction volumes posted their first annual decline in five years. The ministry attributed the slump to delays in transitioning secure digital titles and a drop in large-scale land banking.
REIT Returns & Yield Divergence
- TRIFIC Green REIT Payout: In the structured real estate investment trust sector, the TRIFIC Green USD I-REIT declared an interim cash distribution allocation of USD 0.02 per unit. The registry scheduled its book closure for November 20, 2026, ahead of a November 30 distribution.
- Suburbs vs. Satellites: Yield indexes continued to demonstrate a structural divergence. While average monthly rents in prime Nairobi suburbs climbed past KES 200,000, pricing corrections in satellite towns forced landlords to reprice or cut asking yields to match local medians.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.89
CBK indicative rate, matching the supplied artwork.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026GBP / KES
173.58
CBK indicative rate.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026EUR / KES
145.34
CBK indicative rate.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
Equities
NSE All-Share
237.61
−0.19 points, −0.08%.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026NSE 20-Share
4,111.65
−24.28 points, −0.59%.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026NSE 25-Share
6,556.50
−31.85 points, −0.48%.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026Equity turnover
KSh 510.88 million
29 October close.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
Rates
Central Bank Rate
8.75%
Prevailing policy rate.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026Kenya 2-year bond
9.20%
Government bond yield.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026Kenya 10-year bond
12.53%
Government bond yield.
As at
Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
At a glance
- 1The Nasdaq falls 1.38% and the S&P 500 loses 0.30% as technology earnings unsettle markets; Brent closes at US$114.50 a barrel.
- 2The NSE All-Share slips 0.08% to 237.61; turnover reaches KSh 510.88 million and USD/KES stands at 129.89.
- 3Kenafric launches a KSh 1.3 billion venture fund, while property-sector bank credit contracts by KSh 6.1 billion to KSh 445.9 billion.
Sources
- Serrari Group desk compilation, 30 October 2026; Markets Snapshot – 29 October 2026
- Serrari Group supplied artwork, 30 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — market statistics
- Serrari published Africa macro data