
2 November 2026
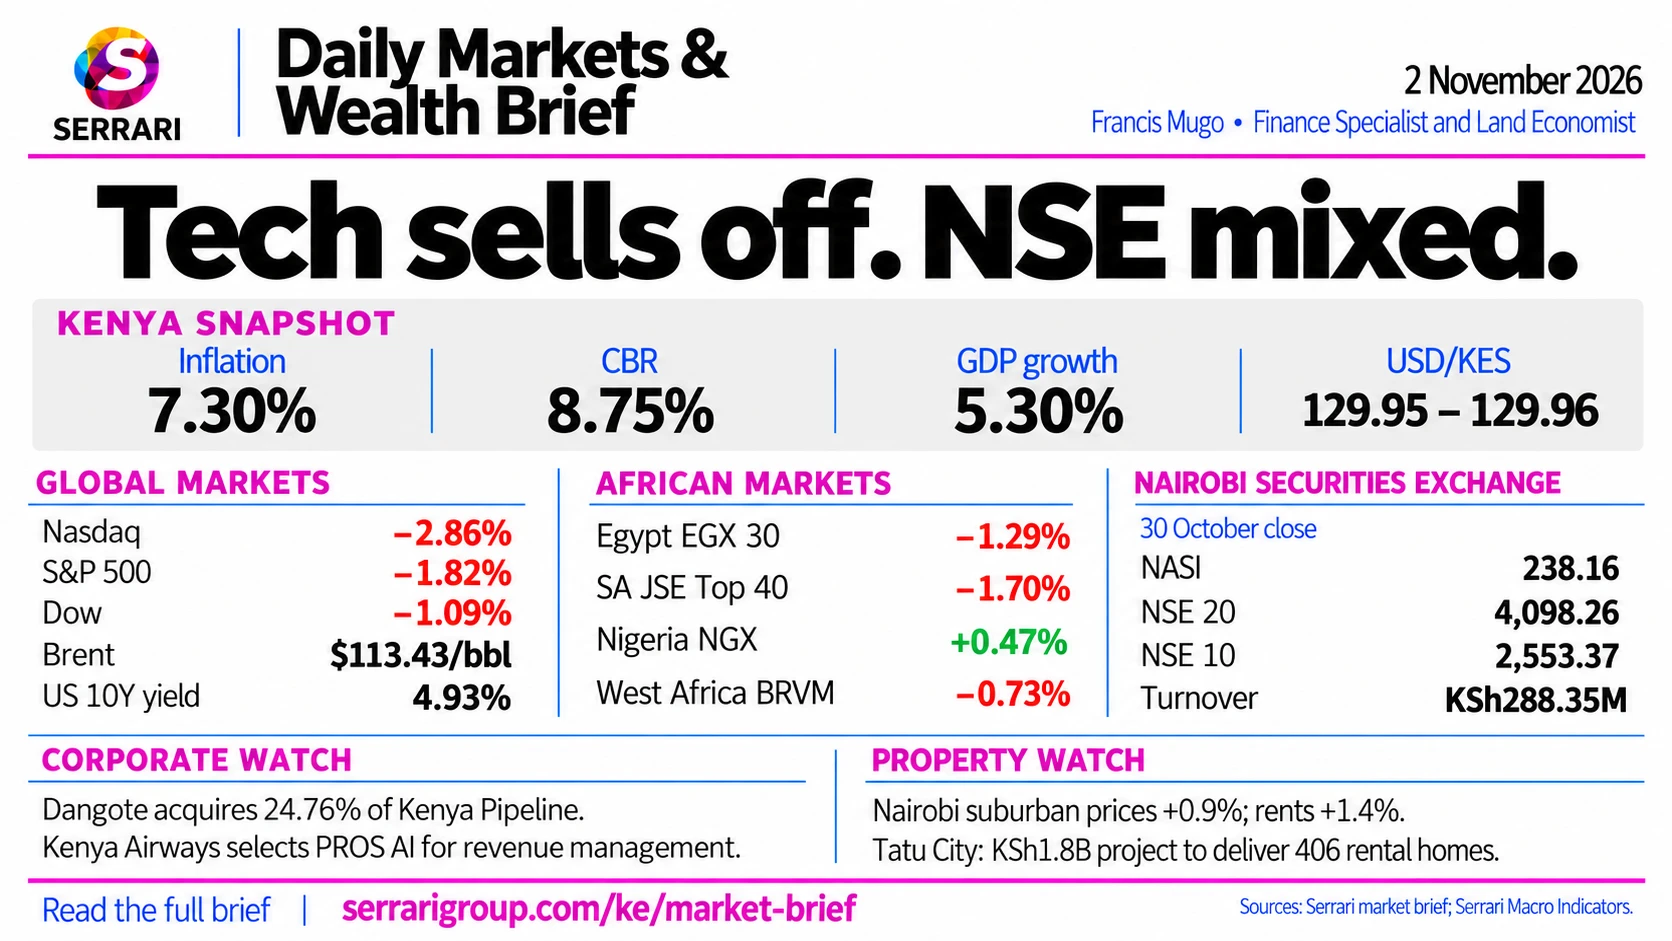
Anxiety over Big Tech’s AI spending sent the Nasdaq down 2.86% and South Korea’s KOSPI down 5.57%, while Brent crude surged to $113.43 a barrel. In Kenya, October inflation rose to 7.3% and Dangote disclosed a 24.76% stake in Kenya Pipeline.

Global Markets
Figures as at · Closing levels for Friday 30 October 2026, as reported in this brief
Global stock markets suffered a brutal, tech-driven sell-off triggered by anxiety over massive artificial intelligence spending and disappointing corporate earnings. Aggressive capital expenditure plans and rare financial misses from Big Tech left investors questioning the timeline for AI returns, prompting a heavy risk-off rotation. Geopolitically driven energy prices soared, with Brent crude surging to $113 a barrel and WTI reaching $104.
Global stocks index snapshot
| Index | Close | Daily change | Key catalyst |
|---|---|---|---|
| Dow Jones Industrial Average (US) | 51,770.31 | -1.09% | Tech flight; defensive rotation into consumer and healthcare |
| S&P 500 (US) | 7,580.07 | -1.82% | Worst single day since June; broke its 100-day moving average |
| Nasdaq Composite (US) | 25,437.00 | -2.86% | Massive cash-burn fears for hyperscalers |
| S&P/TSX Composite (Canada) | N/A | Lower | Dragged down by the broader North American tech rout and trade anxieties |
| STOXX Europe 600 | 646.70 | -0.41% | Tech losses partially offset by soaring energy and defence sectors |
| FTSE 100 (London) | 10,730.00 | +0.07% | Supported by heavily weighted oil majors |
| DAX (Frankfurt) | — | -0.90% | Chip supply chain suppliers led sharp declines |
| Nikkei 225 (Tokyo) | 62,840.00 | -2.81% | BOJ holds rates at 1.25%; chip equipment names plummeted |
| KOSPI (Seoul) | 5,624.53 | -5.57% | Tech-heavy index hammered by the AI spending crisis |
| Hang Seng (Hong Kong) | 23,219.00 | +1.13% | Gained on mainland defensive rotation |
United States
- The AI indigestion: Tech giants suffered a severe valuation bloodbath. Intel plummeted nearly 29%, its worst single-day drop since 1974, after warning of production cash burn and an aggressive revenue miss. Amazon dropped 2% and Alphabet extended its slide following missed projections and ballooning capital commitments.
- Defensive rotation and bonds: Investors exited growth stocks for consumer staples, utilities and healthcare; Walmart and Coca-Cola both gained over 1%. The 10-year Treasury yield eased to 4.93% as money moved into government bonds.
- Crypto Black Friday: Binance suffered a historic $6.3 billion exploit, sending major cryptocurrencies tumbling toward key support levels.
Canada and Latin America
- Resource resilience vs tech drag: Canada’s heavy energy exposure caught a strong bid from the surge in crude and refining margins, but the broader index faced deep pressure from the North American technology rout.
- Geopolitical alignment: The EU and Canada signed a landmark digital trade deal on 30 October, hedging against shifting US trade policy ahead of the US midterm elections.
- Commodity windfalls: Resource-heavy bourses such as Brazil’s B3 and Mexico’s BMV had a mixed session; the premium on global energy and metals volatility partly cushioned the flight from risk assets.
Europe
- Slowing growth: Eurostat flash data showed eurozone Q3 growth slowed to 0.4%, keeping the euro under minor pressure alongside a hawkish ECB stance.
- Semiconductor hit: AI spending anxiety slammed European hardware: ASML, ASM International and BE Semiconductor all fell by more than 5%.
- Energy wins: Third-quarter corporate profits across Europe were propped up by the energy complex, with massive downstream profits at global oil majors.
Asia
- BOJ holds firm: The Bank of Japan kept rates at 1.25%, triggering sharp falls in Japanese tech infrastructure providers such as Lasertec and Ibiden.
- Capex fallout: South Korea’s KOSPI fell over 5%, with Samsung Electronics and SK Hynix dragging it to multi-month lows as foreign capital left tech manufacturing. Over $600 billion in market value was erased across Asian bourses in the single Friday session.
Global forex
- EUR/USD: 1.1172, +0.38% (appreciated). Supported by hawkish ECB signalling and an early departure announcement by Christine Lagarde.
- GBP/USD: 1.3415, +0.11% (appreciated). Sterling holds firm above 1.3400 after absorbing the UK Autumn Budget.
- USD/JPY: 157.10, -0.47% (yen strengthened). A pullback on a safe-haven bid and an unwinding of the global tech carry trade.
- USD/CAD: About 1.3810, flat to mixed. Dragged by the North American tech rout but insulated by surging crude benchmarks.
- USD/MXN: 18.8080, +0.34% (peso appreciated). The peso advanced on stronger-than-expected preliminary Q3 GDP growth of 3.2%.
- USD/CNY: 6.6560, +0.08% (yuan appreciated). The yuan gained on broad US dollar softening.
Sovereign Yields
Figures as at · Closing yields for 30 October 2026, as reported in this brief
Global sovereign yields
| Benchmark | Closing yield | Daily / monthly context | Primary driver |
|---|---|---|---|
| US 10-Year Treasury | 4.93% | Down 6 bps on the day; down ~37 bps in October | Strong safe-haven bid offsetting a record $839B weekly debt auction supply |
| US 2-Year Treasury | 4.59% | Down 6 basis points | Digesting the Fed’s decision to hold benchmark rates at 3.75%–4.00% |
| US 30-Year Bond | 5.31% | Up 1 bp on the day | Supply pressures on the ultra-long end of the curve |
| Germany 10-Year Bund | 3.32% | Down on the day; largest monthly drop since April 2025 | Chief beneficiary of European safe-haven capital flight |
| France 10-Year OAT | 4.95% | Up 4.4 bps | Sharp divergence from Germany due to France’s ballooning fiscal deficit |
| Japan 10-Year JGB | 2.76% | Down 7 basis points | Eased after the Bank of Japan froze its policy rate |
| Canada 10-Year Government | ~3.95% | Tracked the US Treasury decline | Eased alongside falling US yields and cooling short-term local yields |
| Latin America (Brazil/Mexico) | — | Sticky / resilient | Local yields remained high on energy-driven inflation and geopolitical premiums |
Commodities
Figures as at · Settlement prices for 30 October 2026, as reported in this brief
Global commodities
| Commodity | Contract | Close | Daily change | Key driver |
|---|---|---|---|---|
| Brent crude oil | Jan ’27 | $113.43 / bbl | +$2.63 (+2.38%) | Middle East tanker attacks and looming US military strikes |
| WTI crude oil | Dec ’26 | $104.12 / bbl | +$2.12 (+2.08%) | Strong domestic refining demand ahead of the US midterms |
| Natural gas | Dec ’26 | $2.898 / MMBtu | -$0.054 (-1.83%) | One of the lone energy decliners on milder weather forecasts |
| Gold | Dec ’26 | $3,892.40 / oz | -$139.00 (-3.45%) | Violent risk-off liquidation and surging short-term inflation metrics |
| Silver | Dec ’26 | $49.28 / oz | -$2.98 (-5.70%) | Industrial demand worries and gold’s crash |
| Corn | Dec ’26 | $4.4775 / bu | -3.50¢ | Improved Midwest harvest weather balancing global supply |
| Soybeans | Nov ’26 | $12.2225 / bu | +2.50¢ | Dry weather warnings across northern Brazil’s growing regions |
Africa
Figures as at · Closing levels for 30 October 2026, as reported in this brief
Regional performance summary, 30 October 2026. South Africa: equities pull back (-1.70%), rand weakens to 16.71, 10-year yield steady at 8.73%. Nigeria: equities edge up (+0.47%), naira stable at 1,346, Brent surges to $117.64. Egypt: equities decline (-1.29%), pound flat at 56.00, yields spike after a CBE hike. West Africa: BRVM softens (-0.73%), cocoa flat ($5,454), XOF tracks the euro at 585–587.
African sovereign bond yields
| Country | Tenor | Local-currency yield | Context |
|---|---|---|---|
| South Africa | 10-year bond | 8.73% | Near a two-month low on solid fiscal tracking and a stabilising public finance outlook |
| Nigeria | 10-year bond | 16.91% | Sideways to slightly compressed after the central bank’s earlier 3.5% policy rate cut to 23% |
| Nigeria | 30-year bond | 14.65% | Sideways to slightly compressed after the central bank’s earlier 3.5% policy rate cut to 23% |
| Egypt | 1-year T-bill | 25.82% | Upward pressure after the Central Bank of Egypt’s 1% policy rate hike the previous day |
| Egypt | 3-year bond | 24.51% | Upward pressure after the Central Bank of Egypt’s 1% policy rate hike the previous day |
| West Africa (BRVM) | Regional 10-year average | ~7.37%–7.40% | Representative sovereign curves, such as Côte d’Ivoire local debt, steady near mid-7% |
South Africa (JSE and ZAR)
- Equities: The JSE Top 40 tumbled 1.70% to close near 103,823.14, dragged down by a global rotation out of emerging market equities and a mild retreat in safe-haven precious metals.
- Forex: The rand weakened by roughly 0.6% to 0.8%, settling at R16.71 per dollar on safe-haven dollar demand.
- Fixed income: The 10-year government bond yield held firm at 8.73%, near a two-month low, as investors kept confidence in the mid-term fiscal outlook.
Nigeria (NGX and NGN)
- Equities: The NGX All-Share gained 0.47% to close at 254,083.02, supported by a ₦779 billion expansion in market capitalisation led by banking and oil-and-gas heavyweights.
- Forex: The naira closed at 1,346.26 per dollar in the official window. The parallel market premium stayed exceptionally tight at 1,389.00–1,390.00, supported by foreign reserves of over $55 billion.
- Commodities: Brent contracts expired up at $117.64 a barrel (+2.40%) after a tanker attack near the Strait of Hormuz, a fiscal boost to Nigeria’s export revenue that also compounds local subsidy debates.
Egypt (EGX and EGP)
- Equities: The EGX 30 fell 1.29% to 54,224.90 as investors reacted to sudden tightening by the central bank.
- Fixed income: Short-dated treasury yields broke to 25.82% after the Central Bank of Egypt implemented a surprise 1% policy rate hike the previous evening to combat lingering inflation.
- Forex: The pound hovered close to historical lows, closing flat at 55.95–56.00 per dollar.
West Africa (BRVM and softs)
- Equities and forex: The BRVM had a softer session, dropping between 0.73% and 1.33% across regional indexes. The CFA franc (XOF), pegged to the euro, traded between 585 and 587 per dollar.
- Commodities: ICE cocoa futures settled flat at $5,454.00 a tonne. Physical markets in Côte d’Ivoire and Ghana stayed active, and Cameroon’s national board posted firm export gate prices around 3,267 FCFA/kg.
Kenya: NSE and Fixed Income
Figures as at · Nairobi Securities Exchange session data for 30 October 2026, as reported in this brief
Equities
- Market indices: Closed mixed. The NSE All Share Index (NASI) gained 0.23% to 238.16 and the NSE 10 edged up 0.01% to 2,553.37, while the NSE 20 declined 0.33% to 4,098.26 and the Banking Index slipped 0.28% to 271.52.
- Market capitalisation: Rose 0.23% to KES 4.00 trillion (KES 3,996.73 billion).
- Trading activity: Turnover fell 43.56% to KES 288.35 million from KES 510.88 million in the previous session. Share volumes declined 6.27% to 14.11 million shares.
- Top gainers: Sanlam Kenya (Sanlam Allianz Holdings), Family Bank and WPP Scangroup.
- Top losers: Olympia Capital Holdings, Express Kenya and CIC Insurance Group.
- Foreign flows: Foreign participation was low, with net outflows of KES 17.62 million: foreign buys of KES 23.45 million against sales of KES 41.07 million.
Fixed income and yields
- Secondary bond market: Bond turnover declined 16.4% to KES 8.19 billion from KES 9.80 billion in the previous session.
- Kenya 10-year: The benchmark government bond yield held relatively steady around 12.53%.
- Treasury bills: Latest auction / reference rates: 91-day ~8.75%, 182-day ~8.86%, 364-day ~9.03%.
- Central Bank Rate: Held at 8.75% by the Monetary Policy Committee to anchor inflation and stabilise the currency.
Kenya Forex, Macro and Commodities
Figures as at · Central Bank of Kenya indicative rates and KNBS data, as reported in this brief
Central Bank indicative exchange rates (KES)
- US dollar: ~129.95–129.96
- British pound: ~173.20
- Euro: ~144.74
- Japanese yen (100 JPY): ~82.31
Regional and major cross rates
- South African rand: ~7.80 KES
- Ugandan shilling: ~33.43 UGX per KES
- Tanzanian shilling: ~20.32 TZS per KES
- Rwandan franc: ~11.35 RWF per KES
Reserves and inflation
- FX reserves: Roughly USD 14.74 billion, about 5.9 months of import cover.
- Inflation: KNBS data showed annual headline inflation ticked up to 7.3% in October from 6.8% in September, driven by volatile non-core categories such as food, fuel and transport costs.
Export commodities
- Coffee: The NSE concluded its fourth auction of the 2026/2027 season around 30 October, generating a strong Sh1.02 billion. Premium grades attracted top dollar: Grade AA fetched up to $390 (Sh50,664.90) per 50kg bag at premium factories such as Gakuyu-ini.
- Tea: At the Mombasa auction, active buying from Pakistan and Egypt kept the market robust. Prices averaged $2.30 per kg for Sale 42.
- Warehouse receipt reforms: The government advanced the Warehouse Receipt System Amendment Bill, 2026 to Parliament, to harmonise standards and build integrated cross-border agricultural commodity storage within East Africa.
Kenya Corporate News
Figures as at · As reported in this brief
Mergers, acquisitions and corporate moves
- Kenya Pipeline surge: KPC added more than USD 1 billion in market value, extending a major rally, after Aliko Dangote formally disclosed that his group acquired a 24.76% stake through a KSh 42.5 billion block transaction. Sellers included pension funds such as the NSSF and the Public Service Superannuation Fund. Dangote also signalled plans to invest a further USD 1.5 billion to expand Kenya’s regional petroleum pipeline grid.
- Kenya Airways and PROS AI: Kenya Airways selected PROS AI Airline Software to revamp its commercial and pricing systems, deploying PROS Revenue Management Advantage for AI-powered demand forecasting across its network.
- GTBank Kenya: Guaranty Trust Bank Kenya appointed a new Acting Managing Director to steer its local operations.
Regulatory and banking actions
- CBK and struggling lenders: CBK Governor Kamau Thugge told Parliament that two commercial banks failed to meet the 2026 core capital targets. The CBK has summoned the unnamed institutions to explain their recapitalisation and risk-mitigation plans, including for cybersecurity and climate threats.
Supply chain and trade infrastructure
- KRA e-seals: The Kenya Revenue Authority fully rolled out its Multi-Vendor User-Owned Electronic Seals Framework, ending state-owned electronic seals on the Northern Corridor and opening the market to 15 approved private tracking vendors to cut delays and combat cargo theft between Mombasa and the borders.
- Mrima Hill: Mining Cabinet Secretary Hassan Ali Joho confirmed that Chinese mining firms withdrew from bidding on the Mrima Hill niobium and rare earths project, leaving the field to US-backed alternatives. The tender is expected to be awarded in November.
Macro backdrop
- Inflation pressures: KNBS data show annual headline inflation ticked up to 7.3% in October from 6.8% in September, driven by food, fuel and transport costs.
Real Estate
Figures as at · As reported in this brief
The rental tax crackdown
- KRA targets 1 million landlords: The Kenya Revenue Authority launched an enforcement campaign to bring more than one million property owners suspected of concealing or under-reporting rental income into the tax net.
- Mandatory eRITS onboarding: To lift rental tax collection from a baseline of Sh14 billion toward Sh80 billion a year, KRA is treating registration on its Electronic Rental Income Tax System (eRITS) as operationally mandatory. Only about 1,412 landlords had previously onboarded.
Compulsory land acquisition
- Wajir air base: The National Land Commission gazetted the state’s intent to compulsorily acquire a 0.8401-hectare plot (Wajir Township Block 2/1424) for the Ministry of Defence under Section 110 of the Land Act, for a new military forward operating airbase.
Market trends: suburbs vs satellite towns
- A structural split: Quarterly indicators compiled by Nairobi Real Estate (NRE) show premium Nairobi suburban price indices up 0.9% and suburban rents up 1.4%, pushing the average rent for a suburban detached home past KSh 200,000 a month. Satellite town price indices softened 0.6% on peripheral sprawl and rising transport and fuel costs.
- Macro headwinds: Legal clarity on the Housing Levy improved planning certainty, but sentiment remains constrained by rising inflation (6.8%–7.3%) and a weaker shilling at roughly KES 129.8–129.9 per dollar, pushing investors toward cash and instalment financing rather than bank mortgages.
Courts and projects
- Githunguri housing halted: The Environment and Land Court (Justice Jacqueline Mogeni) halted construction on a 58-acre affordable housing site in Githunguri, Kiambu County (Githunguri/Githunguri/T. 801), pending a petition over its protected Mau Mau and cultural heritage.
- Tatu City rental housing: IHS broke ground on a KSh 1.8 billion rental project, Muzi Enzi, in Tatu City to deliver 406 affordable rental apartments, with first tenants expected in 2028.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro dataForeign exchange reserves
$14.74bn
~5.9 months of import cover
As at
Central Bank of Kenya, as reported in this brief
Foreign exchange
USD / KES
129.95
129.95–129.96
As at
Central Bank of Kenya indicative rateGBP / KES
173.20
As at
Central Bank of Kenya indicative rateEUR / KES
144.74
As at
Central Bank of Kenya indicative rate
Equities
NSE All-Share (NASI)
238.16
+0.23%
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,098.26
-0.33%
As at
Nairobi Securities Exchange, as reported in this briefNSE 10
2,553.37
+0.01%
As at
Nairobi Securities Exchange, as reported in this briefNSE Banking Index
271.52
-0.28%
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KES 288.35M
-43.56% from KES 510.88M
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KES 4.00tn
KES 3,996.73bn, +0.23%
As at
Nairobi Securities Exchange, as reported in this briefForeign net flows
-KES 17.62M
Buys KES 23.45M, sales KES 41.07M
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
Held unchanged.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this briefKenya 10-year bond
12.53%
Relatively steady
As at
As reported in this brief91-day T-bill
8.75%
~8.75%
As at
Latest auction / reference rate, as reported in this brief182-day T-bill
8.86%
~8.86%
As at
Latest auction / reference rate, as reported in this brief364-day T-bill
9.03%
~9.03%
As at
Latest auction / reference rate, as reported in this brief
At a glance
- 1AI spending anxiety turned into a rout: Intel fell nearly 29%, the Nasdaq lost 2.86%, the S&P 500 had its worst day since June and over $600 billion was erased across Asian bourses.
- 2Kenyan inflation rose to 7.3% in October from 6.8% in September, driven by food, fuel and transport, while the Central Bank Rate stays at 8.75%.
- 3Dangote’s group disclosed a 24.76% stake in Kenya Pipeline, bought in a KSh 42.5 billion block from pension funds including the NSSF, and signalled a further $1.5 billion for the regional pipeline grid.
Sources
- Serrari Group desk compilation, 2 November 2026; Markets Snapshot – 30 October 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data