
3 November 2026
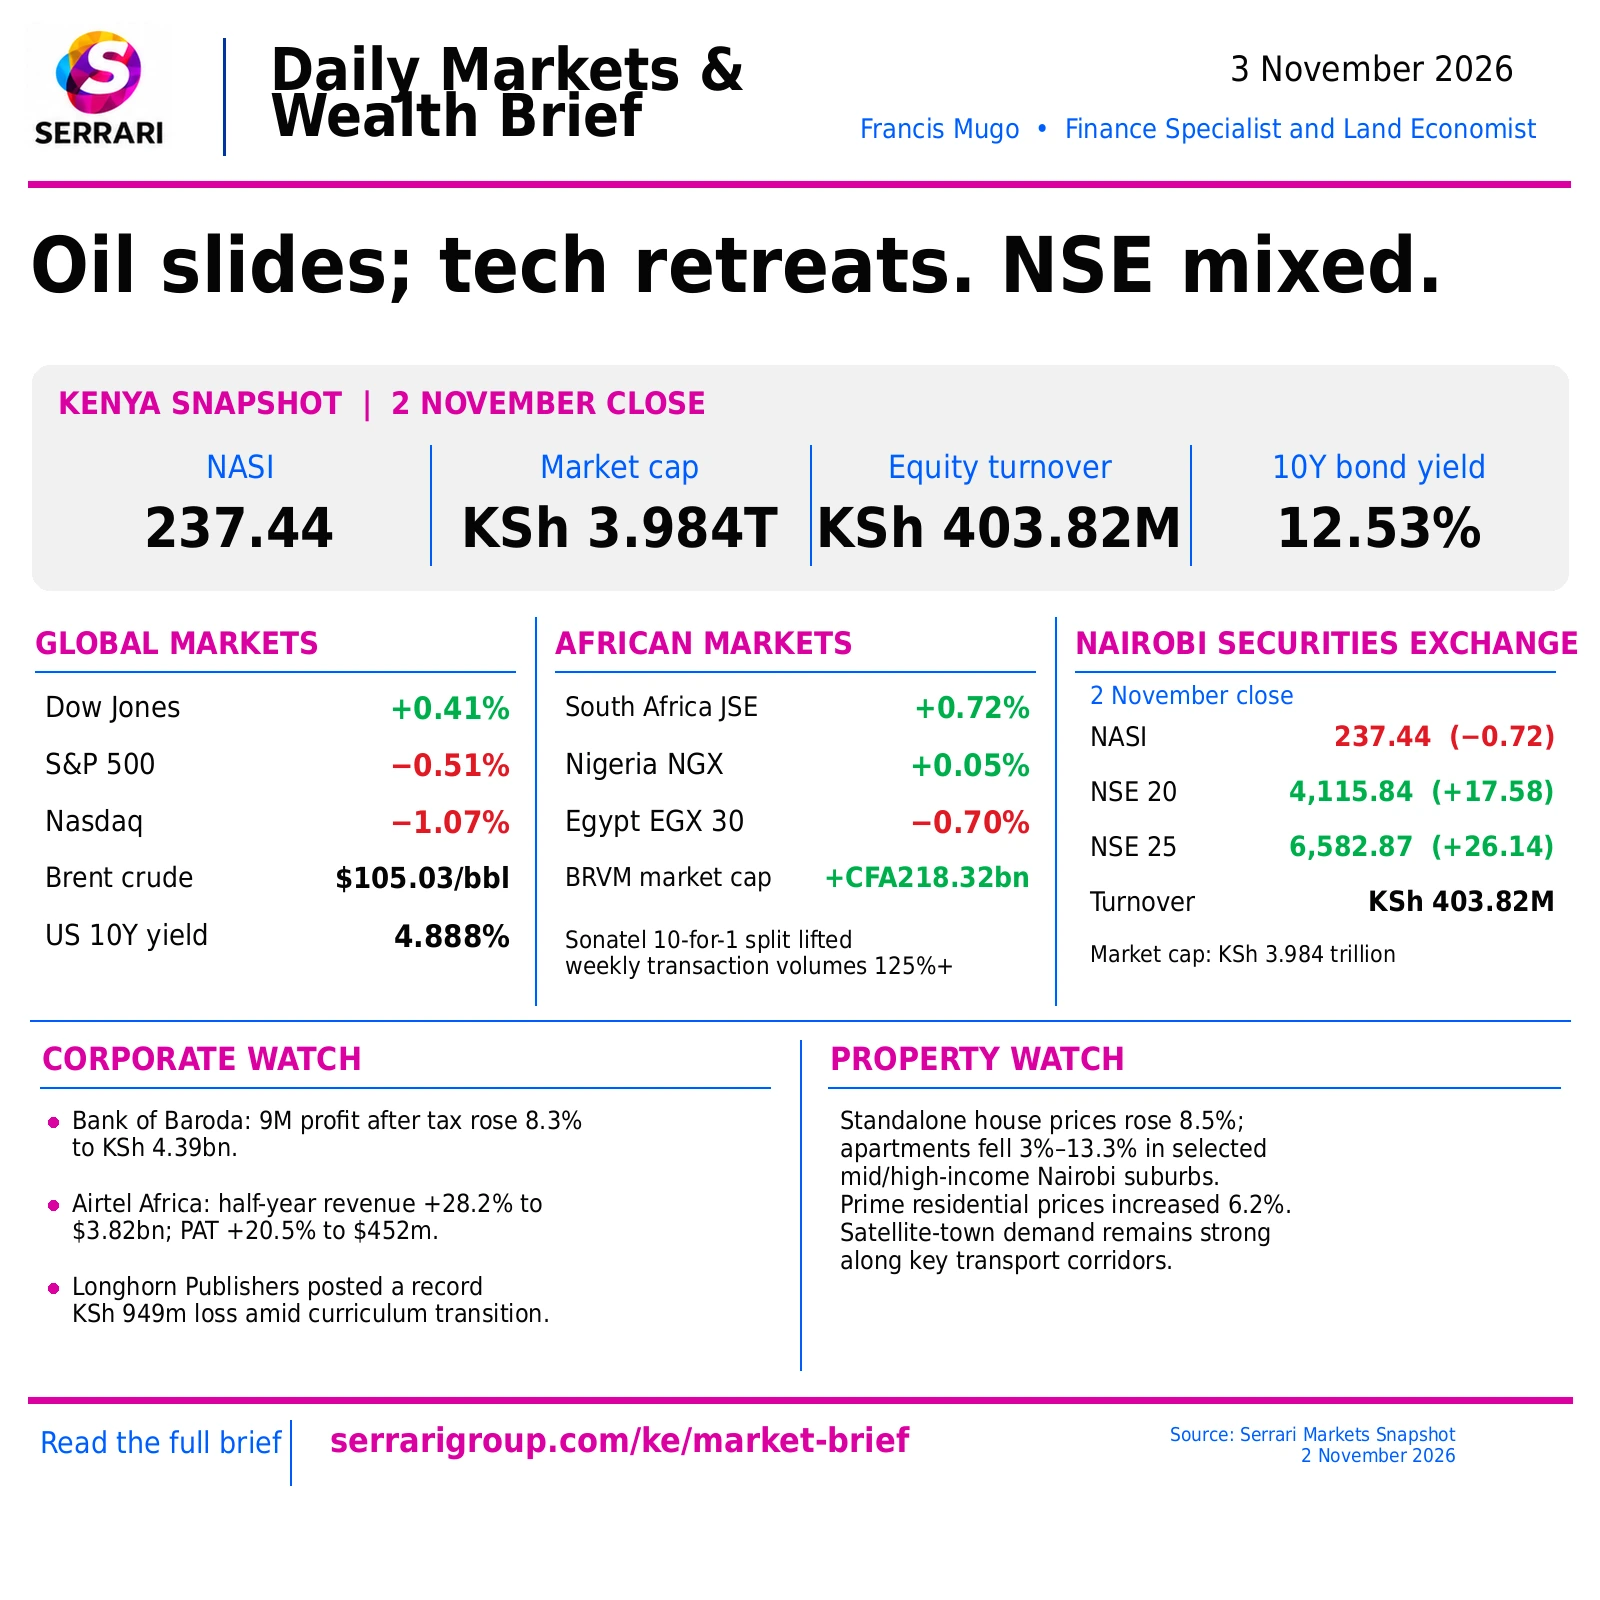
Oil’s war premium collapsed, with Brent down 7.41% to $105.03 and WTI down 7.36% to $96.46, while an afternoon tech reversal left the Nasdaq 1.07% lower. In Nairobi, the NASI eased 0.72 to 237.44 as turnover rose to KSh 403.82 million.

Global Markets
Figures as at · Closing levels for Monday 2 November 2026, as reported in this brief
Major indices
| Index | Close | Change | Catalyst |
|---|---|---|---|
| Dow Jones Industrial Average | 51,983.98 | +0.41% | Defensive blue chips and travel-sector relief |
| S&P 500 | 7,541.40 | −0.51% | An early 1.1% rally was wiped out by tech |
| Nasdaq Composite | 25,164.32 | −1.07% | Afternoon tech reversal put the Nasdaq 100 in a correction |
| Canada — S&P/TSX Composite | 36,035.00 | +1.16% | Up over 400 points on industrial strength and trade progress |
| Stoxx Europe 600 | 621.58 | −0.10% | Falling energy stocks offset stronger factory PMIs |
| Germany — DAX | 25,787.75 | +0.20% | Steadied after the previous week’s steep declines |
| UK — FTSE 100 | 10,695.30 | +0.05% | Muted as slumping oil majors weighed |
| Japan — Nikkei 225 | 63,081.86 | −0.20% | Kioxia plunged 15.8% |
| South Korea — KOSPI | 5,859.08 | +2.20% | Tech hardware rebound led by SK Hynix (+4.2%) |
| Hong Kong — Hang Seng | 27,266.38 | +0.60% | Talk of emergency market stability measures |
| Brazil — Ibovespa | N/A | 0.00% | Closed for All Souls’ Day |
| Mexico — BMV | N/A | Mixed | High industrial park occupancy offset cooling commodities |
United States
- Crude collapse: The geopolitical war premium dissolved on reports that the Trump administration favours diplomatic negotiations over military strikes on Iran. WTI futures plunged 7.36% to $96.46 a barrel, sparking a rally in fuel-sensitive transport stocks; United Airlines gained 6.5%.
- A $115 billion tech deal: Marvell Technology fell 7.3% after announcing an all-stock acquisition of cloud data infrastructure designer Lumentum for roughly $115 billion. Lumentum fell 12.8% as traders digested the 4.5-to-1 share exchange.
- AI monetisation worries: The Nasdaq reversed early gains in afternoon trading as investors pulled money out of growth hardware ahead of Apple’s late earnings, leaving the Nasdaq 100 10.4% below its October record. Anthropic filed an updated S-1 disclosing an $81 billion net loss, driven by convertible debt, on $16 billion of first-half revenue.
Canada and Latin America
- TSX: Toronto rebounded by more than 180 points, insulated from the US tech rout, on signals that a new Canada–US trade framework is finalised ahead of tomorrow’s US elections. Methanex rose on resilient operating cash flow, while TFI International fell 17% on a weak free-cash-flow forecast.
- Canadian dollar: The Bank of Canada recorded the loonie at 71.54 US cents, down from Friday’s 71.63, as the oil slump outweighed the trade news.
- Latin America: Brazil’s B3 was closed for All Souls’ Day, leaving attention on Mexico and Chile. Analysts highlighted the region’s resilience to recent shocks such as the brief closure of the Strait of Hormuz, citing record local exports, little public unrest and stable domestic demand.
Europe and Asia-Pacific
- Europe: Brent’s slide below $109 a barrel hit European oil and gas majors, which led losses, but stronger-than-expected October manufacturing PMIs helped bourses erase early declines. French 10-year bonds weakened as yields decoupled from Germany’s on worries over France’s political deadlock and deficit.
- South Korea: The KOSPI led the regional recovery: SK Hynix rose 4.2% on new long-term memory supply agreements and Samsung Electronics 1.8%.
- Japan: The Nikkei 225 slipped as memory maker Kioxia Holdings fell nearly 16% on a disappointing profit forecast.
- China: The Shanghai Composite rose 1.2% after the People’s Bank of China and securities regulators held emergency meetings with major financial institutions on direct capital market support.
Forex
- EUR/USD: 1.1204, up 0.35%, on an oil-driven fall in the dollar and firm ECB rate expectations.
- GBP/USD: 1.3415, up 0.11%, as markets absorbed the post-Budget fiscal framework.
- USD/JPY: 157.75, down 0.41%, as the yen caught a safe-haven bid from unwinding tech carry trades.
- USD/CAD: 1.3980, up 0.52%, as the historic 7.6% crash in crude stripped the Canadian dollar’s commodity premium.
- USD/MXN: 18.8080, flat, steadied by strong industrial exports and solid preliminary third-quarter GDP.
- USD/CNY: 6.6560, with the yuan up 0.08% on regulatory signals targeting capital market stability.
Global Yields
Figures as at · Yields for 2 November 2026, as reported in this brief
Government bond yields
| Bond | Yield | Change | Driver |
|---|---|---|---|
| US 10-year Treasury | 4.888% | −4.1 bps | Easing energy prices and a defensive flight from tech |
| US 2-year Treasury | 4.583% | Down slightly | Steady as traders waited for the midterm elections |
| US 30-year bond | 5.256% | −5.3 bps | Led long-end gains as inflation expectations cooled |
| Canada 10-year | 3.764% | −4.0 bps | Tracked US yields; spread compressed to −112.7 bps |
| UK 10-year Gilt | 5.198% | Down sharply | An eight-week low as the oil drop softened inflation forecasts |
| Germany 10-year Bund | ~3.29% | Eased lower | Europe’s core safe-haven asset |
| France 10-year OAT | ~4.95% | Ticked higher | Defied the global trend on fears over its structural deficit |
| Japan 10-year JGB | 2.774% | Down on the session | Steadied lower after the Bank of Japan’s rate freeze |
| Brazil / Mexico 10-year | — | Sticky | Elevated as central banks balanced global rate shifts |
Commodities
Figures as at · Closing prices for 2 November 2026, as reported in this brief
Closing prices
| Contract | Close | Change | Driver |
|---|---|---|---|
| Brent crude (Jan ’27) | $105.03 / bbl | −$8.40 (−7.41%) | Rapid de-escalation of the Middle East shipping threat |
| WTI crude (Dec ’26) | $96.46 / bbl | −$7.66 (−7.36%) | War premium unwound; lowest in two months |
| Natural gas (Dec ’26) | $2.855 / MMBtu | −$0.043 (−1.48%) | Mild autumn forecasts cap demand |
| Gold (Dec ’26) | $3,912.10 / oz | +$19.70 (+0.51%) | Mild safe-haven bounce after October’s margin squeeze |
| Silver (Dec ’26) | $49.85 / oz | +$0.57 (+1.16%) | Steadied with gold on industrial bargain-hunting |
| Copper (Dec ’26) | $4.320 / lb | −0.85% | Capped by weaker Chinese weekend manufacturing data |
| Corn (Dec ’26) | $4.4125 / bu | −6.50¢ | Rapid Midwest harvest progress |
| Soybeans (Nov ’26) | $12.1550 / bu | −6.75¢ | Welcome rains in central Brazil |
Africa
Figures as at · Closing levels for 2 November 2026, as reported in this brief
African markets opened the month on a dynamic note as Brent tumbled more than 4% back towards $108–$109 a barrel on progress in US–Iran talks, reversing the previous week’s patterns across indices, currencies and yields.
Major African indices
| Index | Close | Change |
|---|---|---|
| South Africa — JSE All Share | near 108,394 | +0.72% |
| Nigeria — NGX All-Share | 254,424.92 | +0.05% |
| Egypt — EGX 30 | 48,816.24 | −0.70% |
| West Africa — BRVM market capitalisation | — | +CFA 218.32 billion |
Business news
- South Africa: The US reviewed South Africa’s AGOA eligibility on its deadline day; Trade Minister Parks Tau said the country is prepared for any outcome and would have a 60-day window to resolve concerns before tariffs apply. PNE Group sold a 250 MW Free State solar project to a South African independent power producer, and Turpaz Industries bought 70% of flavour maker Sensory FX.
- Nigeria: Australia’s Macro Metals agreed to sell KCM Mining, holder of the Agbaja iron ore project in Kogi State, to RSIN Group for $5.67 million. At the CIBN investiture, Keystone Bank chair Dr Lady Ada Chukwudozie and NESG CEO Dr Tayo Aduloju called for more enterprise financing for manufacturing, and Cross River State rolled out low-interest financing and free business registration for more than 5,350 enterprise owners.
- Egypt: Egypt signed a $1 billion World Bank financing agreement for the second phase of its Development Policy Financing programme, targeting state-enterprise governance, private investment and carbon credit markets. TMR signed an exclusive franchise with Kitopi to bring Catch 22 and Awani to Egypt, and local mutual funds crossed EGP 500 billion in the third quarter.
- West Africa: Business leaders led by Heirs Holdings chair Tony Elumelu are preparing the West Africa Integration and Investment Summit, targeting a $15 billion project portfolio by mid-November. The BRVM gained CFA 218.32 billion in market capitalisation as Sonatel’s 10-for-1 stock split lifted weekly transaction volumes by more than 125%.
Markets
- South Africa: The rand strengthened about 0.4% to R16.64 per dollar on improved October manufacturing sentiment and a 10.4% rise in new vehicle sales. The benchmark 2035 government bond yield fell 2.5 basis points to 8.565%.
- Nigeria: The NGX All-Share hit a record as market capitalisation rose ₦81.44 billion to ₦165.20 trillion, supported by third-quarter results including MTN Nigeria’s pre-tax profit of ₦1.80 trillion. The naira held at ₦1,346.26 per dollar. Brent’s retreat to $108.48–$109.96, from Friday’s $113.43 expiry settlement, eased landing costs for refined products.
- Egypt: The EGX 30 fell another 0.70% on turnover of EGP 10 billion, with international investors the only net sellers after the central bank’s rate defence. Mopco fell 6.1% and Abu Qir Fertilizers 4.7%, while Telecom Egypt rose 3.1% and CIB 2.9%.
- West Africa: Trading was muted. The CFA franc held at ₣585–587 per dollar with the euro, cash and farmgate export hubs in Côte d’Ivoire and Ghana saw steady supply, and attention turned to the Africa Energy Bank’s launch in January 2027.
Sovereign yields
- South Africa: The 10-year R2035 was 8.56%, down sharply (−17 bps).
- Nigeria: The 10-year was 16.88%, down 3 basis points.
- Egypt: The 1-year bill was 25.75% and the 3-year bond 24.48%, easing about 7 basis points.
- West Africa: The regional 10-year average was about 7.35%–7.38%, stable to soft (−2 bps).
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for Monday 2 November 2026, as reported in this brief
Kenyan market figures are the 2 November close.
NSE indices
| Index | Close | Change |
|---|---|---|
| NSE All-Share (NASI) | 237.44 | −0.72 |
| NSE 20-Share | 4,115.84 | +17.58 |
| NSE 25-Share | 6,582.87 | +26.14 |
| NSE 10-Share | 2,562.30 | +8.93 |
| Banking Sector Index | 272.75 | +1.23 |
Wealth and liquidity
- Market capitalisation: Investor wealth fell KSh 11.93 billion to KSh 3.984 trillion.
- Equity turnover: Rose KSh 115.47 million to KSh 403.82 million.
- Banking index: Family Bank has joined the NSE Banking Index, which now covers 12 listed banks.
Government securities
- Treasury bills: At the latest CBK auction the 91-day bill averaged 8.7498% (issue 2706/091), the 182-day 8.8508% (2680/182) and the 364-day 9.0288% (2635/364).
- Short and medium bonds: Secondary yields were 9.11% on the 2-year, 10.39% on the 3-year and 9.24% on the 5-year.
- Longer bonds: FXD3/2019/15 (7.8 years to maturity) yielded 11.20% in the secondary market against about 11.10% net indicative at auction. The 10-year was 12.5300%, and FXD1/2026/30 (29.5 years) about 11.25% net indicative.
Kenya Corporate News
Figures as at · As reported in this brief
Boardroom changes
- KenGen: John Mosonik Kipngetich was named chairman to drive the G2G 2034 energy strategy, following the appointment of Ronoh Kibet as chief executive from 1 February 2027.
- Standard Group: Dr Naim Bilal Yaseen takes over as substantive group CEO from John Bundotich, who had been acting.
- Britam Holdings: Former Ernst & Young senior partner Celestine Munda is the new substantive board chair, guiding the ASCEND 2026–2030 strategy.
- Diamond Trust Bank: Moved its local corporate hub to a new branch on Makadara Road in Old Town.
Results and deals
- Bank of Baroda (Kenya): Nine-month profit after tax rose 8.3% to KSh 4.39 billion on a 24.9% rise in net interest income, despite a KSh 700 million exceptional charge and doubled loan loss provisions.
- Airtel Africa: Half-year revenue rose 28.2% to $3.82 billion and profit after tax 20.5% to $452 million; mobile money users rose 22.4% to more than 60.9 million.
- Longhorn Publishers: Posted a record KSh 949 million loss on write-offs and disruption from the end of the 8-4-4 curriculum.
- Devki Group: Narendra Raval committed more than KSh 200 billion to new cement and steel plants.
- Olympia Capital Holdings: The NSE’s top weekly gainer, up 175.6% on local investor interest.
Legal
- Trusts: The Business Registration Service opened stakeholder consultations on implementing the new Trust Administration Act, 2026.
- Money laundering fines: The High Court ordered companies including Saika Two Estate Developers and Testimony Enterprises to pay KSh 8 million fines within 14 days under anti-money-laundering and FATF rules.
Kenya Economy and Infrastructure
Figures as at · As reported in this brief
Macroeconomy
- Inflation: Inflation rose to 7.3% in October from 6.8% in September, driven by a 17.1% rise in transport costs and a 10.2% jump in food prices, close to the top of the Central Bank of Kenya’s 7.5% ceiling. The fuel shock is expected to keep the Monetary Policy Committee on hold in December.
- IMF: Ahead of bilateral talks, the IMF urged the government to broaden the tax base and remove exemptions rather than raise headline rates.
- Isiolo–Mandera road: The World Bank confirmed the project has passed 60% completion. Backed by KSh 168.2 billion ($1.3 billion) of World Bank funding, it remains on track for 2030.
Industry, environment and jobs
- Industrialisation Summit: Trade and Industry CS Lee Kinyanjui opened preparations for the 2026 summit at KICC, with the state aiming to lift manufacturing’s share of GDP from 7.1% to 15% by 2027.
- KEWASIP: The Ministry of Environment launched the KSh 200 billion, World Bank-backed Kenya Watershed Services Improvement Project to restore 200,000 hectares of degraded land across 12 counties.
- Public internships: The Public Service Commission directed state corporations and public universities to expand the Public Service Internship Programme from 8,000 to 50,000 interns by January 2027.
Real Estate
Figures as at · As reported in this brief
The top of the market
- Conservancy estates: Wealthy buyers are moving from Nairobi 100x50 ft plots to large Safari Estates in wildlife conservancies. Lolldaiga Conservancy in Nanyuki has opened plots of 15 to 233 acres, priced from KSh 51 million ($395,000).
- Conservation premiums: At Naretoi, plots once valued at $250,000–$400,000 are asking up to $2.2 million on resale.
Houses up, apartments soften
- Overall: KMRC and HassConsult data show residential prices up 4.8%, but the growth is uneven.
- Standalone houses: Prices rose 8.5% on demand for space and security.
- Apartments: Prices fell 3% to 13.3% in mid- to high-income Nairobi suburbs such as Westlands (−7.9%) and Upper Hill (−6.8%), widening the window for middle-income renters to buy.
- Prime: Knight Frank reports prime residential prices up 6.2%.
Risks and policy
- Costly gambles: Developers say many Kenyans buying land or building incrementally face budget overruns from job disruption and shifting material prices. An Auditor-General report found 269 of 394 ongoing public housing and infrastructure projects lack complete or verifiable land ownership documents.
- Institutional capital: The Kenya Property Developers Association met the NSE and lenders including Co-op Bank on moving from speculative local capital to institutional structures. The Finance Act 2026 removed the 15% corporate tax rate for developers and VAT exemptions on construction inputs, and the Parliamentary Budget Office flagged a KSh 118 billion funding gap in the Affordable Housing sub-programme.
Satellite towns
- Transport corridors: Investment keeps clustering in Juja, Ruiru, Kitengela, Syokimau and Athi River. With upgrades to the Nairobi Expressway, the Eastern Bypass and the Kenol–Sagana–Marua highway, plots priced at KSh 500,000 to KSh 2 million see the highest absorption, outperforming city listings.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Equities
NSE All-Share (NASI)
237.44
−0.72
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,115.84
+17.58
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,582.87
+26.14
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 403.82 million
+KSh 115.47 million
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KSh 3.984 trillion
−KSh 11.93 billion
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee decision of 7 October 202691-day T-bill
8.7498%
As at
Latest Central Bank of Kenya auction (issue 2706/091), as reported in this brief182-day T-bill
8.8508%
As at
Latest Central Bank of Kenya auction (issue 2680/182), as reported in this brief364-day T-bill
9.0288%
As at
Latest Central Bank of Kenya auction (issue 2635/364), as reported in this briefKenya 2-year bond
9.11%
As at
Secondary market yield, as reported in this briefKenya 5-year bond
9.24%
As at
Secondary market yield, as reported in this briefKenya 10-year bond
12.53%
As at
Secondary market yield, as reported in this brief
At a glance
- 1Oil’s war premium dissolved as Washington favoured talks with Iran: Brent fell $8.40 (7.41%) to $105.03 and WTI 7.36% to $96.46, while the Nasdaq 100 closed 10.4% below its October record.
- 2On the NSE, the NASI eased 0.72 to 237.44 while the NSE 20 rose 17.58 to 4,115.84. Market capitalisation fell KSh 11.93 billion to KSh 3.984 trillion as turnover rose KSh 115.47 million to KSh 403.82 million.
- 3Bank of Baroda’s nine-month profit after tax rose 8.3% to KSh 4.39 billion and Airtel Africa’s half-year revenue rose 28.2% to $3.82 billion, while Longhorn Publishers posted a record KSh 949 million loss.
Sources
- Serrari Group desk compilation, 3 November 2026; Markets Snapshot – 2 November 2026
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data