
4 November 2026
Oil falls as Brent closes at US$104.77, while NSE equity turnover surges to KSh 107.75 billion alongside Nedbank’s NCBA acquisition. KenGen appoints John Mosonik as chairman, and the CMA proposes a KSh 150,000 REIT conversion fee.

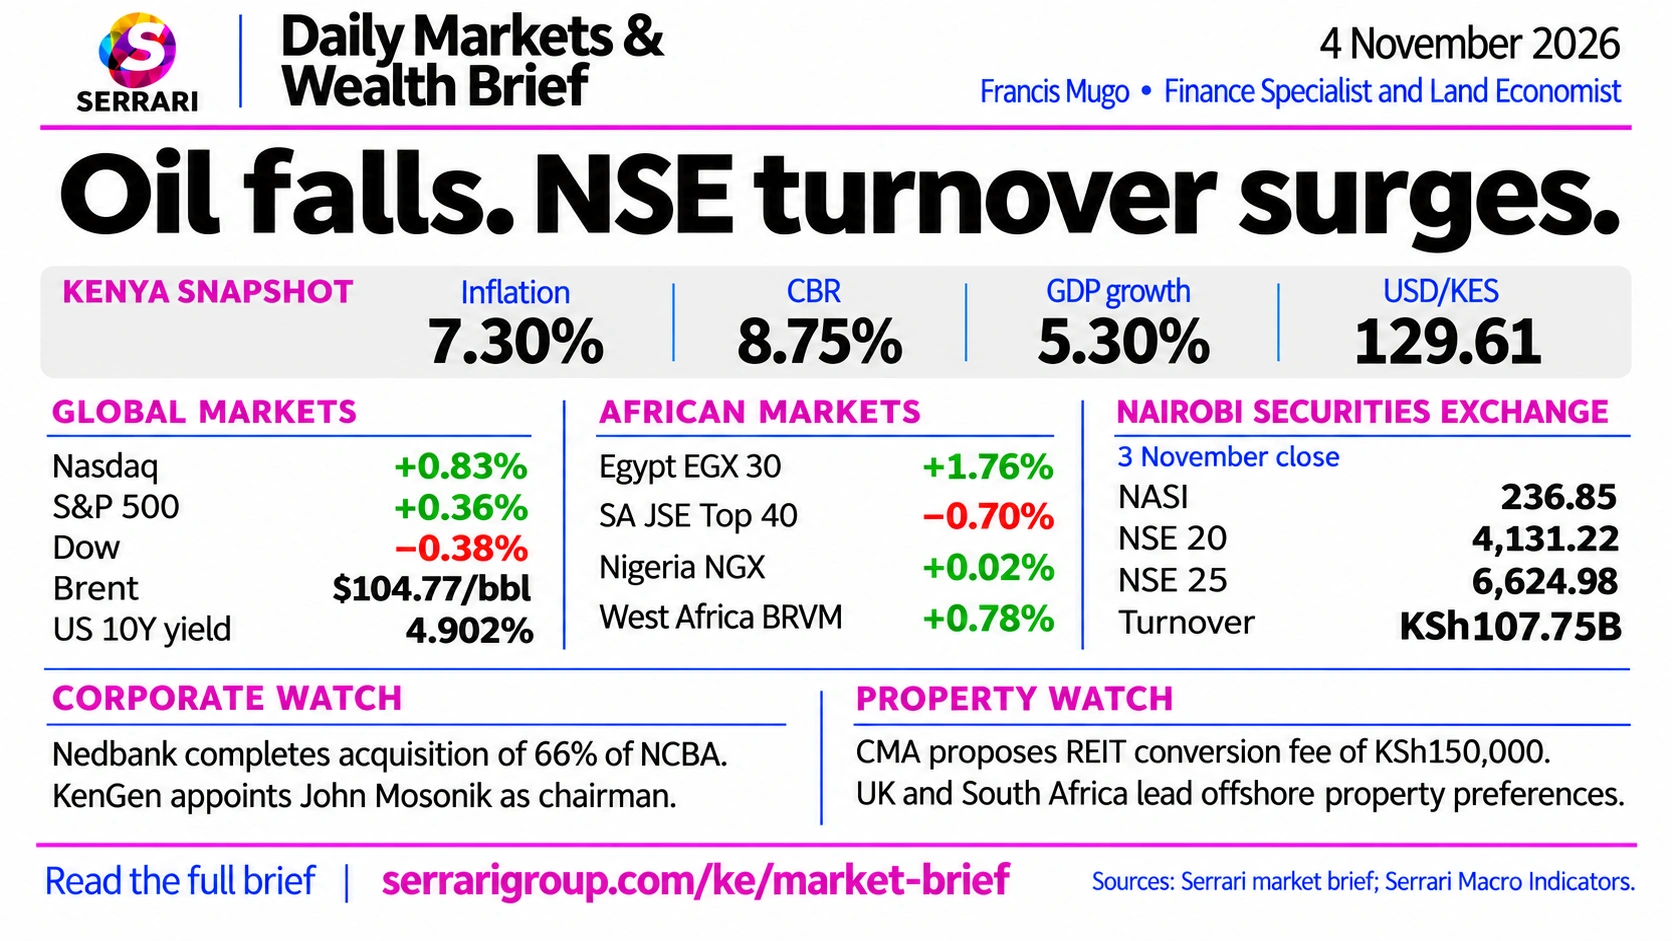
Global Markets
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
US midterm elections, diplomatic signals involving the US and Iran, and a sharp fall in crude oil shaped a mixed, risk-sensitive session.
1. United States (Wall Street)
- US indices: The S&P 500 gained 0.36% to 7,568.92 and the Nasdaq rose 0.83% to 25,372.01, while the Dow fell 0.38% to 51,786.72.
- Movers: Major moves included steep drops for Marvell Technology, Lumentum, and Oracle, contrasted by a surge in IDEXX Laboratories; after-hours, Apple slipped on memory costs while Tesla and SpaceX sentiment dipped on midterm counts.
2. Canada
- S&P/TSX Composite Index: Closed down -0.75% at 35,532.28, pressured by broader North American tech caution and energy sector declines
3. Latin America
- Market Tone: Regional assets traded defensively, impacted by falling crude oil prices affecting energy exporters and cautious positioning ahead of U.S. elections, though lower energy costs helped ease inflation pressures.
4. Europe
- STOXX Europe 600: Closed down -0.58% at 645.66. Energy majors like BP and Shell dropped on U.S.-Iran diplomatic hopes, travel stocks like Ryanair and Lufthansa gained from lower fuel costs, Alstom plunged on a profit cut, and Belgium saw widening bond spreads following political developments.
5. Asia
- Asian indices: The detailed index table reports the Nikkei 225 at 63,081.86, down 4.44%, and KOSPI at 5,648.79, down 3.90%.
- Macro: The Reserve Bank of Australia enacted a rate hike with dovish guidance, while the Bank of Japan monitored currency and wage trends.
Global Equity Indices
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
Closing levels and moves from the supplied 3 November index table.
| Market | Benchmark | Close | Net change | Daily change |
|---|---|---|---|---|
| United States | S&P 500 | 7,568.92 | +27.52 | +0.36% |
| United States | Nasdaq Composite | 25,372.01 | +207.65 | +0.83% |
| United States | Dow Jones Industrial Average | 51,786.72 | −197.26 | −0.38% |
| Canada | S&P/TSX Composite | 35,532.28 | −268.81 | −0.75% |
| Europe | STOXX Europe 600 | 645.66 | −3.78 | −0.58% |
| United Kingdom | FTSE 100 | 10,638.43 | −122.57 | −1.14% |
| Germany | DAX | 25,864.62 | −116.85 | −0.45% |
| France | CAC 40 | 8,020.31 | −27.39 | −0.34% |
| Japan | Nikkei 225 | 63,081.86 | −2,799.77 | −4.44% |
| South Korea | KOSPI | 5,648.79 | −220.57 | −3.90% |
| Hong Kong | Hang Seng | 23,498.11 | −27.86 | −0.12% |
| China | CSI 300 | 4,010.35 | +1.60 | +0.04% |
Sovereign Yields & Kenya Fixed Income
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
| Market | Government security | Yield | Daily move |
|---|---|---|---|
| United States | 10-year Treasury | 4.902% | −4.8 bps |
| United States | 2-year Treasury | 4.550% | −6.0 bps |
| Germany | 10-year Bund | 3.300% | Flat / tighter |
| United Kingdom | 10-year gilt | 5.250% | +5.0 bps |
| Canada | 10-year government bond | 4.120% | −3.5 bps |
| Brazil | 10-year sovereign | 12.85% | Unchanged |
| Japan | 10-year JGB | 0.945% | −2.0 bps |
Global bond drivers
- United States and Canada: Election uncertainty supports a flight to safety, while falling oil and weaker equity futures influence rate expectations.
- Europe: Lower energy prices ease inflation spreads; UK gilt yields rise on post-budget supply concerns.
- Japan and Brazil: Asian equity losses support Japanese government bonds, while Brazilian sovereign yields remain broadly flat ahead of US election results.
Kenya Treasury bills
- 91-day: 8.7498%, flat at the most recent auction.
- 182-day: 8.8508%, with a supplied weekly move of −0.008%.
- 364-day: 9.0288%, with a supplied weekly move of +0.002%.
Kenya Treasury bond curve
- Benchmark yields: 2-year 9.110%; 3-year 10.390%; 5-year 9.123%; 10-year 12.530%; 25-year 13.620%.
- Curve and flows: The 10-year–2-year spread is 342 basis points; over KSh 1 trillion has flowed into government fixed-income securities over the trailing four months.
- 3-year benchmark: The brief reports a 6-basis-point dip in secondary trading.
Kenya fixed-income dynamics
- Duration Appetite: Shorter maturities (under 6 years) continue to draw the highest volume from domestic asset managers trying to balance solid yield with lower interest rate risk.
- Macro Environment: Institutional appetite for long bonds remains measured given the large KES 1.03 trillion net domestic borrowing target for FY2026/27.
- Credit Context: Kenya’s credit status sits steady at S&P: B / Moody's: B3 / Fitch: B-.
Foreign Exchange
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
United States & Canada
- The Dollar Under Pressure: The broader macro sentiment saw the dollar broadly lower against major Group-of-10 currencies, hit by election-induced flight to quality that favoured bonds over equities and cash.
- Canadian dollar (USD/CAD): Held steady near 1.40 CAD per US dollar; broader dollar weakness provided support, while sharply lower crude oil capped upside for the energy-linked currency.
Europe & United Kingdom
- Euro (EUR/USD): The Euro capitalized on the softer greenback, firming 0.4% to close around $1.1237. Plunging crude oil costs also improved the Eurozone's macro outlook by directly compressing structural inflation fears.
- British Pound (GBP/USD): Sterling pushed higher, breaking back above $1.3400. This move came as a softening dollar counteracted the localized fiscal anxieties that had built up in the wake of the recent UK autumn budget.
- Swiss Franc (USD/CHF): The Swiss Franc was the top gainer against the dollar, appreciating 0.7%. This highlighted its traditional status as a pure defensive safe haven during Western political realignments
Asia-Pacific
- Japanese Yen (USD/JPY): The Yen posted a significant safe-haven rally, gaining 0.6% to trade at 157.77 per dollar. The absolute rout across regional Asian stock markets forced investors out of equities and back into cash and local fixed-income paper, accelerating the unwind of popular carry trades.
- Chinese Yuan (USD/CNY): In a major regulatory twist, the People's Bank of China (PBOC) announced it will raise its foreign exchange reserve requirement ratio by 2 percentage points to 6% starting November 15. The macro-prudential tool effectively freezes $20 billion to $25 billion in U.S. dollar liquidity inside Chinese financial institutions. The intervention succeeded in breaking a massive 14-day appreciation streak, pushing the onshore yuan down 307 pips to close at 6.6765 per dollar.
- Australian Dollar (AUD/USD): The Aussie dollar finished flat at $0.6967. The currency absorbed a mixed backdrop where a hawkish interest rate hike by the Reserve Bank of Australia (RBA) was offset by generic global tech supply chain concerns.
Latin America
- Defensive Stance: Major regional commodity blocks like the Brazilian Real (holding near 5.49 per USD) and the Mexican Peso traded defensively. While the falling dollar generally supports emerging markets, collapsing raw export prices coupled with extreme political uncertainty surrounding the final composition of the U.S. Congress limited regional currency upside.
Kenya snapshot
- USD / KES: 129.61, as supplied in the 4 November artwork.
Global Commodities
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
| Commodity | Contract | Close | Daily performance | Market driver |
|---|---|---|---|---|
| Brent crude | Spot / futures | US$104.77/bbl | −7.64% | Qatar-mediated draft memorandum signals potential US–Iran de-escalation. |
| WTI crude | NYMEX December | US$96.09/bbl | −7.40% | Lower structural energy war premiums. |
| Gold | COMEX December | US$3,931.40/oz | +1.84% | Lower Treasury yields and short-covering support a bargain rebound. |
| Silver | Spot | US$49.67/oz | −0.20% | Modest tactical drag against gold’s defensive bid. |
| Corn | CBOT December | US$4.425/bushel | −5.75 cents | US harvest completion reaches 74%. |
| Soybeans | CBOT January | US$12.14/bushel | −2.75 cents | US harvest completion reaches 88%. |
Africa Markets
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
JSE closing level was not supplied.
| Market | Benchmark | Close | Daily change |
|---|---|---|---|
| South Africa | JSE Top 40 | — | −0.70% |
| Nigeria | NGX All-Share | 254,289.35 | +0.02% |
| Egypt | EGX 30 | 49,255.66 | +1.76% |
| West Africa | BRVM Composite | 529.41 | +0.78% |
| West Africa | BRVM 30 | 256.50 | +0.90% |
| Ghana | GSE Composite | 14,155.02 | −0.94% |
Africa-Wide & Energy Financing
- Africa Energy Bank (AEB) Formally Established: The African Export-Import Bank (Afreximbank) and the African Petroleum Producers’ Organisation formally set up the $5 billion Africa Energy Bank at its inaugural general meeting in Abuja, Nigeria. Egyptian banker Helmy Ghazi was named inaugural president to finance projects across the oil, gas, and energy value chains.
- World Bank Private Capital Surge: Private capital mobilized by the World Bank Group for Africa surged nearly 150% to $22 billion in fiscal year 2026, driven by increased guarantees to close the continent's infrastructure and development funding gaps.
South Africa
- AGOA Trade Risk: U.S. President Donald Trump notified Congress of plans to remove South Africa (along with Rwanda) from the African Growth and Opportunity Act (AGOA) trade deal effective January 1, 2027, citing trade/investment barriers and governance concerns. South African Trade Minister Parks Tau described the move as unfortunate and noted plans to diversify export markets.
- Billionaires & Market Ranking: South Africa's Johann Rupert & family ($16.1B), Nicky Oppenheimer & family ($10.6B), and Patrice Motsepe ($4.3B) remain top-ranked continental wealth holders as South Africa sees a quarterly rebound in foreign direct investment (FDI).
Nigeria
- Dangote Refinery IPO & Veenocks Expansion: Nigeria's industrial sector saw major movement as the Dangote Refinery IPO process progressed with regional investor interest (including Rwanda), while Afreximbank backed Veenocks Limited’s $145 million porcelain tile manufacturing expansion in Sagamu, Ogun State.
- Foreign Currency & Wealth: Foreign currency inflows into Nigeria reached $5.15 billion in October. Aliko Dangote remains Africa's richest individual with a net worth of $28.5 billion, followed by Abdulsamad Rabiu ($11.2B) and Mike Adenuga ($6.5B).
Egypt
- Leadership in Pan-African Institutions: Egyptian banker Helmy Ghazi took the helm as inaugural president of the newly launched $5 billion Africa Energy Bank.
- Billionaire Standings: Egyptian business leaders Nassef Sawiris ($9.6B), Naguib Sawiris ($5.6B), and Mohamed Mansour ($4.0B) continue to anchor Egypt's high-net-worth standing on the continent.
West Africa & Central Africa
- Africa Financial Summit (AFIS) in Angola: The Africa Financial Summit opened in Luanda, Angola, co-hosted by the African Development Bank, the Government of Angola, and the International Finance Corporation, focusing heavily on domestic capital mobilization.
- Côte d’Ivoire Growth Spotlight: Afreximbank released a country brief highlighting Côte d’Ivoire as one of West Africa's fastest-growing economies, supported by strong macroeconomic performance and regional trade integration.
South Africa — financial markets
- Rand Softens Amid AGOA Shock and Local Polls: The South African rand softened by 0.3% to trade at 16.64 against the US dollar. The currency faced pressure as investors assessed the Trump administration's decision to suspend South Africa from the African Growth and Opportunity Act (AGOA) effective January 1, 2027, alongside a wait-and-see approach ahead of municipal elections.
- Equities and Bonds: On the Johannesburg Stock Exchange, the Top-40 index fell 0.7%. However, fixed-income markets held resilient, with benchmark 2035 government bond yields easing down by 1.5 basis points to 8.52%. Market analysts noted the broader economic hit from the AGOA revocation was largely priced in.
Nigeria — financial markets
- Equities Push Sluggish Recovery: The Nigerian Exchange Group (NGX) All-Share Index achieved a modest 0.02% recovery to close at 254,289.35 points, reversing a major chunk of the prior session's loss. Market gains leaned heavily on selected large-caps, particularly Transcorp Power (+3.71%) and tier-1 banking institutions.
- Forex Spread Widens: In foreign exchange corridors, the Naira appreciated marginally by 0.07% to ₦1,346.93/USD at the official window. Conversely, the parallel Bureau De Change (BDC) average rate depreciated to ₦1,395/USD, widening the market spread to 3.57%.
- Financial System Liquidity Surge: Financial sector data projected a massive ₦13.79 trillion liquidity inflow for November 2026, fueled by Open Market Operations (OMO) maturities and slowed central bank mop-up operations.
Egypt — financial markets
- Bullish Run and Capital Inflows: The Egyptian Exchange (EGX) witnessed a significant rally, with the benchmark EGX30 index climbing 1.76% to finish at 49,255.66 points. Total stock trading turnover hit EGP 7.53 billion, with international institutional accounts acting as the sole net buyers for the session.
- Top Corporate Gainers: Real estate and consumer cyclicals powered the index upward, led by Orascom Development (+6.8%), Palm Hills Developments (+6.8%), and Eastern Company (+6.1%).
- Regulatory Focus: The Financial Regulatory Authority (FRA) met with an Omani delegation to discuss regulatory expansion, highlighting ongoing framework adjustments for futures, short selling, and derivatives trading.
Central & West Africa — financial markets
- AFIS 2026 Mobilizes Luanda: At the Africa Financial Summit (AFIS 2026) opening in Luanda, Angola, top policymakers and financiers discussed a glaring paradox: while continental banks remain highly profitable, credit to the private sector remains heavily restricted. Deliberations focused on mobilizing a portion of Africa's estimated $4 trillion in domestic savings to fund regional commerce and local currency trade instruments.
- Central Bank Activity: Institutional focus turned toward expanding the adoption of the Pan-African Payment and Settlement System (PAPSS) to accelerate payment integration across regional borders.
- BRVM (West African Regional Exchange): The BRVM Composite Index climbed 0.78% to close at 529.41 points. The blue-chip BRVM 30 added 0.90% to finish at 256.50 points, while total market capitalization reached FCFA 20,761 billion across the regional trading bloc.
- Ghana Stock Exchange (GSE): The GSE Composite Index slid 0.94% to end at 14,155.02 points. Total market capitalization recorded a minor contraction to GH¢ 266,177.32 million.
- BVMAC (Central African Regional Exchange): The index remained stable with daily operations focusing heavily on fixed-income subscriptions. Corporate equity activities were anchored by standard valuations for regional pillars like BGFI Holding Corporation.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
The All-Share slipped while the NSE 20, NSE 25 and sector benchmarks rose; aggregate equity turnover surged alongside Nedbank’s NCBA acquisition.
- Market capitalisation: KSh 3,974.86 billion, down KSh 9.95 billion.
- Equity trading: Aggregate turnover of KSh 107,748,901,074.57 across 1,101,689,156 shares, compared with KSh 420.4 million turnover in the previous session.
- Derivatives: KSh 2,603,987.00 turnover across 3,084 contracts.
| Index | Close | Change (points) | Daily change |
|---|---|---|---|
| NSE All-Share (NASI) | 236.85 | −0.59 | −0.24% |
| NSE 20 | 4,131.22 | +15.38 | +0.37% |
| NSE 25 | 6,624.98 | +42.11 | +0.64% |
| NSE 10 | 2,577.46 | +15.16 | +0.59% |
| NSE Banking Sector Index | 274.92 | +2.17 | +0.79% |
Kenya Corporate News
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
South Africa’s Nedbank Finalizes Takeover of NCBA Group
- Nedbank completed the acquisition of a 66% controlling stake in NCBA Group Plc.
- Transaction: The acquisition was executed through the NSE Block Trade Board, contributing to the exceptional aggregate market turnover.
- Payout and structure: Accepting shareholders received KSh 23.23 billion in cash and 43.63 million new Nedbank shares. NCBA retains its NSE listing, 34% public float, branding, management and board structure; Nedbank will nominate two directors.
Kenya Pipeline Company (KPC) Foils Mombasa Pipeline Siphoning Attempt
- Kenya Pipeline Company security teams detected and neutralized a criminal illegal connection on its pipeline between Pumping Station 14 and 15 in Mombasa. The company confirmed that no petroleum products were lost due to immediate detection by their automated and physical real-time monitoring infrastructure.
KenGen Appoints Former Infrastructure PS John Mosonik as Chairman
- The Kenya Electricity Generating Company (KenGen) formally announced the appointment of former Principal Secretary for Infrastructure, John Kipngetich Mosonik, as the new Chairman of its Board of Directors. Mosonik's corporate leadership is expected to spearhead KenGen's aggressive G2G 2034 green energy expansion strategy.
Kenya Revives Turkana-to-Lamu Pipeline for Dangote Refinery
- The Government of Kenya announced plans to revive the construction of the Turkana oil pipeline connecting inland oilfields to the Port of Lamu. The light sweet crude will serve as crucial feedstock for the Aliko Dangote-backed regional refinery project, where Dangote has already acquired a 24.99% stake in KPC and committed KES 195 million to advance pipeline network connectivity.
Spectrum Payment Model Proposes Upfront Multi-Billion Bill for Telcos
- A regulatory shake-up looms for the telecommunications sector. Under a new proposal, major telcos—including Safaricom, Airtel, and Telkom Kenya could be required to pay billions of shillings upfront for their spectrum rights, eliminating the long-standing installment payment plan model.
Kenya Real Estate
Figures as at · Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
Knight Frank 2026 Report: Wealthy Kenyans Shift Offshore Focus to South Africa
- The newly released Knight Frank Wealth & Investment Trends 2026 report reveals a notable shift in where high-net-worth individuals (HNWIs) in Kenya are placing their offshore property cash.
- While domestic real estate remains the primary choice for 60% of wealthy Kenyans, offshore preferences are pivoting.
- South Africa has risen sharply, now capturing 15% of local managers' offshore property preferences, while the United States has faded in prominence. The United Kingdom retains the leading international spot at 25% due to historical ties and market maturity.
- Wealthy domestic investors are also gradually reallocating money away from traditional primary/secondary homes into instruments like REITs, private data centers, and agricultural land/carbon credits.
REIT reform proposals
- The Capital Markets Authority (CMA) also proposed cutting D-to-I REIT conversion fees from up to KSh 7.5 million down to a standardized KSh 150,000, while lowering public ownership requirements from 25% to 15%.
Affordable housing & satellite towns
- The government's Affordable Housing Programme continues to scale—including handovers at the Pioneer Estate in Eldoret—amid discussions over rising unit prices and active development in Nairobi's satellite towns.
Top Property Awards 2026
- Nominations are open through November 10, 2026, for the industry gala scheduled for November 19, 2026, at the Safari Park Hotel in Nairobi.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.61
Rate supplied in the 4 November artwork.
As at
Serrari Group supplied artwork, 4 November 2026; market snapshot as at 3 November 2026
Equities
NSE All-Share
236.85
−0.59 points, −0.24%.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026NSE 20-Share
4,131.22
+15.38 points, +0.37%.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026NSE 25-Share
6,624.98
+42.11 points, +0.64%.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026Equity turnover
KSh 107.75 billion
Aggregate market turnover; exceptional acquisition activity.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026Market capitalisation
KSh 3,974.86 billion
Down KSh 9.95 billion.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
Rates
Central Bank Rate
8.75%
Prevailing policy rate.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026Kenya 10-year bond
12.530%
Benchmark government bond yield.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 202691-day Treasury bill
8.7498%
Latest auction average.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026182-day Treasury bill
8.8508%
Latest auction average.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026364-day Treasury bill
9.0288%
Latest auction average.
As at
Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
At a glance
- 1Brent falls 7.64% to US$104.77 a barrel, while the Nasdaq gains 0.83% and the US 10-year Treasury yield eases to 4.902%.
- 2NSE turnover reaches KSh 107.75 billion alongside Nedbank’s 66% NCBA acquisition; NASI slips to 236.85 while the NSE 20 and NSE 25 gain.
- 3The CMA proposes a KSh 150,000 D-to-I REIT conversion fee and a lower public ownership threshold; the UK and South Africa lead offshore property preferences.
Sources
- Serrari Group desk compilation, 4 November 2026; Markets Snapshot – 3 November 2026
- Serrari Group supplied artwork, 4 November 2026
- Nairobi Securities Exchange — market statistics
- Serrari published Africa macro data