
5 November 2026
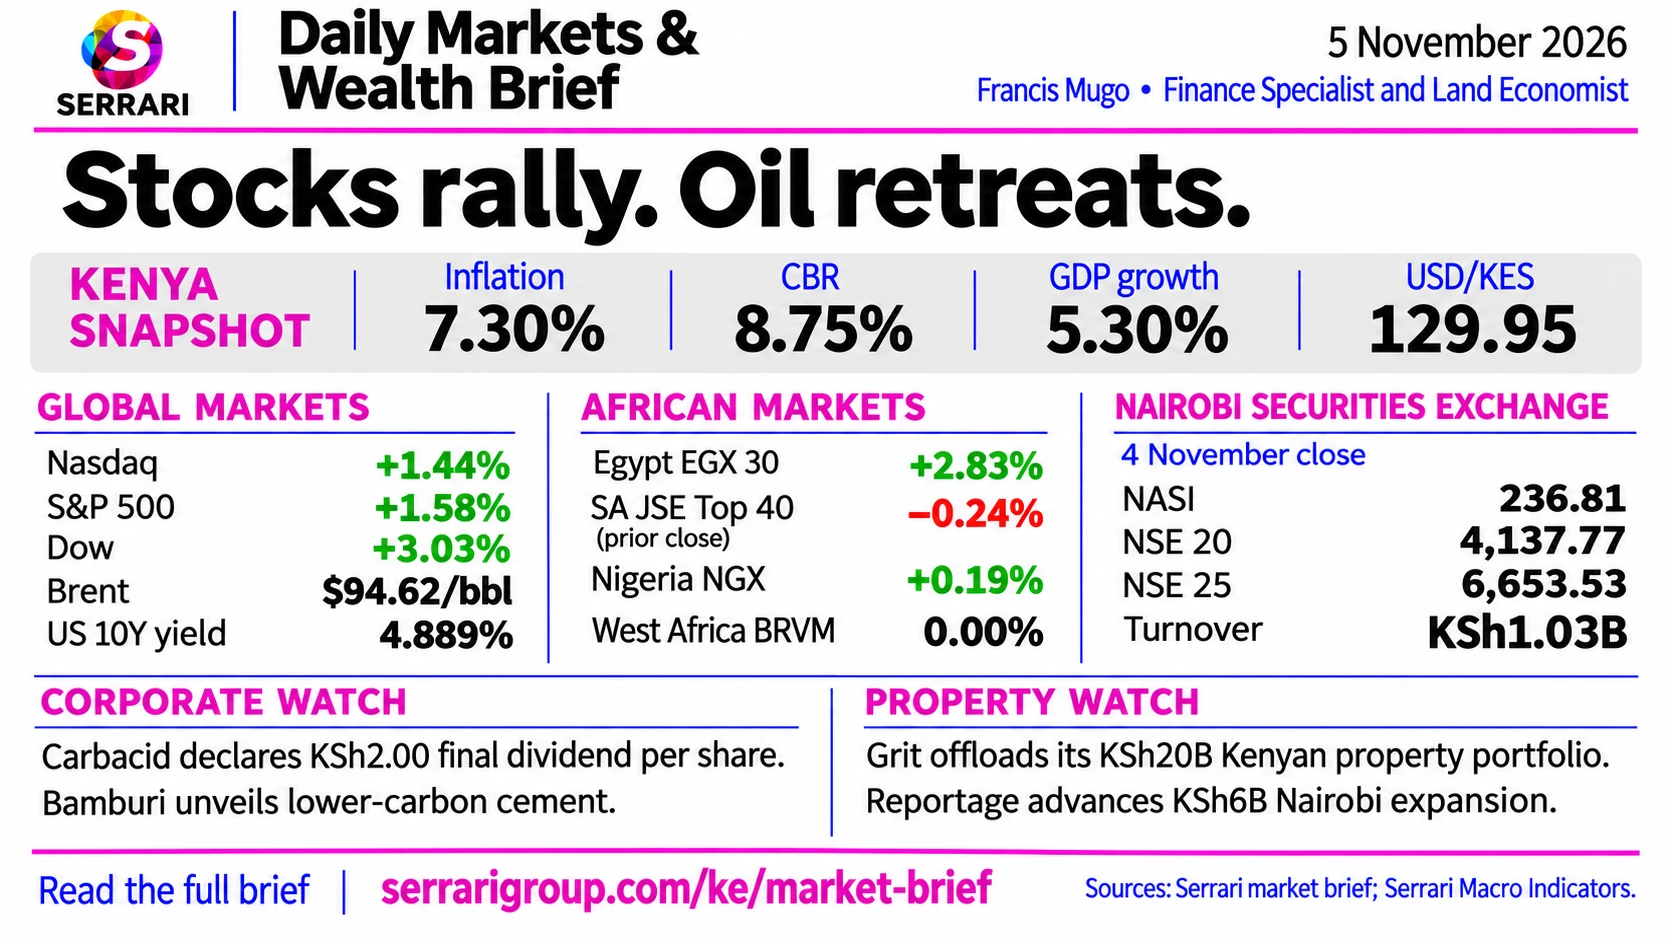
Wall Street rallied after the US midterms, with the Dow up 1,569 points (3.03%) for its best day in 18 months, as Brent crashed 8.7% to $94.62 on hopes of a US–Iran peace deal. In Nairobi, the NSE 10 rose 0.79% and equity turnover reached KSh 1.03 billion.

Global Markets
Figures as at · Closing levels for Wednesday 4 November 2026, as reported in this brief
A Democratic “blue wave” that gave the party control of both chambers of Congress first triggered a volatile risk-off night. Equities then surged after President Donald Trump accepted the results and offered to work with the new Congress, and energy markets collapsed after Vice President JD Vance blamed the losses on the US–Iran conflict, raising hopes of a peace deal.
Major indices
| Index | Close | Change |
|---|---|---|
| Dow Jones Industrial Average | 53,356.12 | +1,569.40 (+3.03%) |
| S&P 500 | 7,688.62 | +119.70 (+1.58%) |
| Nasdaq Composite | 25,736.51 | +364.50 (+1.44%) |
| Russell 2000 | 2,856.95 | +44.50 (+1.56%) |
| Canada — S&P/TSX Composite | 36,341.40 | +809.12 (+2.28%) |
| Brazil — Ibovespa | 167,563.47 | +2,015.59 (+1.22%) |
| Germany — DAX | 26,437.67 | +573.05 (+2.22%) |
| Spain — IBEX 35 | 19,370.90 | +563.70 (+3.00%) |
| France — CAC 40 | 8,177.89 | +157.58 (+1.96%) |
| UK — FTSE 100 | 10,829.21 | +190.78 (+1.79%) |
| Switzerland — SMI | 15,022.85 | +279.76 (+1.90%) |
| Japan — Nikkei 225 | 62,188.63 | −784.53 (−1.25%) |
| Hong Kong — Hang Seng | 23,919.50 | +590.15 (+2.53%) |
| Australia — ASX 200 | 9,006.90 | +172.37 (+1.95%) |
United States and Canada
- Wall Street: The Dow jumped 1,569 points (3%), its best day in 18 months and its fifth-largest one-day point gain in history. The S&P 500 rose 1.5% and the Nasdaq 1.4%, recovering steep overnight futures losses.
- Energy and defence: Front-month Brent crashed 8.7% to $94.62 a barrel on ceasefire hopes. RTX, General Dynamics, Lockheed Martin and Northrop Grumman each fell more than 2% on expectations of tighter defence spending.
- Politically linked stocks: Trump Media & Technology Group plunged 25%, and other MAGA-linked tech and marketplace companies sold off heavily.
- Canada: The S&P/TSX rose 2.28% with Wall Street. Prime Minister Carney announced trips to Europe and Asia to diversify trade and draw foreign investment.
Latin America
- Markets: Brazil’s Bovespa gained 1.23% and Mexico’s S&P/BMV IPC 0.91%.
- Carbon credits: Latin American nature-based solution credits still dominate global volume but could not break the $16 resistance level.
- Local debt: BlackRock and other institutions kept a strong preference for Latin American local-currency debt, citing yields that reward the risk.
Europe
- Rebound: European indices closed sharply higher, with the FTSE 100 rebounding on the US election relief and cheaper oil, and bourses welcomed the prospect of tariff relief under a split Washington.
- Defence: BAE Systems and Thales came under pressure, mirroring US defence stocks.
- Headwinds: Trading was cautious earlier in the day after a third-quarter GDP contraction in France and ECB warnings that its rate-hiking cycle may not be over.
Asia-Pacific
- Volatile sessions: Asian markets opened with heavy tech selling before recovering as US Treasury yields eased.
- Japan: The Nikkei 225 fell 1.4%. SoftBank Group slumped as much as 8% before closing 3.2% lower on fears that a Democrat-led Congress will tighten scrutiny of AI data centres, and Kioxia Holdings plunged 10.8% on weak guidance.
- China and Australia: The Shanghai Composite rallied 2.2% as investors repositioned around the new US political landscape. The ASX 200 fell 0.6% after the Reserve Bank of Australia raised its cash rate to 4.85% to fight sticky inflation.
Forex
- US dollar: A sharp slide in Treasury yields pushed the dollar index lower across the board.
- USD/CAD: Slid 0.3% to near 1.3965 after a seven-week low of 1.3930, helped by a wider Canadian trade surplus of C$5.35 billion.
- EUR/USD: Rose past 1.1250 to a three-week high, supported by flash data showing euro zone inflation at a three-year high of 4% in October.
- GBP/USD: Strengthened past 1.3500.
- USD/JPY: Eased towards 157.90–158.00 as lower US yields narrowed the rate gap.
- AUD/USD: Edged up to near 0.6220 after the Reserve Bank of Australia’s rise to 4.85%.
- USD/MXN and USD/BRL: The peso strengthened, pushing USD/MXN to 18.55–18.60, and the real steadied around 5.46 per dollar after a multi-month peak of 5.49 earlier in the week.
Global Yields
Figures as at · Yields for 4 November 2026, as reported in this brief
Strong inflows pushed US yields to near two-month lows. In Europe, cheaper crude eased inflation fears, but faster-than-expected euro zone flash inflation kept a floor under yields. Latin American local debt kept its appeal for carry.
Government bond yields
| Bond | Yield | Context |
|---|---|---|
| US 2-year Treasury | 4.546% | Down 6.6 bps to a two-month low |
| US 10-year Treasury | 4.889% | Down from 4.951% the previous session |
| US 30-year bond | 5.282% | Down from 5.323% |
| Canada 10-year | 3.712% | Down 7 bps with US yields and the dollar |
| UK 10-year Gilt | 5.135% | Near late-1990s levels on heavy issuance and BoE expectations |
| Spain 10-year | 3.862% | — |
| Sweden 10-year | 3.071% | — |
| Germany 10-year Bund | ~2.75%–2.80% | Steady buffer as the ECB signals caution over its hiking pause |
| Japan 10-year JGB | ~0.95%–1.05% | Exceptionally steep curve as investors watch domestic normalisation |
| Australia 10-year | ~4.40%–4.50% | After the Reserve Bank of Australia’s rise to 4.85% |
| Thailand 91-day | 0.813% | Central bank bond auction average |
| Brazil 10-year | ~12.20%–12.50% | Compressing after the Selic was cut to 13.75% |
| Mexico 10-year | ~9.80%–10.10% | Mild upward pressure from fiscal expansion |
Commodities
Figures as at · Closing prices for 4 November 2026, as reported in this brief
Crude had one of its worst days of the year on expectations that the Strait of Hormuz could soon fully reopen, while gold passed $4,000 as money left a weaker dollar and falling Treasury yields.
Closing prices
| Commodity | Price | Change | Driver |
|---|---|---|---|
| Brent crude | $94.62 / bbl | −$9.02 (−8.7%) | Hopes the Strait of Hormuz will fully reopen |
| WTI crude | $90.15 / bbl | −$8.25 (−8.4%) | Followed Brent lower |
| Natural gas (Henry Hub) | $3.12 / MMBtu | +1.8% | Early winter heating demand forecasts |
| Spot gold | $4,012.50 / oz | +$94.10 (+2.4%) | Past $4,000 on a weaker dollar and lower yields |
| Spot silver | $38.15 / oz | +3.1% | Followed gold |
| LME copper | $9,420 / t | +1.9% | Fears of broad US tariffs softened |
| Chicago wheat | $6.42 / bu | +1.6% | Weaker dollar helped US exports |
| Chicago corn | $4.85 / bu | +1.1% | Weaker dollar helped US exports |
| Soybeans | $12.18 / bu | −0.4% | Higher South American production forecasts |
| Rice (Asia benchmark) | $615 / t | Steady | Strong regional import volumes |
| Iron ore (Brazil to China) | $104.50 / dmt | +1.2% | Firmer industrial metals sentiment |
| Arabica coffee | $2.48 / lb | −0.8% | Better weather in Minas Gerais, Brazil |
| Nature-based carbon credits | $16.00 / t | Flat | Latin American volume, but a hard price ceiling |
Africa
Figures as at · Closing levels for 4 November 2026, as reported in this brief
Major African indices
| Index | Close | Change | Highlights |
|---|---|---|---|
| South Africa — FTSE/JSE Top 40 | 101,192.33 | −0.24% (prior close) | Slightly below recent peaks; industrial and tech giants weighed |
| Nigeria — NGX All-Share | 254,762.81 | +0.19% | Up 473 points on banks and energy stocks such as Transcorp Power |
| Egypt — EGX 30 | 50,650.18 | +2.83% | A major rebound after weeks of correction; 84% of components rose |
| West Africa — BRVM Composite | 525.30 | 0.00% | Steady midweek; up more than 50% this year |
| Central Africa — BVMAC | N/A | Flat / illiquid | Minimal daily activity |
Southern Africa
- AGOA: President Trump issued a 60-day notice ending South Africa’s duty-free status under AGOA from 1 January 2027. President Cyril Ramaphosa called it a negative development and said Pretoria will push for a bilateral trade agreement and more diverse export markets.
- Youth unemployment: Statistics South Africa reported youth unemployment (ages 15 to 34) of 47.4% in the second quarter of 2026, keeping pressure on the Government of National Unity.
- WeBuyCars: The JSE-listed car retailer has shed more than R8 billion in value, with its shares down 42.79% this year.
West and Central Africa
- Africa Energy Bank: Afreximbank and the African Petroleum Producers’ Organization formally launched the Africa Energy Bank in Abuja with $5 billion of authorised capital for oil and power projects, as traditional lenders scale back fossil fuel finance.
- Crude: West African crude trade was subdued after the US midterms, with no deals in the Platts window and weaker physical differentials. Qua Iboe was valued at dated Brent plus $1.35 a barrel.
- Dangote: After its N6.4 trillion ($4.77 billion) Nigerian public offer closed on 28 October, Dangote is in talks with other African bourses to widen access through global depositary receipts, and regulators at the Luanda summit were urged to adopt mutual recognition rules.
- BRVM: Chief executive Edoh Kossi Amenounve said the region’s first derivatives market has been pushed back to 2027 to complete regulatory and technology work.
East and North Africa
- Tanzania SGR: The African Development Bank finalised a $1.2 billion commercial financing package for Tanzania’s Standard Gauge Railway, syndicated with lenders including Deutsche Bank, Société Générale and HSBC.
- Rwanda and AGOA: Rwanda also faces suspension from AGOA preferences from January 2027, but analysts expect little disruption given its diversified mineral and coffee exports.
- Arusha Airport: Moved to 24-hour operations after a $4 million upgrade.
- Fuel costs: Tanzania’s fuel prices rose after months of Brent averaging $124–$125 a barrel in October, lifting transport and operating costs across East Africa.
- Egypt: The IMF forecasts 4.7% growth, supported by renewable energy investment. Fintech OPay, a large payments operator in Egypt and Nigeria, pulled its US IPO because of a regulatory inquiry. Analysts say a Democratic Congress could shift oversight of trade and foreign policy with partners such as Egypt.
Pan-African finance
- AFIS 2026: On the second day of the Africa Financial Summit in Luanda, policymakers debated how to unlock an estimated $4 trillion of institutional savings for private-sector credit.
- PAPSS: The Pan-African Payment and Settlement System links more than 200 banks in 30 countries, but the sixth Deloitte-AFIS barometer found only 11% of surveyed institutions actively connected, citing slow AfCFTA implementation.
Nairobi Securities Exchange and Bonds
Figures as at · Nairobi Securities Exchange session data for Wednesday 4 November 2026, as reported in this brief
Kenyan market figures are the 4 November close. The session was mixed: the NSE 10 rose 0.79% and the NSE 20 0.16%, while the NASI slipped 0.02%.
NSE indices
| Index | Close | Change |
|---|---|---|
| NSE All-Share (NASI) | 236.81 | −0.04 |
| NSE 20-Share | 4,137.77 | +6.55 |
| NSE 25-Share | 6,653.53 | +28.55 |
| NSE 10-Share | 2,597.79 | +20.33 |
| Banking Sector Index | 276.11 | +1.19 |
Market activity
- Market capitalisation: KSh 3,974.22 billion, down KSh 0.64 billion.
- Equity turnover: KSh 1,031,054,571.63 on 26,546,126 shares across 11,987 deals.
- Bond turnover: Secondary bond turnover surged 347.85% to KSh 23.96 billion.
Notable movers
- Gainers: Led by heavyweights including the Nairobi Securities Exchange, Equity Group, Diamond Trust Bank, Carbacid Investments and KCB Group.
- Decliners: Kenya Pipeline, NCBA Group, Eveready East Africa, Home Afrika and Uchumi Supermarket came under pressure.
Government securities
- Treasury bills: The 91-day bill averaged 8.75% heading into November’s auctions, the 182-day 8.85%, in line with the CBR, and the 364-day 9.03%.
- Bonds: The 2-year yielded 9.11% in the secondary market and the 10-year benchmark 12.52%, down 0.01% on the session.
- Reopened bonds: FXD3/2019/015 (15-year, 7.8 years to maturity) was awarded at 12.74%, and FXD1/2026/030 (30-year, 29.5 years to maturity) at 14.13%, heavily oversubscribed.
Kenya Forex
Figures as at · Central Bank of Kenya official rates, 4 November 2026, as reported in this brief
- Reserves: Foreign exchange reserves reached about US$15.3 billion, roughly 6.5 months of import cover.
- Shilling: Held tightly around KSh 129.95 to the dollar, supported by export earnings up 12% year on year and tourism receipts.
CBK official rates
| Currency | Rate (KES) |
|---|---|
| US dollar | 129.95 |
| Sterling pound | 174.39 |
| Euro | 145.40 |
Kenya Corporate News
Figures as at · As reported in this brief
Corporate actions
- Nedbank and NCBA: Nedbank completed its partial offer for a 66% controlling stake in NCBA Group through an on-market block trade of 1.087 billion shares on the NSE.
- Carbacid: Declared a final dividend of KSh 2.00 a share, with books closing on 27 November 2026 and payment on 17 December 2026.
- Bamburi Cement: Unveiled a low-carbon cement that cuts emissions by 64%.
Banking and digital
- Sustainable finance roadmap: The Kenya Bankers Association and commercial banks launched a 10-year roadmap with the IFC and WWF-Kenya that makes environmental, social and governance criteria mandatory in lending, alongside green lending and nature-risk work.
- Crypto: Crypto transaction value in Kenya rose 38% to a record KSh 740 billion in the year to June, from KSh 505 billion in 2025, driven by cross-border trade and importers seeking liquidity.
- Spectrum: Safaricom, Airtel and Telkom Kenya face multi-billion-shilling upfront costs under a proposed Treasury rule ending instalment payments for spectrum.
Kenya Economy and Investment
Figures as at · As reported in this brief
Industry and investment
- Industrialisation Summit: President William Ruto opened the summit at KICC and challenged manufacturers to triple paid internships to 150,000. KAM called for relief from high electricity costs and more predictable regulation.
- US investment: AmCham Kenya urged the state to fix unstable tax policy and VAT refund delays, against a $600 million pipeline of US commitments including Coca-Cola ($175 million), Mars Wrigley ($103 million), Digital Realty ($80 million) and Oracle’s planned public cloud region.
- Lokichar–Lamu pipeline: Plans are in motion to revive the crude pipeline so that Kenyan crude can feed Nigeria’s Dangote refinery.
Macroeconomy
- World Bank: The World Bank’s latest Economic Update raised Kenya’s 2026 growth forecast to 4.6% from 4.3% on a strong first half, but warned that corruption imposes a “governance premium” costing about 2% of GDP a year in higher borrowing costs.
- e-procurement: Treasury CS John Mbadi said the e-GP system has automated 4,470 contracts worth KSh 18.3 billion since launch.
Real Estate
Figures as at · As reported in this brief
Grit’s Kenyan assets
| Asset | Location and details | Financial context |
|---|---|---|
| Rosslyn Grove Estate | Gated community housing US Embassy staff | Financed by a $35 million Absa Kenya loan |
| Buffalo Mall | Commercial mall in Naivasha | Part of a wider KSh 20.5 billion portfolio |
| Eneo Tatu City | Office and BPO hub | Creditors providing tight working capital |
Grit sells up
- Grit Real Estate: The debt-distressed Mauritian developer is offloading its entire Kenyan portfolio, worth about KSh 20 billion, as high global interest rates and financing costs force it to unwind assets.
Foreign expansion
- Reportage Group: The UAE developer confirmed a KSh 6 billion expansion across Nairobi and is assessing new plots beyond its active projects: DG JKIA (over 90% sold), DG West and Enzo Residence.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro dataForeign exchange reserves
US$15.3bn
~6.5 months of import cover
As at
As reported in this brief
Foreign exchange
USD / KES
129.95
As at
Central Bank of Kenya official rate, as reported in this briefGBP / KES
174.39
As at
Central Bank of Kenya official rate, as reported in this briefEUR / KES
145.40
As at
Central Bank of Kenya official rate, as reported in this brief
Equities
NSE All-Share
236.81
−0.04
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,137.77
+6.55
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,653.53
+28.55
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 1.03 billion
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KSh 3,974.22 billion
−KSh 0.64 billion
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee decision of 7 October 202691-day T-bill
8.75%
As at
Latest average yield, as reported in this brief182-day T-bill
8.85%
As at
Latest average yield, as reported in this brief364-day T-bill
9.03%
As at
Latest average yield, as reported in this briefKenya 2-year bond
9.11%
As at
Secondary market yield, as reported in this briefKenya 10-year bond
12.52%
As at
Benchmark bond yield, as reported in this brief
At a glance
- 1A Democratic “blue wave” in the US midterms first rattled futures, then President Trump’s conciliatory response sparked a relief rally: the Dow jumped 1,569 points (3.03%), its best day in 18 months, and Brent crashed 8.7% to $94.62 on hopes of a US–Iran peace deal.
- 2On the NSE, the NSE 10 rose 0.79% and the NSE 20 0.16% while the NASI slipped 0.04 to 236.81. Equity turnover reached KSh 1.03 billion, and secondary bond turnover surged 347.85% to KSh 23.96 billion.
- 3Grit Real Estate is selling its entire Kenyan portfolio, about KSh 20 billion including Rosslyn Grove, Buffalo Mall and Eneo Tatu City, while Carbacid declared a KSh 2.00 final dividend and the World Bank raised Kenya’s 2026 growth forecast to 4.6%.
Sources
- Serrari Group desk compilation, 5 November 2026; Markets Snapshot – 4 November 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data