
9 November 2026
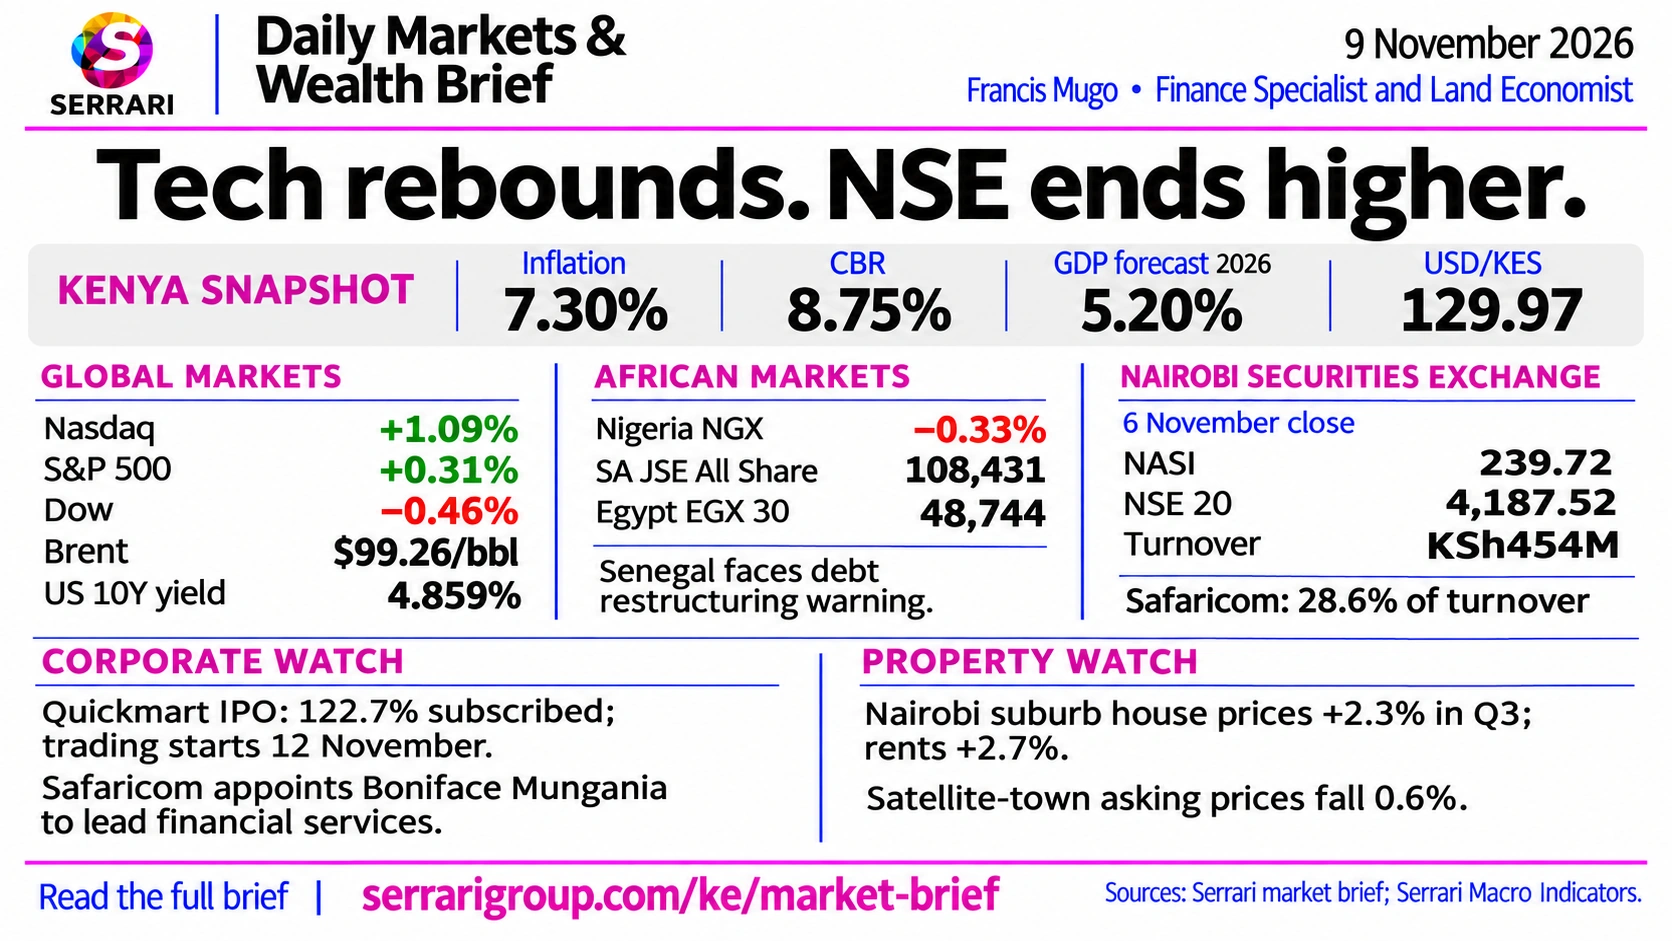
Technology stocks rebound as the Nasdaq gains 1.09%, while the NSE ends the week higher with NASI at 239.72 and Friday turnover of KSh 454 million. Quickmart’s IPO reaches 122.7% subscription, and Nairobi suburban house prices and rents rise in Q3.

Global Markets
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
US technology stocks rebound after a difficult week, while strong payrolls support the dollar and Treasury yields; Asian semiconductor markets remain under pressure.
US market highlights
- AI and Chip Stock Rebound: Following a brutal Thursday where the Nasdaq 100 plunged 6.3% over data center regulation anxieties, buyers stepped back in. Advanced Micro Devices (AMD) surged over 11%, and Nvidia (NVDA) added 2.78%, helping the Nasdaq claw back some weekly losses.
- Strong Nonfarm Payrolls: The October jobs report substantially beat expectations, adding 165,000 jobs against forecasts of 65,000. The unemployment rate dropped to 4.1%.
- Yields and Fed Bets Shift: The robust jobs data sent the 10-year U.S. Treasury yield up to 4.859%. Traders increased the probability of a December Federal Reserve rate hike to roughly 78%.
Canada market highlights
- Softening Labor Market: Unlike the U.S., Canada's economy lost momentum as the unemployment rate ticked up to 6.7% in October. Total employment dropped by 4,700 positions, marking the third consecutive month of employment contraction.
- BOC Rate Relief Expectations: Due to persistent weakness in private-sector jobs, traders trimmed expectations for near-term interest rate hikes, pricing in just 33% odds for a December move by the Bank of Canada.
- Federal Budget Aftermath: Markets digested the newly tabled 2026 Canadian Federal Budget, which focused on massive productivity tax deductions alongside consumer support, pushing the projected deficit over $62 billion.
Europe: Midday Sell-off Followed by a Partial Recovery
- European equity markets opened heavily in the red following the overnight Asian panic but recovered off their session lows by the closing bell.
- Market Indices: London’s FTSE 100 index plunged 2.35% during morning trading but clawed back to close down 1%. Germany's DAX recovered from a midday 2.36% slide to finish flat, while France’s CAC 40 managed a 2.13% weekly gain.
- Monetary Policy: The Bank of England’s decision to hike interest rates to 4.0% continued to reverberate through the FTSE, while ECB President Christine Lagarde confirmed a December rate hike remains the baseline.
- Data Centers Under Fire: Beyond stocks, more than 100 civil rights groups across 15 European nations launched synchronized protests demanding an immediate moratorium on new megadata center construction, further spooking AI infrastructure investors.
Asia-Pacific: Circuit Breakers and Severe Tech Liquidation
- Asian markets bore the brunt of the global technology sell-off, heavily impacting semiconductor hubs, while South Asia decoupled entirely.
- Japan: The Nikkei 225 plummeted 5.96% (down 9.25% for the week) to close at 57,434.77, marking its worst single-day drop since April 2025. Major tech anchors like Advantest and SoftBank suffered steep declines.
- South Korea: The tech-heavy KOSPI plunged over 8% intraday, triggering automatic exchange circuit breakers to halt trading. Authorities stepped in to waive the 140% margin-loan collateral threshold for three months to prevent forced liquidations. The index closed the week down 11.71%.
- Taiwan: The benchmark index dropped 4.5%, shoving the semiconductor-dense market directly into an official bear market territory.
- India: Remained a complete global outlier, recording its strongest weekly stock market rally in six years, with the Nifty 50 gaining 8.58% to close at 25,030.35.
- Greater China: Maintained relative resilience, with Hong Kong's Hang Seng closing the week 5.10% higher.
Latin America: Macro Adjustments and Fintech Shock
- While less exposed to the immediate semiconductor supply chain panic, Latin American markets faced macro headwinds and unique regional tremors.
- Paraguay: A massive fintech platform failure sent shockwaves through regional financial sectors, triggering an immediate political earthquake and structural concerns over digital banking oversight.
- Macro Environment: The region continued navigating a slow-growth environment impacted by strict U.S. trade protectionism hitting Mexico’s industrial export pipeline, though long-term productivity remains supported by rapid mobile tech adoption.
Global Equity Indices
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
6 November closing levels; daily and weekly returns are shown separately.
| Benchmark | Close | Daily change | Weekly change |
|---|---|---|---|
| S&P 500 | 7,376.86 | +0.31% | −2.68% |
| Dow Jones Industrial Average | 51,285.73 | −0.46% | −0.94% |
| Nasdaq Composite | 24,579.42 | +1.09% | −3.37% |
| S&P/TSX Composite | 35,789.09 | +0.52% | −1.53% |
Global Commodities
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
Energy: Crude Recovers, But Suffers Sharp Weekly Loss
- While oil bounced slightly on Friday due to a re-emerging geopolitical risk premium and maritime tensions in the Middle East, it capped off a brutal weekly drop. The market unwound supply premiums following the U.S. midterm elections, which raised hopes of regional de-escalation.
- Brent Crude: Settled up roughly 1% on the day to $99.26 a barrel, though it fell more than 16% on a weekly basis.
- WTI Crude: Gained 0.53% to end at $91.00 a barrel.
- Natural Gas (Henry Hub): Finished slightly higher at $2.78/MMBtu. A lower-than-expected EIA storage build (+77 Bcf vs +81 Bcf) gave it a minor boost, though record warmth capped massive gains.
Precious Metals: Under Pressure from a Surging Dollar
- Precious metals suffered an intraday correction as the massive U.S. payroll beat fortified the U.S. dollar, driving yields higher and denting non-yielding asset appeal.
- Gold: Spot gold dropped nearly 1% to end around $4,076.10 per troy ounce, retreating from earlier weekly highs above $4,130.
- Silver: Eased slightly to end around $57.66 per ounce after a major mid-week short-squeeze that saw it previously reclaim the $50–$53 territory.
Industrial Metals: record Stocks Weigh on Copper
- Copper: Settled near $6.25 per lb ($13,660/tonne). Industrial metals fell to multi-month lows as a record surge in COMEX inventories (hitting 731,428 tonnes) outweighed tight supply indicators and record premiums out of Shanghai.
Agriculture & Livestock: Mixed Grains, Major Livestock Rout
- Grains managed a modest short-covering recovery ahead of the upcoming USDA reports, while livestock faced relentless bearish pressure.
- Corn & Soybeans: December corn closed up slightly at $4.41½ per bushel, while January soybeans rose to $11.93¾. Gains were supported by a flash sale of U.S. agricultural goods to China.
- Wheat: Chicago wheat dropped 8 cents to close at $5.91¼ per bushel, weighed down by heavy Russian export supplies and optimizing expectations for Black Sea grain movements amid pending peace talks.
- Livestock: Feeder cattle fell heavily to $318.37 per cwt, and live cattle dropped to $214.05 per cwt, recording some of their lowest levels since late 2025 due to a major programmatic sell-off throughout the week.
Africa Markets
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
South Africa faces election uncertainty and technology-sector pressure, Nigeria extends weekly losses, and Senegal faces debt sustainability warnings.
The submission uses different return periods for these markets; they are labelled explicitly.
| Market | Benchmark | Close | Reported period and move |
|---|---|---|---|
| South Africa | JSE All Share | 108,431 | Daily: down over 1% |
| Nigeria | NGX All-Share | 248,877.22 | Daily: −0.33% |
| Egypt | EGX 30 | 48,744 | Weekly: down nearly 2% |
South Africa: JSE Softens as Rand Weakens on Election Shifts
- Equities Downturn: The Johannesburg Stock Exchange fell back (All Share Index down over 1% to 108,431), tracking a global sell-off in US tech and AI sectors.
- Rand Slippage: The South African rand weakened to approximately R16.53 per US dollar.
- Election Cautiousness: Investors monitored ongoing municipal election results showing the ANC drop to 32% and the pro-business DA steady at 24%.
- Sovereign Bonds: The benchmark 2035 government bond yield climbed 4.5 basis points to 8.33%.
- Corporate Earnings: Paper manufacturer Sappi reported a steep full-year EBITDA drop to $294M due to Middle East logistics costs and a stronger rand.
- Retail Restructuring: The Foschini Group (TFG) confirmed closing 120 underperforming offshore stores.
Nigeria: Equity Losses Extend and Stablecoin Ban Enforced
- Market Drop: The Nigerian Exchange Group (NGX) All-Share Index dropped 0.33% to end Friday at 248,877.22, losing ₦540 billion in a single day.
- Weekly Summary: Total weekly equity losses reached 2.13% to close at ₦161.59 trillion.
- Naira Tracking: The Nigerian naira closed at ₦1,375 per US dollar on the official market.
- Liquidity Influx: Commercial banks' deposits at the Central Bank of Nigeria's (CBN) Standing Deposit Facility surged to ₦8.31 trillion.
- CBN Mop-Up: The apex bank counteracted by absorbing ₦724.32 billion via an Open Market Operations (OMO) auction.
- Crypto Regulation: The CBN enacted strict stablecoin licensing rules and placed an immediate ban on algorithmic stablecoins.
Egypt: Sovereign Gas Breakthrough and IPO Traction
- Stock Stagnation: The EGX30 index suffered institutional sell-offs, closing down nearly 2% for the week at 48,744 points.
- Treasury Competition: Equity demand was stifled by high-yielding government securities.
- Energy Boom: Egypt announced the "Nasim-1X" natural gas discovery in the Mediterranean Sea.
- Gas Output: The new exploratory reservoir is estimated to contain 200 billion cubic feet of gas.
- Capital Momentum: EFG Hermes celebrated the successful $658 million historic IPO completion of Banque du Caire.
West Africa: Senegal Debt Default Warning
- Credit Rating Alert: Moody's Ratings issued a stark warning that Senegal’s ongoing external debt restructuring will likely constitute a distressed exchange default.
- Yield Premium: Senegal remains the continent’s most distressed sovereign, with investor yield premiums sitting 1,469 basis points above US Treasuries.
- Fiscal Deficit Expansion: Senegal’s rejected revised 2026 budget projected a widened deficit forecast of 7.6% of GDP due to inflated energy subsidies.
- Regional Cash Issuance: The West African Economic and Monetary Union (UEMOA) continued heavy public securities issuance amid regional price pressures.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
The NSE ended the week of 6 November higher, supported by corporate earnings and strategic transactions.
- Friday turnover: Aggregate equity turnover was KSh 454.0 million on 6 November.
- Trading concentration: Safaricom accounted for 28.6% of the session’s total traded value.
Index moves are quoted from the week-ending summary; a banking-index close was not supplied.
| Index | Close | Change in week-ending summary |
|---|---|---|
| NSE All-Share (NASI) | 239.72 | +0.66% |
| NSE 20 | 4,187.52 | +2.18% |
| NSE Banking Sector Index | — | +3.05% |
Kenya Economy & Investment
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
Macroeconomics & Currency
- Shilling stability: The detailed 6 November forex table quotes USD/KES at 129.97, matching the supplied artwork; foreign-exchange reserves remain a buffer against seasonal shocks.
- Interest Rates: Treasury bill yields showed steadying behaviour, with the 91-day T-Bill rate holding firm at 8.75%.
- Inflation Pressures: Official figures point to rising consumer pressures, with annual inflation ticking up to 7.3% for October 2026, driven primarily by localized fuel and energy shocks.
International Investment Inflows
- US Portfolios Rebound: Fresh data from the US Treasury Department revealed that American individual and corporate portfolio holdings in Kenyan equities and bonds surged 45% over the past year to a four-year high of KSh 258 billion ($1.9 billion). Investors are heavily locking in attractive yields on long-term government infrastructure bonds.
- World Bank Economic Update: The newly released World Bank report notes that overall Foreign Direct Investment (FDI) inflows into Kenya defied broader geopolitical friction, rising by 170.5% to $2.74 billion for the year ending late 2026. The multilateral lender bumped Kenya’s H1 2026 GDP growth rate to a resilient 5.2%.
Kenya Corporate News
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
Quickmart IPO final allocation
- The financial headline of the day was the official allotment announcement for Quickmart PLC's oversubscribed KSh 15 billion Initial Public Offering (IPO).
- High Demand: The IPO achieved a 122.7% subscription rate, drawing KSh 18.41 billion in total valid bids against the targeted KSh 15 billion.
- Ownership allotment: Retail and regional institutional buyers were allotted 100% of valid applications. The UK-backed MOBILIST programme scaled back its cornerstone allocation to benefit domestic retail and foreign portfolios.
- Secondary Market: The selling shareholder, Sokoni Retail Kenya, maintains a 50% stake. Quickmart shares are scheduled to formally commence trading on the NSE on Thursday, November 12, 2026, under the ticker symbol QMRT.
Telecommunications & Fintech
- Safaricom Executive Appointment: Safaricom PLC formally announced the appointment of Boniface Mungania as the permanent Chief Financial Services Officer. Mungania, a long-serving executive who originally joined the telco in 2007 as a customer care representative, will now head the crucial M-PESA ecosystem. He succeeds Esther Masese Waititu and reports directly to Group CEO Peter Ndegwa.
Banking & Sustainable Finance
- 10-Year Green Lending Roadmap: The Kenya Bankers Association (KBA) officially unveiled the Banking Industry Sustainable Finance Roadmap, a decade-long framework (2027–2037) designed to aggressively mobilize private capital for climate-resilient projects. Developed in partnership with the IFC and WWF Kenya, the roadmap aims to address the country’s projected US$56 billion climate financing needs. It challenges the Central Bank of Kenya (CBK) to incorporate climate stress testing and explore differentiated reserve requirements to encourage sustainable lending to informal MSMEs.
Agriculture & Corporate Governance
- KTDA Leadership Wrangles: Tensions flared at the Kenya Tea Development Agency (KTDA) Holdings, following a sudden board election that ousted Chairman Enos Njeru. Njeru was replaced by James Githinji Mwangi. In a sharp public rebuttal, Njeru openly questioned the transparency and legality of the board process, claiming that the succession coup was motivated by external financial and political interference rather than smallholder tea farmers' interests.
World Bank Releases 34th Kenya Economic Update
- The World Bank officially launched its latest Kenya Economic Update, adjusting the country's 2026 economic growth forecast to 5.2% (up from 4.6% in 2025), driven by strong performances in the industrial and services sectors. Despite the positive growth narrative and strong foreign exchange reserves ($14.7 billion), the report heavily underscored that deep governance and anti-corruption reforms are mandatory to sustain long-term private investment and formalized job creation.
Global Oil Slump Hints at Local Fuel Relief
- Data released by the Central Bank of Kenya (CBK) showed Murban crude oil prices plummeted by 14.86% within a single week, dropping to USD 94.04 per barrel. This sharp decline comes just ahead of the Energy and Petroleum Regulatory Authority’s (EPRA) mid-month fuel price review scheduled for November 14, indicating potential pump price relief for Kenyan businesses.
Foreign Exchange & Rates
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
| Currency | 6 November KES rate | Weekly trend |
|---|---|---|
| USD | 129.97 | Flat |
| GBP | 174.45 | Pound strengthens from approximately 173.04 |
| EUR | 145.82 | Euro strengthens against KES |
Global currencies
- US Dollar Index (DXY): Rose 0.74% to 102.30, its largest daily percentage gain in nearly five months.
- Canadian dollar: Traded at 70.86 US cents, down from 71.48 US cents the previous day.
Interest-rate references
- US 10-year Treasury: 4.859%, after stronger-than-expected October jobs data.
- Kenya 91-day Treasury bill: 8.75%, as reported in the macroeconomic summary.
- Central Bank Rate: 8.75%, as supplied in the artwork.
Kenya Real Estate
Figures as at · Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
House prices and rents in Nairobi’s established suburbs rose in Q3 2026, while satellite towns and some middle-income apartment markets faced softer pricing.
House prices, rents and land
- Nairobi Suburb House Prices & Rents:
- Asking prices for houses in Nairobi's established suburbs increased by 2.3% in Q3 2026 to an average of Sh33.88 million.
- Rental prices in the suburbs grew by 2.7%.
- Top-performing neighborhoods included Spring Valley (house price appreciation of 6.8%), Westlands (5.9%), Muthaiga (5.5%), and Karen/Loresho (5.2%).
- Loresho led rental growth at 6.2% (average rent of Sh338,100–Sh350,100+), followed by Kitisuru (5.1%) and Muthaiga (4.5%).
- Nairobi Land Market Slowdown:
- Land prices in Nairobi suburbs grew by just 0.7% in Q3 2026—marking the slowest quarterly growth rate in three years as buyers pivot toward completed housing rather than speculative land holding.
- Satellite Towns:
- Property asking prices in satellite towns dipped slightly by 0.6% to an average of Sh14.43 million, while rental growth cooled to 0.4%.
- Affordable Housing & Promotions:
- President William Ruto handed over keys to 220 completed units at the Chepalungu Affordable Housing Project in Bomet County, implemented at a cost of roughly Ksh546.8 million.
- Private developers rolled out seasonal incentives, such as Cledun Realtors announcing Black November land discounts (up to KSh50,000 off select plots like Wema Court Phase II).
Mixed Fortunes for Middle-Income Apartment Rentals
- The apartment market is experiencing localized corrections. While leafy suburbs climbed, landlords in middle-income apartment hubs like Kileleshwa and Ruaka have been forced to lower rents, with Kileleshwa marking a notable 12% annual rental price decline due to expanding supply.
Impact of the Finance Act 2026 and Regulatory Brief
- The legal and tax landscape is actively altering developer math:
- Tax Pressures: The residential rental income tax rate has officially risen from 7.5% to 10%, with the KRA strictly enforcing landlord registrations. Furthermore, the elimination of the 15% preferential corporate tax rate means large-scale residential developers are now paying the standard 30% corporate rate.
- Zoning & Urban Disputes: A major Supreme Court development concerning high-rise approvals (up to 28 floors) on Rhapta Road, Westlands, has brought renewed scrutiny to unregulated urban development, signalling stricter zoning enforcement by county governments moving forward.
- Real Estate Sector: The National Environment Management Authority (NEMA) invited public feedback on a newly submitted Environmental Impact Assessment (EIA) for a mega 25-storey residential complex in Westlands, Nairobi by Flourish Haven Limited.
Emerging Asset Classes
- Data Centers as Real Estate: Digital infrastructure is officially the fastest-growing allocation for wealthy Kenyan investors, with institutional firms drawing massive capital layout into Nairobi-based tech real estate.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP forecast 2026
5.2%
World Bank 2026 forecast; distinct from historical quarterly GDP growth.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
Foreign exchange
USD / KES
129.97
Detailed 6 November forex table and supplied artwork.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026GBP / KES
174.45
6 November forex table.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026EUR / KES
145.82
6 November forex table.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
Equities
NSE All-Share
239.72
+0.66% in the week-ending summary.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026NSE 20-Share
4,187.52
+2.18% in the week-ending summary.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026Equity turnover
KSh 454 million
Friday, 6 November session.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
Rates
Central Bank Rate
8.75%
Prevailing policy rate from the supplied artwork.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 202691-day Treasury bill
8.75%
As reported in the macroeconomic summary.
As at
Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
At a glance
- 1The Nasdaq gains 1.09% and the S&P 500 rises 0.31% on Friday; Brent closes at US$99.26 after a weekly decline of more than 16%.
- 2NASI ends at 239.72 and NSE 20 at 4,187.52, with Friday turnover of KSh 454 million; Quickmart trading is scheduled to start on 12 November.
- 3Nairobi suburban house asking prices rise 2.3% in Q3 and rents gain 2.7%, while satellite-town asking prices fall 0.6%.
Sources
- Serrari Group desk compilation, 9 November 2026; Markets Snapshot – 6 November 2026
- Serrari Group supplied artwork, 9 November 2026
- Nairobi Securities Exchange — market statistics
- Serrari published Africa macro data