
11 November 2026
Wall Street falls after hotter US inflation, while Brent retreats to approximately US$89.50 a barrel. NASI closes at 239.04 on KSh 1.44 billion turnover, Safaricom’s half-year net income rises 35.9%, and lower building costs offer relief to self-builders.

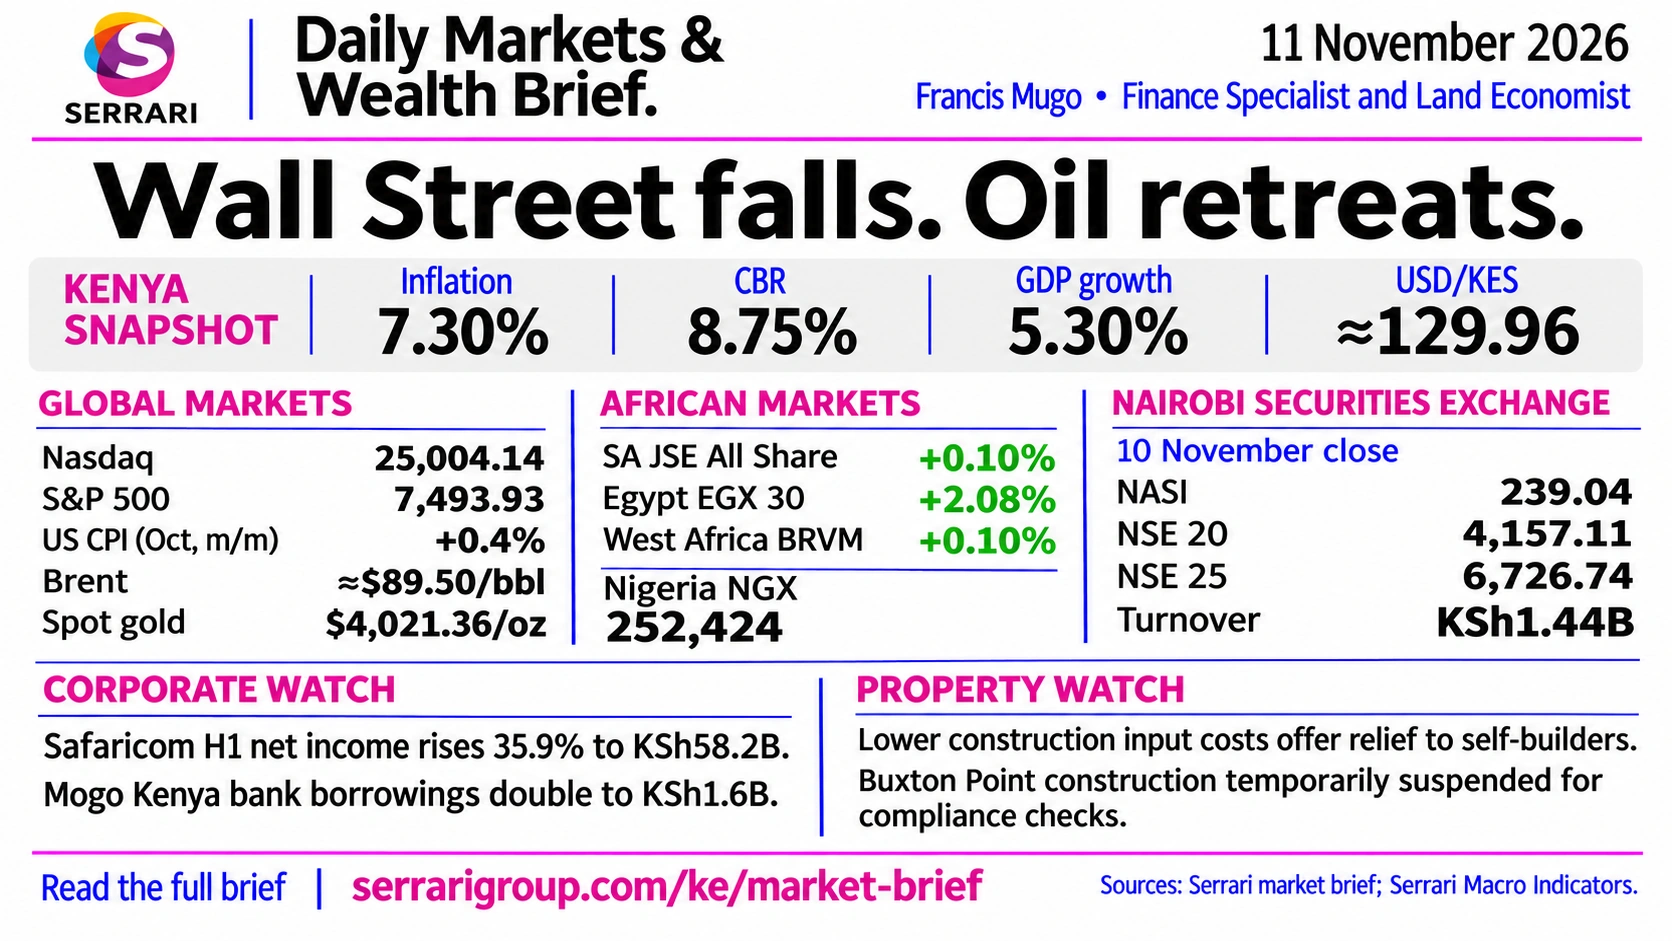
Global Markets
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
Wall Street falls after October US CPI rises 0.4% month on month, while European and Asian markets benefit earlier in the session from lower energy prices.
U.S. market highlights
- Stock Indices Slump: Wall Street fell sharply as investors reacted to the consumer price index (CPI) data. The Dow Jones Industrial Average dropped over 360 points (approx. 0.6%–0.7%), the S&P 500 fell about 0.9% (losing 56 points to 7,493.93), and the Nasdaq Composite slid roughly 1.4% (down 249 points to 25,004.14).
- Hotter Inflation Data: The U.S. consumer price index rose 0.4% in October on a seasonally adjusted basis (surpassing economist expectations of 0.3%), while core CPI climbed 0.3%. "Supercore" service prices (excluding housing and energy) rose 0.4%.
- Fed Rate Hike Expectations: The sticky inflation data increased market pricing and expectations for the Federal Reserve to implement another interest rate hike at its upcoming December meeting.
- Anthropic IPO Filing: Despite broader market jitters, AI startup Anthropic filed with U.S. regulators aiming for a valuation of roughly US$1.3 trillion in an upcoming IPO.
Canada market highlights
- TSX Falls: Canada's main stock index followed U.S. markets lower, with the S&P/TSX composite index dropping 284.87 points to close/trade at 36,161.39, dragged down largely by losses in the base metals sector.
- Currency and Commodities:
- The Canadian dollar weakened to 70.40 cents US, down from 70.81 cents US the previous day.
- December crude oil fell US$1.14 to US$85.71 per barrel.
- December gold dropped US$62.00 to US$4,052.50 an ounce.
- Institutional & Corporate News: CPP Investments reported a 0.5% loss for its second quarter, weighed down by fixed-income losses, and tensions continued around the layoff situation at the Stellantis/Roshel Brampton assembly plant.
Market Closings & Key Indices
- S&P/TSX Composite (Canada): Fell nearly 300 points, heavily weighed down by interest-rate-sensitive sectors.
- Nasdaq Composite (US): Led the Wall Street decline as higher yields pressured the technology sector.
- US Short-Term Bond Yields: The US 2-year Treasury yield surged 17 basis points following the inflation release.
The Catalyst: Hot October Inflation Data
- The market downturn was driven entirely by the October inflation metrics, which surpassed economic forecasts:
- Headline CPI: Increased 0.4% month-over-month on a seasonally adjusted basis, higher than the Dow Jones consensus estimate of 0.3%.
- Core CPI: Rose 0.3% month-over-month (excluding food and energy), which landed at the top end of expectations. Over the past three months, consumer prices excluding energy have accelerated at a 3.6% annualized rate.
- Rising Costs: Economists pointed out persistent pressure in non-energy categories, with consumer discretionary goods like dishes and flatware climbing roughly 12% year-over-year.
Central Bank Implications & Speculation
- The uncomfortably warm core inflation print heavily altered market expectations for upcoming central bank meetings in December:
- Federal Reserve (Fed): Federal Reserve Governor Christopher Waller indicated ahead of the data that a strong inflation reading could lean the Fed toward upsizing to a 50-basis-point interest rate hike at the December 9th meeting. Investors quickly began pricing in higher odds for aggressive monetary tightening.
- Bank of Canada (BoC): The Canadian bond market experienced a corresponding ripple effect, lifting BoC pricing for December back to a highly uncertain coin-toss decision.
Europe: Record Chasing and Energy Relief
- European shares rallied during the day as plunging energy costs mitigated regional margin pressures.
- Indices Performance: The pan-European STOXX 600 climbed 0.67% to 660.96, floating within 1% of its all-time record high. Germany's DAX and France's CAC 40 led the continental benchmarks with 1.3% gains.
- Sector Highlights: Banking equities drove the bulk of the market's gains, surging 2.6%.
- Macro Catalyst: Brent crude oil prices dropped another 1% to $91.56 a barrel, removing the heavy "stagflationary premium" that had burdened European industrial franchises throughout October.
- Webull Italian Expansion: Global fintech and digital broker Webull Corporation officially launched its brokerage services in Italy, allowing Italian investors to trade U.S. and European equities, European ETFs, and U.S. options via the Webull Trading Platform.
- Trilateral Ukraine-Russia Talks in Abu Dhabi: European officials—including representatives from the European Commission and European Council alongside delegations from France, Germany, and the UK—joined U.S.-hosted peace talks in Abu Dhabi focusing on maritime navigation in the Black Sea and infrastructure protection.
- COP31 Global Carbon Network Announcement: Convened by UN Trade and Development (UNCTAD), a new Global Carbon Market Network announced its launch lineup ahead of COP31 in Antalya, Türkiye, uniting exchanges and market actors (including the UK Carbon Market Forum and Astana International Financial Centre) to fix carbon market fragmentation.
- Corporate Earnings & Logistics: German industrial and consumer goods giant Henkel reported strong 9-month organic sales growth (4.3% organically), though Europe experienced slight softness compared to double-digit surges in the IMEA and Asia-Pacific regions. Meanwhile, Maersk updated low-water and heavy-load surcharges affecting European inland waterways and global shipping routes.
Asia-Pacific: Technical Rebounds & Trading Curbs
- Asian bourses staged a powerful tech-led rebound, recovering forcefully from the deep sell-offs sparked by the recent US midterm election results.
- South Korea’s Kospi Surge & Sidecar Trigger: South Korea’s benchmark Kospi index jumped 5.09% (and the Kosdaq surged over 4.73%) as Asian markets rebounded following a tech stock dip. The Korea Exchange briefly activated a "sidecar" mechanism to halt buy-side program trading for five minutes after the Kospi 200 futures index gained 5% or more.
- Japan (Nikkei 225): The index surged 2.78% as investors aggressively bought the dip in semiconductor names and assessed a newly released Bank of Japan summary indicating clear support for a December interest rate hike.
- China (CSI 300): Exhibited more cautious trading despite the central bank (PBOC) expanding its liquidity swap facilities to boost local equity buybacks.
- Broader Asia-Pacific Rebound: The Topix rose 1.77%, while Australia’s S&P/ASX 200 gained 1.19%, tracking a Wall Street tech rebound and lower oil prices.
- India’s Equity Influx: India’s NSE Nifty 50 jumped 2%, capping its strongest week since 2021 as investors funnelled capital into Indian equities seeking shelter from broader AI sector ructions.
- Philippine Economy Slows: Q3 economic growth in the Philippines came in slower than expected, placing its annual growth target under uncertainty as external trade and global tariff dynamics weigh on regional performance.
Latin America: The "Anti-AI" Value Haven
- Latin American markets drew focus as money managers began rotating capital out of expensive global tech infrastructure and into regional commodities.
- Export Boom: The Inter-American Development Bank (IDB) reported that goods exports from Latin America and the Caribbean grew 19.5% year-on-year in the first half of 2026, wildly outpacing the global trade expansion rate of 14.5%.
- Country Leaders: Peru (+30%) and Mexico (+26%) registered the fastest projected export paces, bolstered heavily by a 23.5% jump in mineral and metal export indexes.
- Bargain Hunting: Senior strategists noted that deeply discounted valuations in Brazilian utilities and banks have turned the region into a defensive anti-AI shelter against Wall Street volatility.
- MATRADE Diversification Push: Malaysia's external trade agency highlighted strong export acceleration into Latin American markets—notably Mexico (up 56% to RM39.4 million) and Chile (up 37% to RM32.8 million) through September 2026—as Asian exporters aggressively diversify away from single-market reliance.
- Emerging Market Bargains & South American Utilities: Global money managers and institutional investors pointed to rock-bottom valuations in emerging markets (trading at roughly 8 times forward earnings), specifically highlighting South American utilities and regional financial assets as high-dividend alternatives amid tech-heavy volatility.
- Shipping Surcharges to Latin America: Maersk issued rate and heavy-load surcharge adjustments (effective late November and December 2026) for cargo moving from Far East Asia to West Coast South America, Central America, the Caribbean, and Colombia.
Global Equity Indices
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
10 November snapshot. Approximate percentage moves are retained as supplied; the Canadian level is described as close/trade in the submission.
| Benchmark | Reported level | Session move |
|---|---|---|
| S&P 500 | 7,493.93 | About −0.9% |
| Nasdaq Composite | 25,004.14 | Roughly −1.4% |
| Dow Jones Industrial Average | Not supplied | Approximately −0.6% to −0.7% |
| S&P/TSX Composite | 36,161.39 | −284.87 points |
Global Commodities
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
Oil and precious metals retreat as geopolitical risk premiums ease and hot US inflation lifts rate expectations.
Energy: Deep Slump as Middle East War Geopolitics Ease
- Energy prices fell to their lowest levels since August following a drastic cooling of geopolitical tensions in the Middle East.
- The "Restraint" Sell-Off: Both benchmarks cratered after U.S. President Donald Trump indicated that further military strikes on Iran were "not a very necessary thing at this point," triggering algorithmic trend-followers to aggressively dump their bullish bets.
- Brent & WTI Benchmarks: Global benchmark Brent crude tumbled below $90 a barrel, dropping over 3% to settle near $89.50. West Texas Intermediate (WTI) matching the slide to hit $84.47.
- Supply Flow Resilience: Tanker traffic crossing the crucial Strait of Hormuz has quietly returned to pre-war volumes under international military coordination, entirely erasing the localized threat premiums that previously choked energy supply lines.
- Gasoline Relief: For the first time since July, the average U.S. consumer gasoline price dipped below $4.00 a gallon, easing core inflation worries for global central banks.
Precious Metals: Sharp Reversal on Hot U.S. Inflation
- Precious metals suffered an immediate punch as new macroeconomic updates forced a repricing of global interest rate expectations.
- Gold Plummets: After opening the day firmly above the $4,100 per ounce threshold, spot gold shed nearly 3% to fall to $4,021.36. The trigger was an October U.S. Consumer Price Index (CPI) report that printed at 0.4% (beating the 0.3% forecast).
- The Fed and the Dollar: The hot inflation print sent Treasury yields and the U.S. Dollar Index surging. Traders immediately priced in an 84% chance of a stricter Federal Reserve rate hike in December, severely diminishing the allure of non-yielding bullion.
- Silver and Platinum Squeeze: Mirroring gold's slide, silver futures shed over 4.1% to fall back to $51.30 per ounce, giving back all of its early-week momentum.
Industrial Metals & Agriculture: Shifting Demand Dynamics
- Industrial and agricultural assets navigated a mixed bag of corporate earnings beats, environmental constraints, and structural surpluses.
- Copper Flirts with Supply Tightness: London Metal Exchange (LME) three-month copper finished down roughly 1.1% to $13,675 a metric ton following the hot CPI data. However, the floor remains cushioned by tight physical supply chains inside China and strong industrial tech manufacturing.
- Mining Financial Windfall: Global miner Barrick Gold reported its quarterly earnings, logging a massive adjusted EBITDA of $3.46 billion. Despite localized weather shocks in South America, higher year-over-year realized metals pricing boosted its net revenues by 22%.
- Grains Await WASDE Catalyst: Soft commodities remained locked in cautious, flat trading ahead of the USDA's imminent November WASDE report. Corn futures crept up 0.5% while wheat languished near multi-month lows as market players monitor ongoing grain shipping corridor discussions between Russia and Ukraine.
Africa Markets
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
Daily comparison from the detailed table; weekly and year-to-date moves in the regional commentary describe separate periods.
| Market | 10 November close | Daily performance |
|---|---|---|
| Egypt EGX 30 | 52,483.46 | +2.08% |
| South Africa JSE All Share | 115,150.00 | +0.10% |
| Nigeria NGX All-Share | 252,424.00 | −0.01% |
| West Africa BRVM Composite | 520.74 | +0.10% |
Western Africa
- Regional Bond Reforms: Nigeria proposed sweeping capital market reforms to enable investors to seamlessly trade bonds across West Africa, unlocking long-term infrastructure funding.
- Debt and Diaspora Taps: Nigeria, Egypt, and South Africa combined owe China $17.2 billion, prompting the African Development Bank (AfDB) to deploy new structures to leverage diaspora investments.
- Equity Movements: The Nigerian stock market recorded a mild weekly contraction of 2.13% as part of mixed continental performances.
- IPO Megafunds: The Dangote Refinery IPO pulled ₦5.85 trillion ($4.1B) in orders, making it the largest public offering in African history. It was 3x oversubscribed.
- Listing Shifts: Dangote Cement cancelled its London secondary listing. Management cited changed market conditions to focus purely on African growth.
- Policy Reforms: Finance Minister Taiwo Oyedele proposed regional capital market reforms to allow cross-border bond trading across West Africa.
Northern Africa
- Market Outperformance: Egypt emerged as the continent's top weekly equity performer, with its stock market surging by 4.94%.
- Macroeconomic Pressure: Alongside Nigeria, Egypt remains under intense scrutiny regarding its share of the $17.2 billion debt footprint with Chinese lenders.
Eastern Africa
- Telecom Profit Surges: South Africa’s Vodacom reported a 25.7% half-year profit jump, heavily anchored by its pan-African expansion and the robust performance of its Safaricom deal.
- Industrial Expansion: The global lubricants manufacturer FUCHS officially launched a new joint venture in Kenya to solidify its distribution footprint across East Africa.
- Trade Declines: Kenya's export volumes to Middle Eastern markets shrank notably to Sh31.09 billion for the year, down from Sh42.23 billion in 2025.
Central Africa
- Subsea Cable Recovery: Internet connectivity across the Democratic Republic of Congo and neighbouring states is poised for relief; the West Africa Cable System (WACS) repair vessel arrives tomorrow to fix the October 29 fault.
- Currency Transition: Markets across Cameroon, Chad, and the CEMAC zone are finalizing adjustments following the recent Bank of Central African States deadline to withdraw historical CFA franc coins.
Southern Africa
- Macroeconomics: South Africa official unemployment rate rose to 33.7% in Q3 2026 (from 33.6%), reminding investors of sticky structural headwinds.
- Corporate News: Mining giant Sibanye Stillwater dropped 3.34%, while telecom player Vodacom surged 7.15% following positive updates from Safaricom.
- Historic IPO Listing: Botswana recorded its largest IPO in history; RMB successfully executed the BWP 1.66 billion ($121 million) listing of Kwa Nokeng Oil Limited on the Botswana Stock Exchange.
- Bullish Indexes: Both South Africa (+2.45%) and Namibia (+2.41%) registered robust stock market growth to lead sub-Saharan performance indices.
South Africa (JSE & ZAR)
- Stock Market Performance: The Johannesburg Stock Exchange benchmark index (SAALL) moved marginally higher, ending the session at 115,150 points (up 0.10%). Corporate highlights included Vodacom, which reported a 26% profit surge and announced plans to secure partners for building African AI data centres. Conversely, material stocks faced profit-taking, highlighted by Harmony Gold Mining Company sliding 5.26%.
- Forex Market: The South African rand (ZAR) faced selling pressure. A strengthening global greenback coupled with cautious sentiment ahead of domestic employment figures dragged the currency downward despite local energy grid stability improvements.
Nigeria (NGX & NGN)
- Stock Market Performance: The Nigerian Exchange (NGX) All-Share Index rested at 252,424 points. The week opened with an extraordinary ₦2.32 trillion capitalization surge, primarily anchored by Dangote Cement Plc climbing 9.61% on robust investor demand. On Tuesday, market turnover remained massive with ₦31.8 billion in transactions, where Champion Breweries led the single-day gainers, locking in a 10% maximum daily limit rise.
- Forex Market: The Nigerian naira (NGN) faced ongoing currency volatility. However, the sentiment remains supported by recent liquidity reforms and heavy interest surrounding the upcoming local listing of the Dangote Refinery.
Egypt (EGX & EGP)
- Stock Market Performance: The EGX 30 index jumped 2.08% to close at 52,483.46 points, registering a massive turnaround on a daily turnover of EGP 12.8 billion. The rally was driven cleanly by heavy-weight financial and retail assets, with EFG Holding soaring 6.8% and Abu Dhabi Islamic Bank (ADIB) gaining 5.1%. Egyptian domestic investors were aggressive net buyers.
- Forex Market: The Egyptian pound (EGP) steadied on the back of positive international assessments. Reports highlighted that Egypt successfully upgraded its position within global benchmarks (including MSCI and FTSE Russell emerging indices), noting zero current delays in foreign currency repatriation for external investors.
West Africa (BRVM & XOF)
- Stock Market Performance: The Francophone West African regional exchange (BRVM Composite Index) remained robust, hovering near the 520.74 point level (+0.10% on the day) after experiencing a substantial multi-week surge of over +44% year-to-date in dollar terms. Financial interest is currently heightened after the BRVM executive board confirmed structural changes, including expanding into futures, regional agricultural commodity contracts, and ETFs to deepen regional capital flows.
- Forex Market: The West African CFA franc (XOF), pegged tightly to the Euro, drifted lower alongside the Euro against a surging U.S. dollar as global geopolitical demand favoured the greenback.
Nairobi Securities Exchange
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
The detailed 10 November closing table shows a mixed session: NASI and NSE 20 edge lower, while NSE 10 and NSE 25 advance.
- Equity turnover: KSh 1.44 billion changed hands during the session.
- Aggregate market activity: 36.10 million shares traded across 11,126 equity deals; market capitalisation stood at KSh 4.01 trillion.
- Weekly context: The separate weekly summary reports gains of 2.2% for NSE 10, 1.3% for NSE 20, 2.3% for NSE 25 and 2.5% for the banking index.
10 November closing values and daily moves from the detailed NSE table.
| Index | Close | Daily change |
|---|---|---|
| NSE All-Share (NASI) | 239.04 | −0.10 points (−0.04%) |
| NSE 10 | 2,631.07 | +2.94 points (+0.11%) |
| NSE 20 | 4,157.11 | −7.10 points (−0.17%) |
| NSE 25 | 6,726.74 | +2.08 points (+0.03%) |
| Banking Sector Index | 278.59 | −0.11 points (−0.04%) |
Fixed Income & Central Bank Operations
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
- CBK Settlements: The Central Bank of Kenya handled a busy schedule of coupon and interest payments for major infrastructure and floating-rate/fixed-rate bonds, including FXD1/2026/030 (12.5%), FXD1/2022/015 (13.942%), FXD1/2022/025 (14.188%), and IFB1/2019/016 (11.750%), alongside settlements for reopened government paper.
- Sovereign Debt Profile: Following its active streak of Eurobond buyback operations (ranking high globally among IDA-eligible countries for smoothing near-term maturities like the 2027 and 2028 papers), demand for T-bills and new bond issues continues to run high.
Foreign Exchange & Rates
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
10 November CBK rates as quoted in the submission. All quotes are approximate.
| Currency pair | Approximate reported KES rate |
|---|---|
| USD / KES | ≈129.96 |
| GBP / KES | ≈173.75 |
| EUR / KES | ≈144.93 |
Kenya Economy & Policy
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
- Africa Financial Markets Index: Kenya recently climbed to 5th place in the 2026 Absa Africa Financial Markets Index (up from 7th), propelled by improved market transparency, stronger bond and stock trading, and new dollar-denominated securities listed on the Nairobi Securities Exchange.
- Budget & Treasury: The National Treasury is actively receiving Sector Budget Proposals this week ahead of upcoming fiscal framework consultations.
Kenya Corporate News
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
Financial Services
- Mogo Doubles Bank Loans to KES 1.6 Billion: Digital and asset financier Mogo Kenya has doubled its local bank borrowings to KES 1.6 billion, securing key credit facilities from Ecobank Kenya and I&M Bank. The funding push matches an explosive growth curve in Kenya's digital credit pool, which hit KES 153.8 billion.
Telecommunications
- Safaricom H1 Profits Hit KES 58.2 Billion: Safaricom Plc injected strong positive sentiment into the NSE after announcing a 35.9% surge in group net income to KES 58.2 billion for the half-year ended September 30, 2026. The historic earnings were powered by its mobile financial services arm, M-Pesa, which crossed the KES 100 billion revenue mark in a six-month reporting cycle for the first time.
Corporate Actions & Dividends
- A flurry of prominent companies have confirmed upcoming book closures and corporate payouts on the Nairobi Securities Exchange Corporate Action Calendar:
- Carbacid Investments Plc: Announced a final dividend of KES 2.00 per share (Books closure: November 27, 2026).
- Kenya Power & Lighting Co (KPLC): Confirmed a final dividend of KES 1.20 per share (Books closure: November 27, 2026).
- TRIFIC Green USD I-REIT: Declared an interim distribution of USD 0.02 per unit (Books closure: November 20, 2026).
- ALP Industrial REIT: Confirmed an interim dividend of USD 0.0207 per unit (Books closure: November 18, 2026).
State Corporations & Infrastructure
- NTSA Top Management Shakeup: The National Transport and Safety Authority (NTSA) has formally declared vacancies for 16 senior leadership positions, opening a massive structural overhaul spanning its road safety, compliance, vehicle licensing, and internal audit segments.
- CRBC Infrastructure Runs Ahead: China Road and Bridge Corporation (CRBC) continues to bag multi-billion shilling state construction contracts for ongoing Standard Gauge Railway (SGR) extensions across the country despite historical international funding freezes.
Additional dividend calendar
- EABL books closed for a final dividend of KSh 8.70 per share; BOC Kenya processed an interim dividend of KSh 4.00 per share.
- Kenya Pipeline Company’s final dividend is KSh 0.32 per share, with books closing on 30 November. The dedicated corporate-action list specifies 18 November for ALP Industrial REIT’s USD 0.0207 per-unit interim dividend book closure.
Kenya Real Estate
Figures as at · Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
Q3 2026 trends from the supplied property overview, distinct from the daily market snapshot.
| Market segment | Q3 2026 price trend | Areas highlighted | Reported context |
|---|---|---|---|
| Nairobi suburban houses | +2.3% | Spring Valley, Westlands, Muthaiga | Strong rental yields and expatriate demand |
| Satellite-town houses | −0.6% | Ngong, Ongata Rongai | Softer demand after earlier price increases |
| Satellite-town land | +0.65% | Ruiru, Juja outperform | Growth slowed; underperforming Treasury bills |
Relief for self-builders
- A widening divide has appeared between buying ready-made homes and building independently. While purchasing developed properties is increasingly expensive, cheaper construction inputs and building materials are providing notable relief to those with active construction sites or off-plan developments.
Improving Credit Conditions
- Market activity is being bolstered by a friendlier monetary environment. The Central Bank of Kenya (CBK) base rate cuts over the past two years have successfully driven average commercial lending rates down to 14.4% (down from a stinging 17.2% two years earlier). Coupled with a 10.6% growth in private sector credit, buyers are finding it easier to secure property financing.
Regulatory & Fraud Crackdowns
- Karen Land Fraud Arraignments: Two prominent company directors were officially charged at the Milimani Law Courts following a November 6 arrest over an alleged KSh 25 million land fraud scheme involving forged title documents in Karen.
- Buxton Point Project Suspended: In coastal news, the Mombasa County government has abruptly ordered a temporary suspension of construction works at the multi-billion shilling Buxton Point Affordable Housing project citing ongoing regulatory non-compliance checks.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.96
Approximate CBK quote as reported in the submission.
As at
Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026GBP / KES
173.75
Approximate CBK quote as reported in the submission.
As at
Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026EUR / KES
144.93
Approximate CBK quote as reported in the submission.
As at
Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
Equities
NSE All-Share
239.04
Daily: −0.10 points (−0.04%).
As at
Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026NSE 20-Share
4,157.11
Daily: −7.10 points (−0.17%).
As at
Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026NSE 25-Share
6,726.74
Daily: +2.08 points (+0.03%).
As at
Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026Equity turnover
KSh 1.44 billion
10 November aggregate session turnover.
As at
Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
Rates
Central Bank Rate
8.75%
Prevailing policy rate from the supplied artwork.
As at
Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
At a glance
- 1October US CPI rises 0.4% month on month; Wall Street falls and Brent settles near US$89.50 a barrel.
- 2NASI closes at 239.04, NSE 20 at 4,157.11 and NSE 25 at 6,726.74, with aggregate equity turnover of KSh 1.44 billion.
- 3Safaricom half-year net income rises 35.9% to KSh 58.2 billion; cheaper construction inputs support self-builders while Buxton Point faces a temporary suspension.
Sources
- Serrari Group desk compilation, 11 November 2026; Markets Snapshot – 10 November 2026
- Serrari Group supplied artwork, 11 November 2026
- Nairobi Securities Exchange — market statistics
- Serrari published Africa macro data