
12 November 2026
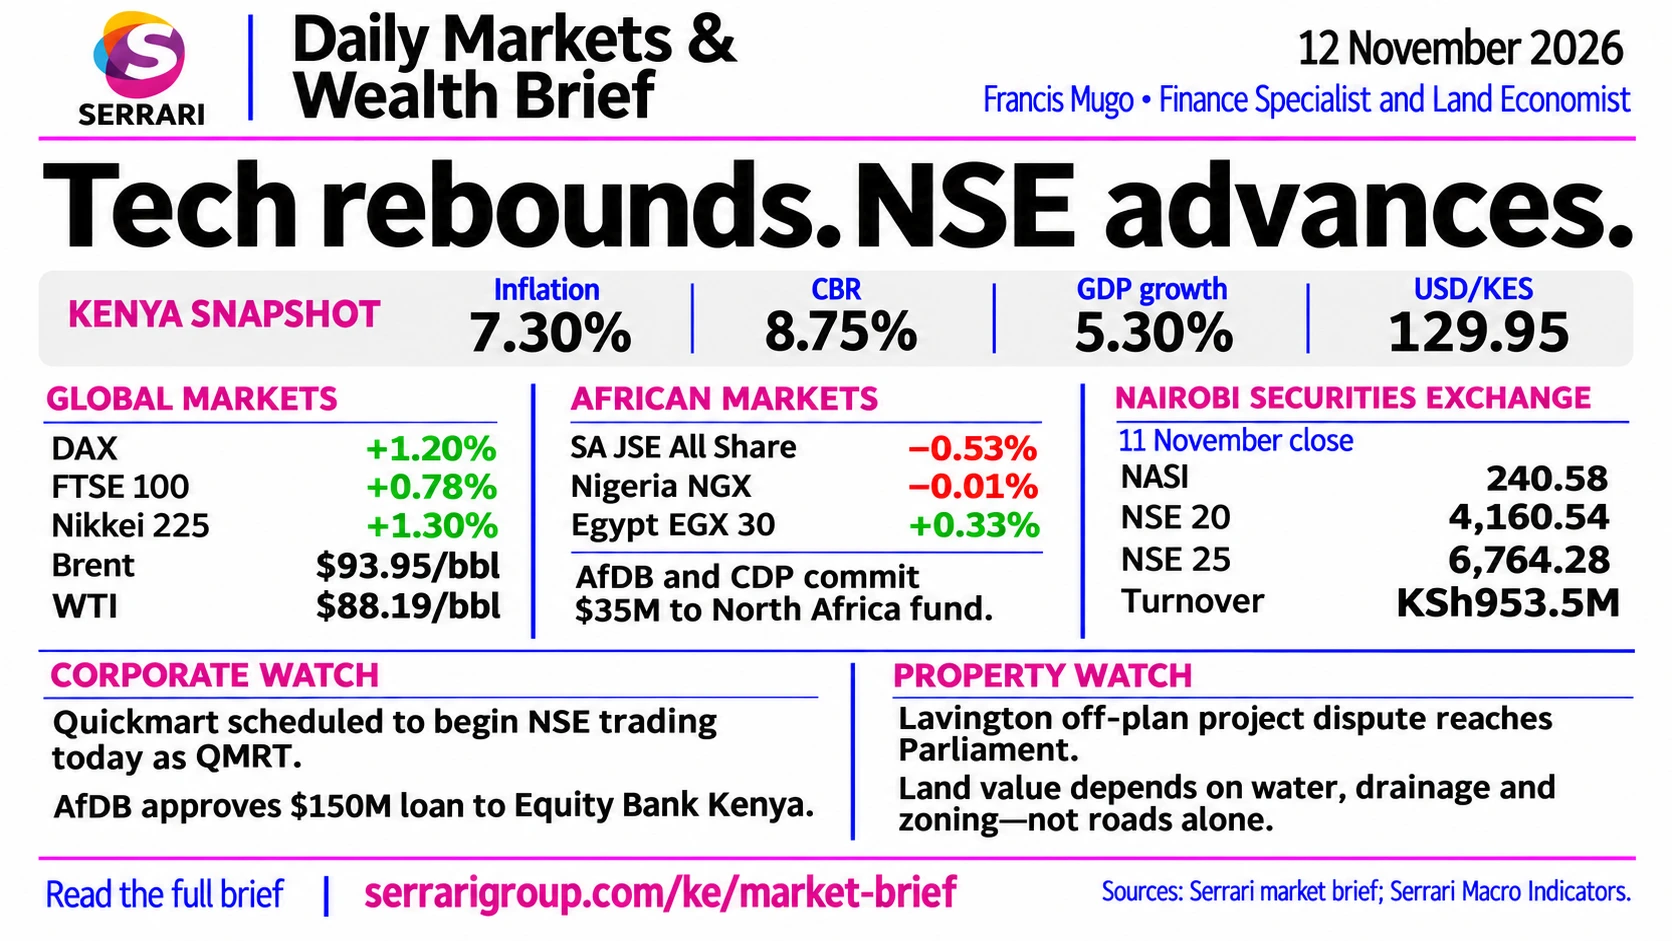
AI stocks led a broad rebound as CoreWeave surged over 20% and Germany’s DAX rallied 1.20%, while hot US inflation lifted the dollar index to a 19-month high. In Nairobi, the NASI rose 0.64% to 240.58 as Quickmart prepared to debut on the NSE as QMRT.

Global Markets
Figures as at · Closing levels for Wednesday 11 November 2026, as reported in this brief
North and Latin American equities staged a broad rebound fuelled by a surge in artificial intelligence stocks, and Europe and Asia followed on AI chip demand and moderating crude prices. The US dollar strengthened across forex markets after hot US inflation data reinforced bets on a December Federal Reserve rate hike.
Major currency pairs — October US CPI pushed 10-year Treasury yields to 5.00%
| Pair | Session performance and key levels | Primary driver |
|---|---|---|
| USD/JPY | Rose toward 159.66 (from 158.80), testing 10-week highs and key 160.00 resistance | Widening US–Japan yield differentials as traders price in a December Fed hike |
| EUR/USD | Fell to ~$1.1092–1.1127 (from $1.1164 on Tuesday) | Broad dollar strength and lingering concern over French public finances |
| GBP/USD | Declined to ~$1.3273 (from $1.3345) | Dollar rally offset UK economic resilience and Bank of England rate expectations |
| EUR/GBP | Edged lower to ~0.8358–0.8362, though options turned bullish on a euro rebound | Traders bet pessimism over French fiscal risk is overdone relative to sterling |
United States
- Tech-led equity rally: Major indexes recovered from Tuesday’s pullback: the Nasdaq Composite climbed roughly 1.9% to 2.3%, the S&P 500 gained about 1.5% to 1.6%, and the Dow posted a smaller advance of 0.1% to 0.5%.
- AI catalysts: CoreWeave surged over 20% after beating third-quarter revenue estimates and raising full-year guidance. Reports of an oversubscribed IPO for Anthropic and a 2.7% to 4% rebound in Nvidia lifted confidence in the AI trade further.
- Bond market closure: Cash Treasury trading was closed for Veterans Day, a pause after Tuesday’s selloff pushed the 10-year yield briefly above 5% following a hotter-than-expected October CPI print of 0.4% month on month.
Canada and Latin America
- TSX gains: The S&P/TSX Composite rose about 250 points (0.79%) to trade near 36,420–36,456, supported by energy, technology and base metals.
- Oil rebounds while gold slips: December WTI rose $1.94 to near $87.98 a barrel, while December gold fell $17.70 to $4,012.50 an ounce on higher rate expectations.
- Regional equities advance: Brazil’s Ibovespa gained 0.91% to 172,895, clawing back ground after a steep monthly pullback, and Mexico’s IPC rose 0.73% to 72,418.
- Banking focus: Regional lenders stayed in the spotlight alongside European peers as investors digested third-quarter results and tighter global monetary conditions.
Americas forex
- Dollar index: Climbed 0.67% to 102.91, a 19-month high. Hawkish Fed commentary, including Governor Christopher Waller leaning toward a 25 basis point hike in December, kept pressure on the greenback.
- Canadian dollar: Slid to four-week lows, with USD/CAD up roughly 0.36% to 0.39% at around 1.4240–1.4245 (70.24 US cents).
- Latin American currencies: The Mexican peso softened, with USD/MXN near 18.63. The Brazilian real held steady around 5.56 per dollar, supported by the central bank’s pause in rate cuts.
Europe
- Major indices: Germany’s DAX led with a 1.20% rally to 26,662.77. London’s FTSE 100 advanced 0.78% to 10,835.47 and France’s CAC 40 added 0.66%.
- Corporate movers: Siemens Energy jumped over 8% after record quarterly revenue of €12.83 billion and higher long-term targets on data centre power demand. Edenred surged 6.4% after a favourable court ruling in Brazil, and Infineon gained after forecasting over 20% revenue growth in 2027.
- Sectors: Basic resources, banks and technology hardware led, shrugging off concern over French fiscal stability.
Asia
- Semiconductor rallies: Taiwan’s Taiex surged 3.6% as TSMC jumped 3.1% on a 59.7% annual rise in October revenue. South Korea’s Kospi climbed 2.4% to 5,365.75, led by Samsung Electronics (+3.4%) and SK Hynix (+5.4%).
- Japan and India: The Nikkei 225 gained 1.3% to 61,248.59, even as SoftBank Group dipped 0.4% after a 1.1 trillion yen quarterly net loss. India’s BSE Sensex rallied 0.95% (772.75 points) to 81,879.40 on foreign inflows and easing oil prices.
- China diverges: The Shanghai Composite finished up 0.6% at 3,685.27 as Singles’ Day began, while Hong Kong’s Hang Seng slipped 0.7% to 24,387.06.
- Emerging Asian currencies: The Indian rupee strengthened slightly to near 93.70 per dollar on lower crude prices, while the South Korean won traded near 1,487.57 per euro.
Commodities
Figures as at · Prices for 11 November 2026, as reported in this brief
Crude oil and precious metals rebounded from steep prior-session selloffs as geopolitical supply risks and tighter agricultural forecasts outweighed a stronger dollar.
Precious and industrial metals
| Commodity / market | Session performance and key levels | Primary driver |
|---|---|---|
| Gold (spot / COMEX) | Stabilised near $4,050–$4,055/oz, holding key support at $4,000 | Higher US yields and a stronger dollar capped gains; dip-buying emerged after Tuesday’s CPI-driven drop |
| Silver (COMEX / MCX) | Rallied ~2.3% on COMEX to $52.41/oz; Indian MCX silver jumped 1.61% to ₹1,85,514/kg | Strong Asian physical and futures buying recovered nearly all of Tuesday’s losses |
| Aluminium (China) | Edged lower across Chinese trading hubs | Mysteel Global data showed Chinese stockpiles rising for two days, easing supply fears |
| European materials | Basic resources stocks gained alongside broader equities | Encouraging guidance from industrial and power-infrastructure firms |
Energy
- Crude oil: WTI climbed roughly 2.5% to $88.19 a barrel and Brent rose to $93.95 after dipping to 11-week lows earlier in the week on hopes of easing US–Iran tensions. Across European and Asian hours Brent traded between $92.55 and $93.94 (touching intraday highs above $95) and WTI at $86.76–$88.19, as reports of shipping attacks and stalled nuclear talks restored a risk premium. Brent was also quoted at $92.65–$92.72 in forex trading.
- European natural gas: Dutch TTF futures rose 1.44% to 2.68%, settling near €85.95–€87.00/MWh on colder weather, weak wind generation and EU storage below 75% at the start of November.
- Regional impact: Earlier oil weakness relieved Asian importers such as India, though Goldman Sachs raised its December Brent forecast to $105 a barrel on Gulf supply risks.
Americas
- Precious metals: Spot gold edged up to near $4,005–$4,044 an ounce after a nearly 3% selloff on the October CPI data, and was also quoted near $4,030–$4,047. Silver gained roughly 1.5% to $52.27.
- Grains: December CBOT wheat slipped 2¼¢ to $5.90½ a bushel and corn traded lower around $4.45 on shifting US weather.
- Canada: ICE canola was closed for Remembrance Day, leaving the January contract at $770.40 a tonne. Recovering gold, silver and copper lifted TSX resource stocks, Barrick Mining filed for a New York IPO of its North American business, and Conifex Timber reported continued lumber weakness despite US duties falling to 24.75%.
- Latin America: Comex copper gained nearly 1% to $6.28–$6.30 a pound. Southern Copper is prioritising a $10.3 billion ($15 billion AUD) investment pipeline in Peru over the next decade. ECLAC projects Latin American goods exports up 20% in 2026 to $1.9 trillion, led by Peru (+30%) and Bolivia (+23%), and wetter weather across South America is being watched for planting.
Agriculture
- Grains and oilseeds rally: Corn and soybean futures rallied from multi-month lows after the USDA cut US production and ending-stock projections more than expected; wheat climbed alongside.
- European trade flows: After the 66th European Commodities Exchange in Rotterdam, traders focused on Black Sea export logistics and tight feed-grain balances.
Africa
Figures as at · Closing levels for 11 November 2026, as reported in this brief
Major African stock indices
| Index | Close | Daily change | Primary catalyst |
|---|---|---|---|
| JSE FTSE All Share (South Africa) | 114,090.59 | -0.53% | Global hawkish sentiment; local consumer discretionary selling (Mr Price -2.29%) |
| NGX All-Share (Nigeria) | 252,289.45 | -0.01% | Profit-taking in heavy banking stocks (Zenith, Stanbic) offsets local gainers |
| EGX 30 (Egypt) | 52,656.99 | +0.33% | High institutional turnover; heavy bids into Abu Qir Fertilizers (+5.0%) |
Southern Africa
- AGOA friction: Facing fears of exclusion from the US African Growth and Opportunity Act, Pretoria has pivoted toward Beijing for expanded bilateral trade arrangements.
- Corporate boost: Vodacom shares jumped on robust interim results, with its domestic prepaid business returning to growth and data margins climbing to 37.4% EBITDA.
East, West and Central Africa
- Kenyan coffee in China: Kenyan coffee producers are scaling up operations and distribution in China on growing demand and easing trade barriers.
- Kenya’s ranking: Weaker localised growth projections have pulled down the investment rankings of prominent hubs such as Kenya.
- West Africa: The region holds a 4.6% growth projection for 2026, outperforming the continent on diversification and a push for financial sovereignty. Nigeria and Ghana have advanced as targets for global venture capital.
- Central Africa: Growth is trending toward 3.8% for 2026 on oil and mineral price premiums. In eastern DRC, institutions are rolling out decentralised platforms such as DMT School to safeguard student records amid volatility.
North Africa
- Mid-market capital: The African Development Bank and Italy’s Cassa Depositi e Prestiti finalised a joint $35 million equity investment in the RMBBV North Africa Fund 3, for mid-market scale-ups in consumer goods, private healthcare and fintech across Egypt, Morocco and Tunisia.
Regional forex
- USD/ZAR: R16.5917, -0.46% (rand depreciated), on a stronger greenback and weak domestic data. The rand traded around 16.6, its weakest since early November, as Q3 unemployment hit a four-year high of 33.7%.
- USD/NGN: ₦1,350.86 official; ₦1,411–₦1,430 parallel; -0.11% (naira depreciated). Bureau de change desks sold at ₦1,419 to ₦1,430, and the official–parallel gap remains manageable under the CBN’s FX unification reforms.
- USD/EGP: EGP 53.5125, +0.63% (pound appreciated), on strong institutional turnover. National Bank of Egypt windows offered EGP 53.27 buying and EGP 53.37 selling, well clear of October’s multi-month low near EGP 56.27.
- USD/XOF: 616.71 (derived from 0.001702 USD), -0.61% (CFA depreciated), tracking the weakening euro peg and raising costs for importers of dollar-priced energy.
Nairobi Securities Exchange
Figures as at · Nairobi Securities Exchange session data for 11 November 2026, as reported in this brief
Broad market benchmarks closed in positive territory.
- Turnover and capitalisation: Market capitalisation climbed 0.62% to KSh 4.04 trillion, while equity turnover fell 33.83% to KSh 953.5 million from KSh 1.44 billion in the prior session.
- Top gainer and loser: Nairobi Business Ventures led the gainers; Shri Krishna Overseas was the day’s heaviest loser.
- Foreign flows: Foreign investors recorded net inflows of KSh 107.5 million, a sharp reversal from the previous session’s net outflows of KSh 435.8 million.
- Vodacom and Safaricom: Vodacom Group’s interim results showed its financial services revenue up 99%, padded by sustained organic growth at Safaricom.
NSE indices, 11 November close
| Index | Close | Daily change | % change |
|---|---|---|---|
| NSE 10 Share Index | 2,650.24 | +19.17 | +0.73% |
| NSE All Share Index (NASI) | 240.58 | +1.54 | +0.64% |
| NSE 25 Share Index | 6,764.28 | +37.54 | +0.56% |
| Banking Sector Index | 280.35 | +1.76 | +0.63% |
| NSE 20 Share Index | 4,160.54 | +3.43 | +0.08% |
Kenya Forex, Fixed Income and Policy
Figures as at · Central Bank of Kenya and government releases, as reported in this brief
Forex
- USD/KES: The shilling remained stable at KSh 129.95 per US dollar.
- GBP/KES: 161.40 KES, marginally down.
- EUR/KES: 137.65 KES, stable.
- UGX/KES: 28.60 UGX, stable.
- TZS/KES: 20.15 TZS, stable.
Macroeconomics and fixed income
- Bond market activity: Secondary bond turnover rose 9.68% to KSh 26.85 billion as the CBK pushes a Sh50 billion Treasury bond tap sale offering yields of up to 12.857%.
- Investment pipeline: The Ministry of Investments, Trade and Industry said Kenya’s investment pipeline has reached KSh 2.6 trillion, including the proposed Dangote East Africa refinery in Lamu’s Special Economic Zone.
Banking and monetary policy
- AfDB loan to Equity Bank: The African Development Bank approved a $150 million, 8-year subordinated loan to Equity Bank Kenya, part of Equity’s wider $500 million recapitalisation programme to expand long-term SME financing.
- Next MPC meeting: The CBK’s next Monetary Policy Committee meeting is on 9 December 2026. The Central Bank Rate stands at 8.75%.
Kenya Corporate News
Figures as at · As reported in this brief
Capital markets and securities regulation
- Parliament probes CMA over Quickmart: The National Assembly’s Public Investments Committee questioned the Capital Markets Authority on investor protection around Quickmart’s KSh 15 billion IPO, raising concerns over operating cash flows and noting the proceeds go to the selling shareholder, Sokoni Retail Kenya, not the business.
- Quickmart debut: Quickmart is slated to begin trading on the NSE on Thursday 12 November 2026 under the ticker QMRT. The IPO closed 22.7% oversubscribed, with KSh 18.41 billion in applications.
- Suntra order upheld: The High Court upheld a CMA order directing Suntra Investments to restore 212,500 Safaricom shares wrongly allocated during the 2008 IPO and pay KSh 2.4 million in accrued dividends to Wanjugi Discount Stores Limited.
Regulatory shocks and compliance
- Trust registrations paused: The Business Registration Service suspended manual trust registration applications while it moves to a digital system under the Trust Administration Act, 2026.
- CAK fine warning: The Competition Authority of Kenya launched a crackdown on retailers imposing unfair terms on suppliers; executives risk a KSh 10 million fine or five years in prison.
- CBK capital ultimatum: The CBK warned 11 commercial banks they face possible closure if they miss the revised KSh 3 billion minimum core capital. Government-backed Consolidated Bank of Kenya has the largest gap, a KSh 3.7 billion deficit.
Corporate finance and expansion
- Mogo Kenya: Secured matching commitments from local institutions, doubling its domestic bank facility to KSh 1.6 billion and lifting its local funding pool beyond KSh 9 billion, via private placements managed by Dry Associates Investment Bank.
- Sports finance accelerator: The Ministry of Sports and the African Sports and Creative Institute unveiled a roadmap for private capital in sports infrastructure beyond AFCON 2027, including the Baobab Deal Room pitching programme for sports technology, equipment and media SMEs.
Real Estate
Figures as at · As reported in this brief
Parliament and consumer protection
- Lavington off-plan default: Embakasi East MP Babu Owino raised in Parliament the stalled Terrace Apartments project on Hatheru Road, Lavington, where about 110 Kenyans who invested off-plan between 2016 and 2018 risk losing their money after a bank auctioned the property on a developer loan default. He called for strict oversight of off-plan housing.
Commercial development and policy
- Infrastructure disconnect: GulfCap Real Estate analysis cautioned that highway connections do not automatically create land value if drainage, sewerage, water connections and zoning enforcement fail to keep up.
- Finance Act squeeze: Under the Finance Act 2026, property transferred to REITs keeps its capital gains tax exemption, but residential rental income tax rose from 7.5% to 10%, and the end of the 15% corporate tax rate for developers building over 100 units a year doubles their rate to the standard 30%.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.95
Stable
As at
As reported in this briefGBP / KES
161.40
Marginally down
As at
As reported in this briefEUR / KES
137.65
Stable
As at
As reported in this brief
Equities
NSE All-Share (NASI)
240.58
+1.54 (+0.64%)
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,160.54
+3.43 (+0.08%)
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,764.28
+37.54 (+0.56%)
As at
Nairobi Securities Exchange, as reported in this briefNSE 10
2,650.24
+19.17 (+0.73%)
As at
Nairobi Securities Exchange, as reported in this briefNSE Banking Index
280.35
+1.76 (+0.63%)
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 953.5M
-33.83% from KSh 1.44bn
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KSh 4.04tn
+0.62%
As at
Nairobi Securities Exchange, as reported in this briefForeign net flows
+KSh 107.5M
Previous session: net outflow of KSh 435.8M
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
Next MPC meeting 9 December 2026.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this brief
At a glance
- 1AI demand drove a broad rebound: CoreWeave surged over 20%, Taiwan’s Taiex jumped 3.6% on TSMC, and Germany’s DAX rallied 1.20% as Siemens Energy rose over 8%.
- 2Hot October US inflation (+0.4% month on month) kept a December Fed hike in play, pushing the dollar index to a 19-month high of 102.91.
- 3Quickmart begins trading on the NSE today as QMRT after its KSh 15 billion IPO drew KSh 18.41 billion in applications, even as Parliament questioned the CMA over investor protection.
Sources
- Serrari Group desk compilation, 12 November 2026; Markets Snapshot – 11 November 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data