
13 November 2026
Quickmart made its Nairobi Securities Exchange debut after a KSh 15 billion IPO, lifting every NSE index as NASI rose 0.40% to 241.55. Globally, Nvidia fell sharply after Jensen Huang’s exit while Germany’s DAX broke above 27,000 for the first time.

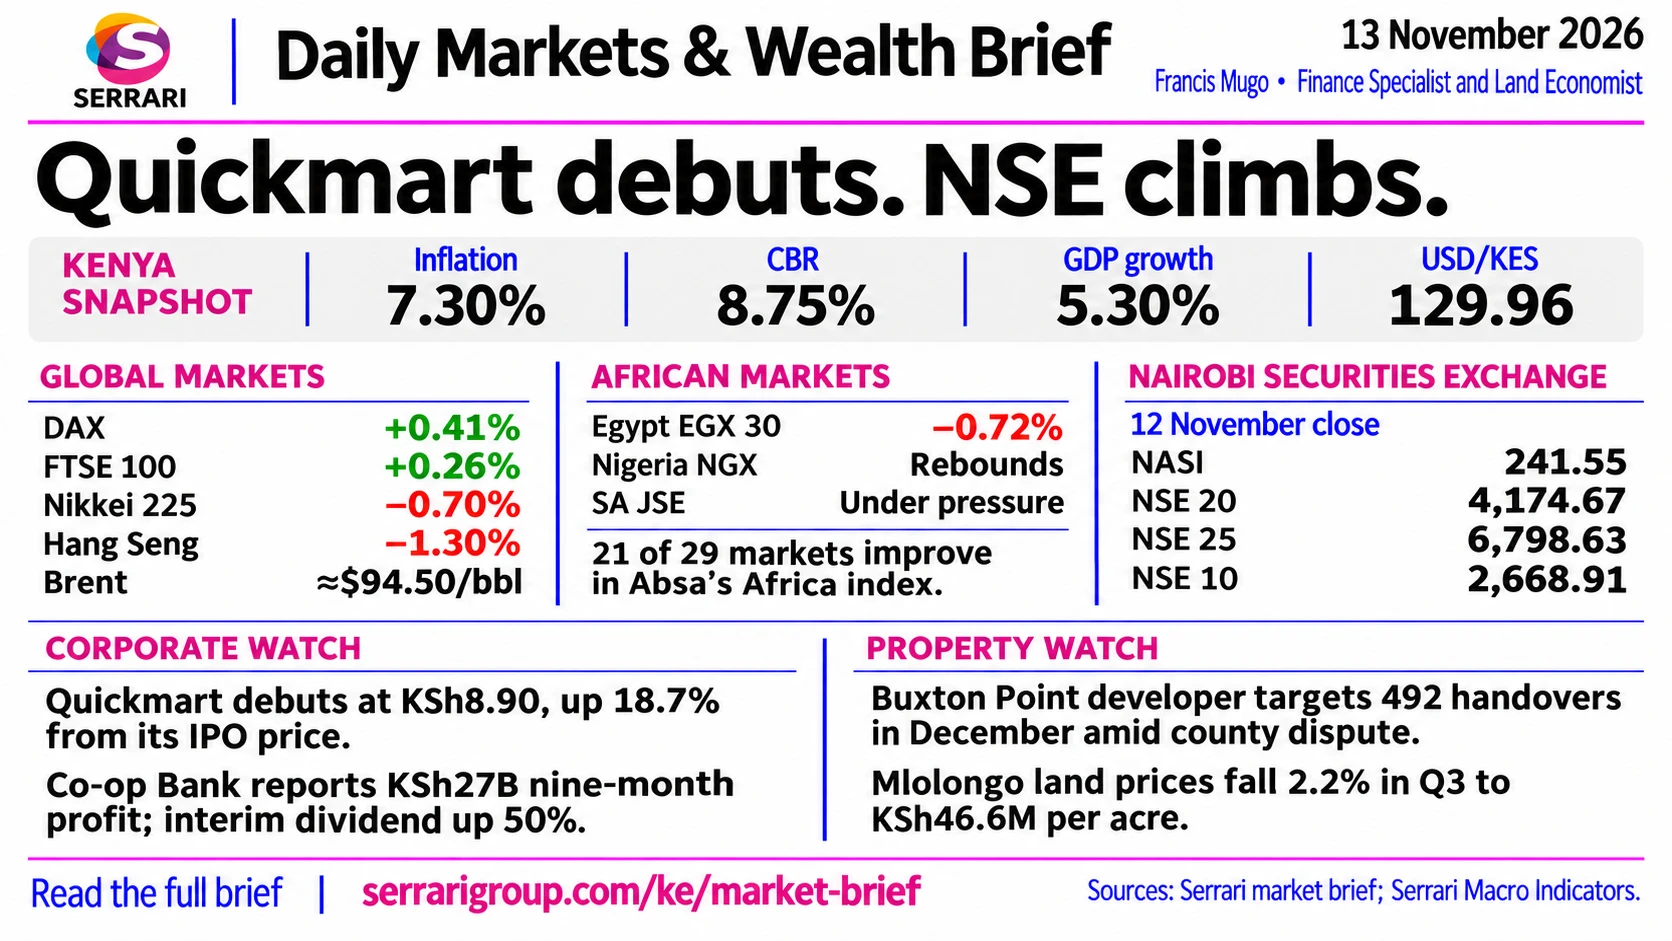
Global Markets
Figures as at · Market data for Thursday 12 November 2026, as reported in this brief
Markets across the Americas had a volatile session, dominated by a leadership shake-up at Nvidia, rising energy prices and shifting rate expectations. Europe and Asia diverged: European stocks hit fresh records on strong earnings while Asian equities retreated on semiconductor turmoil and a stronger dollar.
Major pairs — elevated Treasury yields and expected Fed hikes kept major peers on the defensive
| Pair | Intraday range | Session close / late trade | Key takeaway |
|---|---|---|---|
| USD/JPY | 159.51 – 159.99 | ~159.87 | Tested the 160.00 threshold amid Bank of Japan intervention warnings |
| EUR/USD | 1.1065 – 1.1110 | ~1.1081 | Pressed to multi-month lows on diverging Fed and ECB rate outlooks |
| GBP/USD | 1.3200 – 1.3340 | ~1.3250 | Slipped toward critical yearly trend support despite resilient UK data |
| AUD/USD | 0.6820 – 0.6860 | ~0.6841 | Weakened to multi-month lows as global yield differentials weighed on risk appetite |
| USD/CAD | 1.4210 – 1.4310 | ~1.4280 | Extended gains toward yearly highs on broad greenback momentum |
United States
- Major indices: US equities traded lower in the afternoon. By mid-afternoon in New York the S&P 500 had slipped 0.3% (after opening near 7,619), the Nasdaq 100 declined 0.4% and the Dow edged down 0.1%.
- Nvidia leadership crisis: Nvidia shares tumbled between 6% and 9% after the resignation and ouster of longtime CEO Jensen Huang amid personal conduct allegations and a US probe into alleged product smuggling. CFO Colette Kress was appointed interim CEO. Super Micro Computer fell 9%, while AMD gained as an alternative chip supplier.
- Bonds and macro: Reopening after Veterans Day, Treasury yields climbed as crude rallied and traders priced in potential Fed hikes after Tuesday’s hot CPI. Markets also watched weekly jobless claims and a key 30-year bond auction.
- Corporate movers: HubSpot rallied over 7% on strong earnings and co-founder Brian Halligan’s return to leadership; investors positioned ahead of after-hours results from Cisco Systems and Applied Materials.
Canada and Latin America
- S&P/TSX Composite: Traded down roughly 0.2% to 0.5%, near 36,244–36,343 after closing Wednesday at 36,412.
- Sectors: Base metals and mining weighed as December gold fell over $120 to roughly $3,880 an ounce. Healthcare and financials were subdued, while information technology jumped over 2%.
- Currency and economy: The Canadian dollar weakened to near 70.15 US cents as investors weighed a recent Bank of Canada hike, cooling unemployment (6.7%) and US–Canada tariff risks into 2027.
- Regional benchmarks: Entering Thursday, Brazil’s Bovespa stood near 172,060 (+0.42% prior close) and Mexico’s S&P/BMV IPC near 72,006 (+0.16% prior close).
- Investment: WEG announced a $250 million investment in Mexico through 2030 to expand transformers, generators and energy storage for North American AI data centres. EBANX reported a 138% year-on-year surge in processed digital payment volumes across eight Latin American countries.
- Sovereign credit and weather: Fitch said Latin American sovereign ratings have headroom to absorb a severe “Super El Niño”, but warned of growth slowdowns, particularly in Peru and Ecuador, and renewed inflation pressure in agriculture and hydroelectricity.
Europe
- Record highs: The STOXX 600 edged up 0.14% after touching a record 665.38 intraday, and Germany’s DAX gained 0.41% after breaking above 27,000 for the first time.
- Regional benchmarks: France’s CAC 40 rose 0.34%, Switzerland’s SMI 0.63% and London’s FTSE 100 0.26%.
- Earnings and rotation: Lower mega-cap tech exposure shielded Europe from the Nvidia sell-off. Siemens surged 3.8% on a raised outlook, Merck gained 1.6% on higher profit guidance and Burberry jumped 8%–9% on a return to first-half profitability; ASML (-2.6%) and Endeavour Mining (-8.4%) weighed.
- Macro and energy: UK Q3 GDP beat expectations at +0.7% quarter on quarter and Germany’s growth forecast was upgraded. European gas jumped over 3% to nearly €90/MWh on winter supply concerns and Strait of Hormuz disruption.
Asia
- Tech sell-off: Most Asian indices closed lower on the Nvidia crisis. Taiwan’s TAIEX dropped 2.6% and South Korea’s KOSPI fell 0.6% to 5,342.73.
- Regional closes: Japan’s Nikkei 225 fell 0.7% to 60,819.36 on tech losses and October producer inflation of +7.1% year on year. Hong Kong’s Hang Seng fell 1.3% to 24,008.55 and the Shanghai Composite dipped 0.7% to 3,655.83.
- India: The Nifty 50 closed marginally higher (+0.08% at 25,275.25) on foreign inflows and Brent near $92 a barrel.
- Currency pressure: Hawkish Fed expectations kept the dollar firm, pushing the yen toward the 160 intervention zone at around 159.65–159.70.
Key Market Snapshot
Figures as at · Levels for 12 November 2026, as reported in this brief
| Index | Level / move | Key driver |
|---|---|---|
| US S&P 500 | ~7,600 (-0.3% intraday) | Nvidia CEO exit; rising bond yields |
| US Dow Jones | ~52,450 (-0.1% intraday) | Blue-chip resilience vs tech drag |
| Canada S&P/TSX | ~36,245 (-0.4% intraday) | Gold sell-off and mining losses |
| Brazil Bovespa | ~172,060 (prior close) | High domestic rates; WEG expansion |
| Mexico S&P/BMV IPC | ~72,006 (prior close) | Infrastructure and nearshoring inflows |
| Pan-Europe STOXX 600 | +0.14% (record intraday high) | Strong Q3 corporate earnings; non-tech rotation |
| Germany DAX | +0.41% (topped 27,000 intraday) | Siemens profit boost; upgraded German GDP outlook |
| UK FTSE 100 | +0.26% | Burberry rally (+8%) offset by mining losses |
| Japan Nikkei 225 | 60,819.36 (-0.7%) | Tech pullback; 7.1% producer price jump |
| Hong Kong Hang Seng | 24,008.55 (-1.3%) | Broad risk-off mood and US rate pressure |
| Taiwan TAIEX | 43,091.87 (-2.6%) | Heavy Nvidia supply-chain exposure |
Commodities
Figures as at · Prices for 12 November 2026, as reported in this brief
Commodities split sharply: crude and softs rallied on Middle East tension and El Niño supply warnings, while precious and industrial metals sold off under a surging dollar.
Global commodities snapshot
| Commodity | Nov 12 price / level | Daily move | Key driver |
|---|---|---|---|
| Brent crude oil | ~$94.50 / bbl | +1.9% to +2.3% | US–Iran tensions and Strait of Hormuz risks |
| WTI crude oil | ~$87.69 – $88.19 / bbl | +1.4% to +2.0% | Geopolitical supply premium |
| COMEX gold | ~$3,860 – $3,880 / oz | -2.9% to -3.3% | Stronger USD and December Fed hike bets |
| COMEX copper | ~$6.16 – $6.21 / lb | -1.0% to -1.8% | Dollar strength and high inventory financing costs |
| Cocoa futures | $5,187 / ton | +2.8% | Ivory Coast El Niño 21%–25% crop loss warning |
| Arabica coffee | ~275 – 277 USc / lb | +3.1% to +4.0% | Broad softs rebound and weather risk |
| Chicago wheat | ~$5.84 / bu | -2.5% to -2.8% | Grain profit-taking and export competition |
Energy: crude surges on Strait of Hormuz rhetoric
- Crude rally: Oil climbed roughly 2% after US President Donald Trump said Washington does not need a deal with Iran. Brent rose to roughly $94.50–$94.62 a barrel and WTI to $87.69–$88.19.
- OPEC+ and gas: Argus Media noted OPEC+ producers led by Saudi Arabia and Iraq have surged output to offset Gulf transit risks. US natural gas rose 2.78% to $3.33/MMBtu and European gas neared €90/MWh.
Metals: gold drops below $4,000, copper at four-month lows
- Precious metals: Bets on a December Fed hike lifted the dollar and yields. COMEX gold fell nearly 3% to around $3,860–$3,880 a troy ounce, silver dropped over 3%–4% to roughly $49.73–$50.03, palladium fell 3.7%–5.7% and platinum 1.3%.
- Industrial metals: Copper slipped 1.0%–1.8% to roughly $6.16–$6.21 a pound, a four-month low. Aluminium eased 1.2% to $3,145.50 a ton and iron ore held flat at $92.15.
Agriculture: cocoa and coffee jump, grains pull back
- Softs: Cocoa jumped 2.8% to $5,187 a tonne after Ivory Coast’s weather agency warned a strong El Niño could cut 2026/27 output by 21%–25%. Arabica rose 3.1%–4.0% to roughly 275–277 US cents a pound, and rubber gained 3.2%.
- Grains and oilseeds: Chicago wheat fell roughly 2.5%–2.8% to $5.82–$5.84 a bushel, corn dipped 1.2% to $4.42 and soybeans edged to $12.19–$12.27. Canola rose 0.9%–1.1% to CAD 777.30 a tonne.
Africa
Figures as at · Market data for 12 November 2026, as reported in this brief
African markets saw contrasting momentum: a landmark retail IPO debut in Nairobi, a rebound in Lagos equities, and currency and yield pressure in Johannesburg on global inflation concerns.
African markets snapshot
| Exchange / benchmark | Highlight / move | Key driver |
|---|---|---|
| Kenya NSE (Quickmart IPO) | Debuted on the NSE | Oversubscribed KSh 18.41B retail offer |
| South Africa JSE All Share | ~112,895 – 113,359 (-0.1% to -0.5%) | Weaker rand, rising bond yields and global tech dip |
| Nigeria NGX | Rebounded higher | Renewed domestic buying interest |
| Egypt EGX 30 | 52,123.18 (-0.72%) | Profit-taking after ~24.6% YTD surge |
| Morocco CFG 25 / MASI | 17,429 (-0.01%) | Flat trading; low domestic inflation (0.5%) |
| Ghana GSE | 365% YTD trade surge | High retail volume led by MTN Ghana |
| Kenya Treasury bonds | KSh 50B reopened offer | 12.5%–12.86% coupons; CBK rate stress test |
| Afreximbank | $3B project pipeline | $2B facility for agro-processing and exports |
| USD / KES (Kenya) | 129.90 – 130.10 | Flat; anchored by CBK dollar sales |
| USD / NGN (Nigeria) | 1,355.88 (official) / 1,435 (street) | Official window firmer; parallel market softer |
| USD / ZAR (South Africa) | ~16.77 | Weaker on broad USD strength and Fed outlook |
| USD / GHS (Ghana) | 11.70 | Weaker on corporate and services dollar demand |
| USD / UGX (Uganda) | 4,105 – 4,115 | Stabilising on remittances and October rate hike |
| USD / ZMW (Zambia) | 20.74 | Gradual depreciation on hard-currency appetite |
| USD / EGP (Egypt) | ~53.44 | Steady amid domestic yield support |
East Africa: Quickmart debuts on the Nairobi bourse
- Landmark listing: Quickmart PLC began trading on the NSE after an oversubscribed IPO that drew KSh 18.41 billion in applications against a KSh 15 billion target, at an offer price of KSh 7.50 a share.
- First day: The debut rally lifted the retailer’s market valuation to KSh 35.6 billion, making it the 19th largest listed firm on the exchange.
- Institutional backing: Kenya’s second major IPO of 2026, after Kenya Pipeline Company in March, drew strong international demand: foreign investors subscribed nearly three times their allocation, with anchor backing from the IFC and UK-backed fund MOBILIST.
Southern and West Africa
- Johannesburg: The FTSE/JSE All-Share edged down roughly 0.1%–0.5%, between 112,895 and 113,359, as the rand weakened and government bond yields climbed. Economists flagged inflation risk from the softer rand, elevated Brent and higher-for-longer Fed rates.
- Lagos: The NGX rebounded on Thursday as domestic institutional and retail investors returned to bellwether stocks.
Continent-wide capital markets
- OECD listing study: African Capital Markets 2026 warned that high listing costs and low liquidity outside South Africa and Egypt keep pushing growing firms toward private equity, commercial debt or overseas exchanges such as London.
- Absa index: The 10th Absa Africa Financial Markets Index found 21 of 29 nations improved their market development scores in 2026, lifting the continental average to a decade high on FX resilience, digital platforms and green finance.
Regional forex
- Kenyan shilling: Flat against the dollar; commercial banks quoted 129.90 / 130.10 against 129.80 / 130.00 a week earlier, with CBK dollar sales absorbing import demand.
- Ugandan shilling: Quoted at 4,105 / 4,115 per dollar against last week’s 4,040 / 4,050, held within a 4,050–4,150 band by remittances and last month’s emergency rate hike.
- Nigerian naira: Strengthened ₦2.46 to ₦1,355.88 in the CBN window (near ₦1,348 on broader interbank quotes), while the parallel market slipped ₦15 to about ₦1,435.
- Ghanaian cedi: Weakened to 11.70 per dollar from 11.65 a week earlier on commerce and services demand; Absa Bank Ghana traders expect the pressure to persist.
- Rand, kwacha, pound and ZiG: The rand traded around 16.77 per dollar late Thursday; the kwacha softened to 20.74 from 20.62; the Egyptian pound held around 53.44; and the RBZ quoted the ZiG at 26.54.
Nairobi Securities Exchange
Figures as at · Nairobi Securities Exchange session data for 12 November 2026, as reported in this brief
Kenya’s stock market advanced across all major indices, powered by Quickmart’s debut and strong banking gains, while the shilling held at 129.96 per dollar.
Indices
- NSE All Share (NASI): Rose 0.40% to 241.55.
- NSE 20: Gained 0.34% to 4,174.67.
- NSE 25 and NSE 10: Advanced 0.51% to 6,798.63 and 0.70% to 2,668.91.
- Banking Sector Index: Led sectoral performance with a 0.82% jump to 282.65.
Movers
- Quickmart (QMRT): Made its trading debut against a KSh 7.50 IPO offer price, lifting its market capitalisation to KSh 35.60 billion.
- Co-operative Bank: Rallied on heavy volume after strong earnings and a 50% interim dividend increase.
- Volume and gainers: Absa Bank Kenya led trading volume. TRIFIC Green REIT, Unga Group and Family Bank were among the notable gainers.
- Laggards: The New Gold ETF fell with global bullion prices, and Car & General and Kapchorua Tea closed lower.
Kenya Forex
Figures as at · Central Bank of Kenya indicative rates, 12 November 2026, as reported in this brief
The shilling stayed tightly anchored against major currencies, supported by CBK liquidity management and balanced corporate flows.
| Currency pair | CBK indicative rate (Nov 12) | Commercial bank / market trend |
|---|---|---|
| USD / KES | 129.96 | Quoted at 129.90 – 130.10 by commercial banks; flat on the day |
| GBP / KES | 172.72 | Steady amid subdued sterling trading |
| EUR / KES | 144.38 | Stable with balanced importer demand |
Kenya Corporate News
Figures as at · As reported in this brief
Quickmart’s KSh 35.6 billion debut, Co-operative Bank’s third-quarter profit growth and Kenya Pipeline’s capital spending plans anchored the corporate news.
Corporate highlights snapshot
| Company / entity | Key development | Headline figure |
|---|---|---|
| Quickmart PLC | Listed on the NSE | KSh 35.6B market cap |
| Co-operative Bank | Nine-month earnings and interim dividend hike | KSh 27B profit (+50% dividend) |
| Kenya Pipeline (KPC) | Unveiled 3-year capital expenditure plan | KSh 100B ($770M) investment |
| Williamson Tea | Released half-year financial results | Swung to KSh 291M profit |
| Ecobank / Ketraco | High Court priority payment ruling | KSh 549M award payout |
Capital markets and retail deals
- Quickmart lists on the NSE: The supermarket chain began public trading against its KSh 7.50 IPO price. The rally generated KSh 5.6 billion in first-day paper gains and lifted the 72-store retailer’s valuation to KSh 35.6 billion, the bourse’s 19th largest listed firm.
- Adenia Partners partial exit: Adenia completed a partial exit through the oversubscribed KSh 15 billion offer for sale. Adenia and the founders keep a combined 50% via Sokoni Retail Kenya Limited, while anchor investors IFC, MOBILIST, 337 Frontier and RWC LLC hold 21.6%.
Banking and earnings
- Co-operative Bank: Raised its interim dividend 50% after KSh 27 billion profit for the nine months to 30 September 2026, and won a High Court ruling rejecting Nairobi City Hall’s bid to halt its KSh 692 million debt recovery.
- Williamson Tea and Kapchorua Tea: Released 2026/2027 half-year results; Williamson Tea swung back to profit with KSh 291 million in net earnings.
- Sanlam Allianz: Held a virtual extraordinary general meeting to advance shareholder approvals for its corporate restructuring.
Energy, infrastructure and legal rulings
- Kenya Pipeline expansion: Acting CFO Antony Ndegwa outlined plans to invest about KSh 100 billion ($770 million) over three years, largely debt-funded, to expand storage and transport while protecting the 50% dividend payout policy. Management noted early talks on synergies with Aliko Dangote’s Greenview International, which holds 24.99% of KPC and plans a coastal refinery.
- Ecobank v Ketraco: The High Court ordered Ketraco to pay KSh 549 million (€3.8 million plus KSh 1.5 million) directly to Ecobank Kenya from a KSh 10 billion arbitral award, ahead of claims from Instalaciones Inabensa SA and COX T&L SL.
- Private capital for state projects: Private investors lined up KSh 96 billion of funding commitments for upcoming state infrastructure projects.
Real Estate
Figures as at · As reported in this brief
Kenya real estate snapshot
| Segment / location | Key metric / price | Trend / driver |
|---|---|---|
| Buxton Point (Mombasa) | 492 units due Dec 2026 | Construction dispute with Mombasa County |
| Mlolongo land | KSh 46.6M / acre (-2.2% QoQ) | Largest Q3 land price drop among satellite towns |
| Kiambu / Rongai land | KSh 48.1M / KSh 29.6M per acre | Down 1.0% and 0.9% QoQ on slower speculative buying |
| Nairobi suburb houses | KSh 33.88M avg (+2.3% QoQ) | Strongest growth in 4 years; lower 14.4% loan rates |
| TRIFIC Green REIT (NSE) | — | Active trading amid CMA REIT reform push |
Affordable housing and project disputes
- Buxton Point standoff: GulfCap Real Estate pushed back against Mombasa County enforcement notices after the county halted construction at the Buxton Point affordable housing project. The county wants 10% of units (roughly 180 homes) and commercial space under the joint venture, plus full rent support for displaced residents. GulfCap says it remains on track to hand over 492 completed units in December 2026 and is working with the State Department for Housing on a Tenant Purchase Scheme.
- National housing pipeline: The National Housing Corporation reiterated its target of 110,000 more units by 2027, on top of over 50,000 delivered, through county partnerships, tenant purchase schemes and estate upgrades.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.96
Commercial banks 129.90 – 130.10
As at
Central Bank of Kenya indicative rateGBP / KES
172.72
As at
Central Bank of Kenya indicative rateEUR / KES
144.38
As at
Central Bank of Kenya indicative rate
Equities
NSE All-Share (NASI)
241.55
+0.40%
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,174.67
+0.34%
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,798.63
+0.51%
As at
Nairobi Securities Exchange, as reported in this briefNSE 10
2,668.91
+0.70%
As at
Nairobi Securities Exchange, as reported in this briefNSE Banking Index
282.65
+0.82%
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee, as published on this brief’s artwork
At a glance
- 1Quickmart began trading on the NSE after an IPO that drew KSh 18.41 billion against a KSh 15 billion target, valuing the 72-store retailer at KSh 35.6 billion — the bourse’s 19th largest listed firm.
- 2Nvidia fell 6%–9% after CEO Jensen Huang’s resignation and ouster, with CFO Colette Kress named interim CEO; Taiwan’s TAIEX dropped 2.6% while Europe, with less mega-cap tech exposure, hit record highs.
- 3Every NSE index rose: NASI +0.40% to 241.55, NSE 20 +0.34% to 4,174.67, NSE 10 +0.70% and the Banking Index +0.82%, led by Co-operative Bank after a 50% interim dividend increase.
Sources
- Serrari Group desk compilation, 13 November 2026; Markets Snapshot – 12 November 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data