
16 November 2026
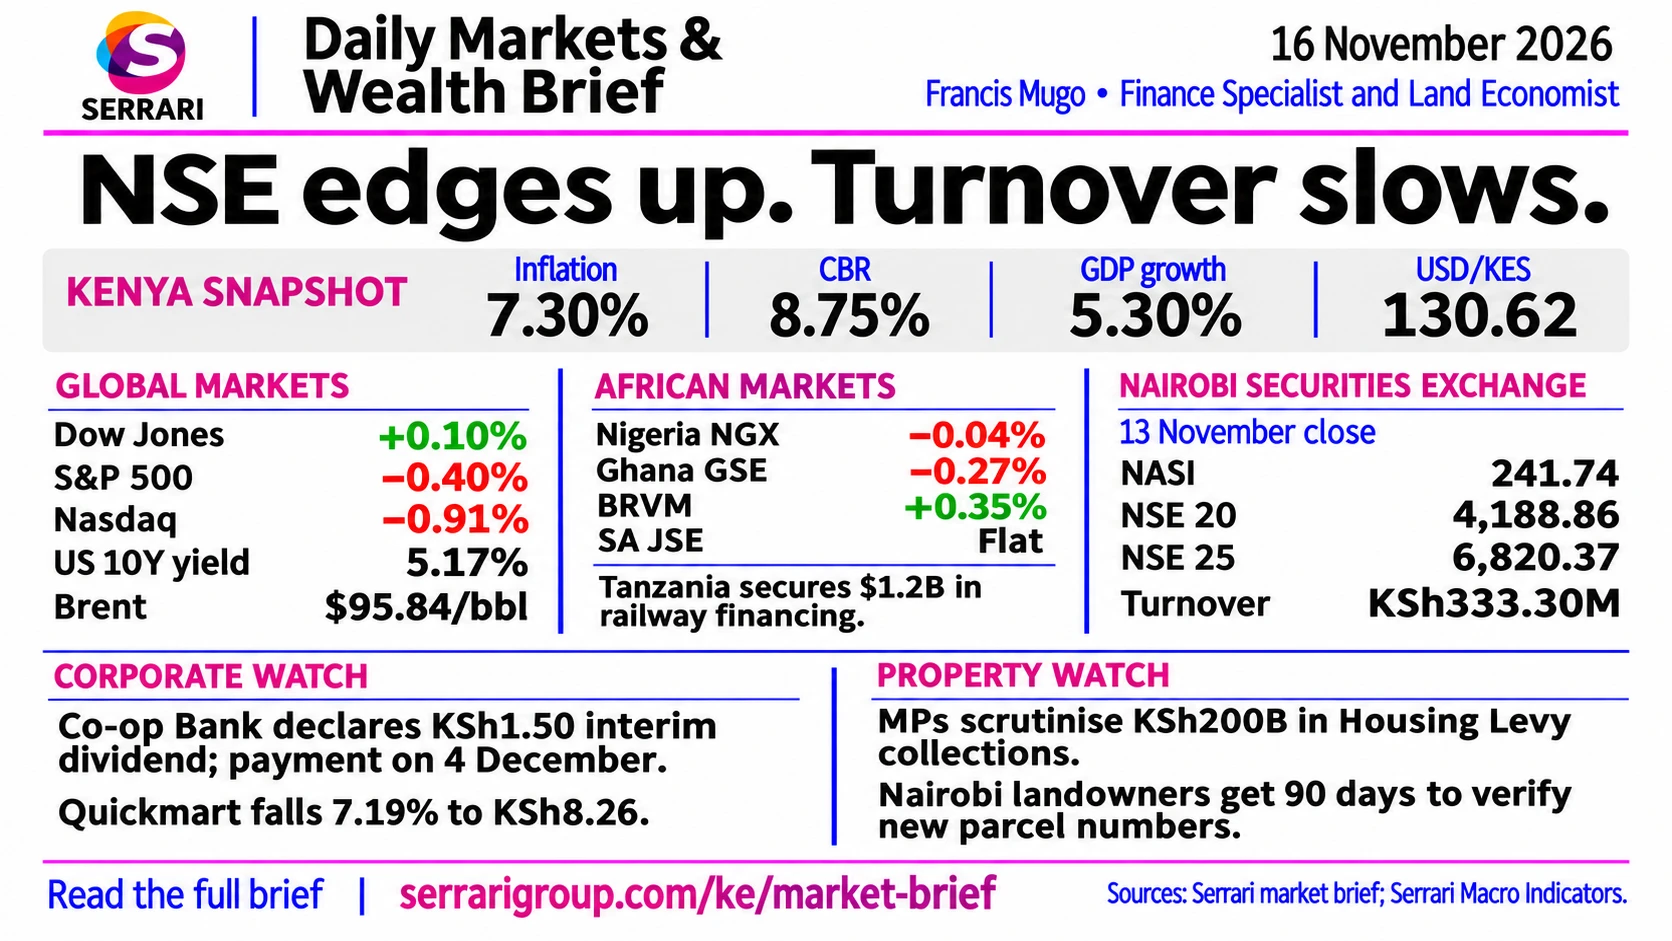
The NSE edged higher on Friday 13 November, with NASI up 0.08% to 241.74, as equity turnover fell 56.49% to KSh 333.30 million. Wall Street still logged its strongest week since August, and the Stoxx Europe 600 closed at an all-time high.
Global Markets
Figures as at · Market data for Friday 13 November 2026, as reported in this brief
Global forex — major currency pairs (close / spot)
| Pair | Rate | Daily / weekly trend | Key market driver |
|---|---|---|---|
| DXY (USD Index) | 103.41 | Up 0.23% on the day | Hotter US CPI earlier in the week and 10-year yields hitting 5.1% |
| EUR/USD | 1.1028 – 1.1050 | Down for 4th straight day | Wide Fed–ECB rate gap and eurozone growth concerns weigh on the euro |
| USD/JPY | 159.70 – 160.00 | Testing 160.00 resistance | Rising US yields push the pair toward Tokyo’s verbal intervention zone |
| GBP/USD | 1.3214 | Resilient near 1.32 | Upbeat UK Q3 GDP (1.7% annualised) and industrial output cushioned losses |
| USD/CHF | 0.8388 | Climbing toward 2026 highs | Broad dollar rally outweighs safe-haven franc demand |
| USD/CAD | 1.4270 | Firm / USD higher | US rate expectations outpace the Bank of Canada policy outlook |
| AUD/USD | 0.6772 – 0.6800 | Multi-month lows | Tech-sector volatility, softer energy prices and a strong USD weigh on the Aussie |
| NZD/USD | 0.5540 | Lower | Risk-off mood and a widening US yield advantage pressure the kiwi |
United States
- Major indexes: Despite late-week pullbacks, US markets notched their strongest weekly performance since August. The Dow Jones Industrial Average closed Friday at 52,347.55 (+0.1% on the day, +2.1% for the week), the S&P 500 at 7,561.67 (-0.4%, +2.5% for the week) and the Nasdaq Composite at 25,136.27 (-0.91%, +2.3% for the week).
- The Nvidia turmoil: Sentiment was heavily affected by the sudden departure of Nvidia CEO Jensen Huang following revelations of a personal affair, which dropped Nvidia’s market capitalisation below $4 trillion and pressured semiconductor and AI-related shares.
- Wholesale and consumer inflation: October’s Producer Price Index rose 0.3% month on month (slightly below the 0.4% consensus) but 6.5% year on year, the largest annual advance since November 2022. It followed a hotter-than-expected CPI report showing a 0.4% monthly rise.
- Interest rate expectations: Sticky inflation and a strong October jobs report raised near-certainty expectations that the Federal Reserve may consider another rate hike at its December meeting.
- US dollar (DXY): The US Dollar Index strengthened significantly over the week, rising to 103.17 from 101.57.
- Treasury yields: Bond markets sold off further, pushing the 10-year Treasury yield up to 5.17% as investors re-priced risk amid persistent inflation and high government debt.
Europe
- Stoxx Europe 600: Closed a historic week at an all-time high, finishing the session with a marginal gain and rallying 2.4% for the week — its strongest weekly advance since July — on a rotation away from US tech-heavy volatility.
- FTSE 100 (UK): Reached an intraday record high before closing up around 0.23% to 0.36%, near 10,902–10,910 points.
- DAX and CAC 40: Germany’s DAX recovered from early losses to close up roughly 0.07% to 0.2% (near 26,749 points, total return value). France’s CAC 40 ended about 0.09% higher, near 8,368, even as luxury-goods names weighed.
- Nvidia and AI fallout: European markets initially dipped on global tech jitters after Jensen Huang’s abrupt resignation, though Europe’s lower direct exposure helped it outperform Wall Street.
- Corporate movers: Swiss luxury group Richemont tumbled between 6.8% and 9% (closing down around 3.8%–7%) after first-half jewellery sales missed expectations. Wise Group jumped nearly 9.8% after a settlement agreement with Belgian prosecutors over alleged money laundering, without admitting wrongdoing.
- Macro and outlook: The euro area posted a €10.3 billion trade deficit as imports jumped 16.1%, while third-quarter GDP expanded 0.4% with employment steady. Goldman Sachs raised its 12-month STOXX 600 target to 700 (from 695), projecting earnings growth slowing to roughly 7% in 2027.
Asia
- South Korea: The Kospi led regional gains, surging 2.79% (the Kosdaq rose 2.43%) on a partial intraday recovery in tech sentiment.
- Japan: The Nikkei 225 advanced between 1.06% and 1.62% and the Topix added 0.25%, recovering from early-week tech headwinds.
- China and Hong Kong: The Shanghai Composite edged up 0.21%. The Hang Seng slipped about 0.57% to 1.55% across sessions, dragged by tech weakness (Alibaba fell 6.8%) amid reports of US restrictions on Chinese access to AI semiconductors.
- Australia and India: Australia’s S&P/ASX 200 eased 0.73%. India’s Sensex (down 289 points) and Nifty slipped on inflation and financial-sector drags.
- Drivers: Markets reacted to the Nvidia leadership change, with CFO Colette Kress stepping in as interim CEO. Brent hovered near $95.82 a barrel after swings on geopolitical comments about Iran, and China reported a jump in its third-quarter current account surplus to $276.1 billion.
Commodities
Figures as at · Prices for 13 November 2026, as reported in this brief
Key commodity prices, 13 November 2026
| Sector | Commodity | Price / settlement | Daily change | Key market driver |
|---|---|---|---|---|
| Energy | WTI crude oil | $88.56 / bbl | -0.26% | Unexpected US inventory build (+4.7M bbls) offset Gulf supply risks |
| Energy | Brent crude oil | $95.84 / bbl | -0.05% | Continued US blockade on Iran and Strait of Hormuz tanker tensions |
| Energy | Natural gas | $3.23 / MMBtu | -3.32% | Extended weekly slide amid mild demand forecasts |
| Precious metals | Gold | $3,886.30 / oz | +0.08% | Stabilised near one-year lows after a sharp weekly drop on Fed rate-hike bets |
| Precious metals | Silver | $49.12 / oz | -1.77% | Pressured by a stronger US dollar and softer solar-panel demand |
| Industrial metals | Copper | $6.09 / lb ($13,371.50/t) | -1.66% | Hit a near four-month low amid an AI-sector equity sell-off |
| Industrial metals | Aluminium | $3,011.00 / ton | -0.60% | Slipped on broader industrial weakness despite tight LME spot spreads |
| Agriculture | Chicago wheat | 609.75 ¢/bu (Mar ’27) | +1.75% | Rebounded off 4½-month lows on ongoing Black Sea export disruptions |
Energy holds near multi-month highs despite a weekly pullback
- Crude benchmarks traded nearly flat on Friday but logged a second consecutive weekly decline. Reports of tanker strikes in the Strait of Hormuz and Houthi attacks on Saudi infrastructure kept geopolitical risk premiums elevated, but gains were capped by a surprise 4.7 million-barrel jump in US commercial crude stockpiles and an International Energy Agency forecast of a fourth-quarter global supply surplus.
Precious metals stabilise after a weekly rout
- Gold hovered just below $3,900 after falling more than 4% over the prior five sessions to a one-year low. A stronger dollar and rising Treasury yields weighed on bullion as markets priced in a December Fed hike after sticky wholesale inflation (PPI up 6.5% year on year). Silver underperformed, sliding below $50 an ounce.
Industrial metals slide on tech volatility
- Copper posted its steepest weekly decline since March, touching its lowest price since July. Goldman Sachs analysts said a broad sell-off in AI and data-centre equities triggered heavy fund liquidation, overshadowing tight physical inventories in China.
Grains rebound from multi-month lows
- Agricultural futures broadly climbed on Friday, led by wheat and soybeans. Wheat bounced off its lowest level since June as prolonged halts to Russian and Ukrainian Black Sea shipments offset large Southern Hemisphere harvests.
Africa
Figures as at · Market data for 13 November 2026, as reported in this brief
Africa’s financial markets and macroeconomic landscape show a transition toward growth ambitions tempered by persistent debt, inflation and external pressures.
Major African equities and indices, 13 November 2026
| Exchange / index | Closing value | Daily change | Key market highlights |
|---|---|---|---|
| Nigerian Exchange (NGX ASI) | 252,269.16 | -0.04% | Traded 3.70 billion shares worth ₦23.11 billion across 27,205 deals; banking and insurance gains such as First HoldCo (+1.76%) and UBA (+1.20%) cushioned the index |
| Johannesburg Stock Exchange (JSE ASI) | 112,894.87 | Flat | The JSE Top 40 closed at 104,486.62; Brait plc (-3.78%) saw selling pressure while Huge Group (+2.46%) gained |
| Ghana Stock Exchange (GSE-CI) | 13,961.97 | -0.27% | Investors digested the 2027 budget’s US$10 billion New Economy programme and early redemption of GH¢29 billion in domestic bonds |
| BRVM Composite (West Africa) | 518.96 | +0.35% | Outperformed regional peers on infrastructure momentum, including Côte d’Ivoire’s new 390MW gas plant |
| Egyptian Exchange (EGX 30) | 49,234.35 | Flat | Supported by easing October headline inflation (12.7%) and moderating core inflation |
Macroeconomic growth and forecasts
- IMF and World Bank: The IMF projects Sub-Saharan Africa’s real GDP growth at 4.5% for 2026 and 2027, while the World Bank Group estimates 4.3% in 2026 (up from 4.1% in 2025).
- Ghana: Unveiled a US$10 billion “New Economy” programme in its 2027 budget and announced the early redemption of GH¢29 billion in domestic bonds.
- Nigeria and Uganda: The World Bank upgraded Nigeria’s 2026 growth forecast to 4.3%; Uganda recorded 6.4% expansion in FY2025/26.
- Senegal and South Africa: Senegal’s growth is expected to slow to 1.5% in 2027 on heavy debt and energy costs; South African unemployment edged up to 33.7%.
Financial markets and index updates
- Tanzania: Rose to 9th place with an overall index score of 62, aided by money market reforms, strong bond subscription and the launch of its first exchange-traded funds.
- South African equities: Huge Group (HUG.JO) closed up 2.46% at 250.00 ZAc; Brait plc (BAT.JO) dropped 3.78% to 178.00 ZAc.
Key infrastructure and strategic deals
- Tanzania: Secured US$1.2 billion in railway financing.
- Côte d’Ivoire: Commissioned a new 390MW gas plant.
- Botswana: Announced plans to double its stake in De Beers.
- Algeria and Burkina Faso: Progressed regional trade and green finance, including Algeria’s Tindouf free trade zone and Burkina Faso’s carbon market legislation.
Nairobi Securities Exchange
Figures as at · Nairobi Securities Exchange session data for 13 November 2026, as reported in this brief
The equities market closed higher on 13 November 2026, though trading activity slowed sharply from the previous session.
Indices
- NSE All Share (NASI): Advanced 0.08% to 241.74.
- NSE 20: Rose 0.34% to 4,188.86.
- NSE 25: Gained 0.32% to 6,820.37.
- Banking Index: Added 0.50% to 284.07.
- Market capitalisation: Total market capitalisation stood at approximately KSh 4.09 trillion.
Trading activity
- Turnover: Equity turnover softened to KSh 333.30 million, down 56.49% from the previous session’s KSh 766.03 million, with share volumes down 34.19% to 18.79 million shares.
- Movers: ABSA Bank Kenya, Quickmart Supermarket and Co-op Bank Group led turnover. Uchumi Supermarket and Longhorn Publishers were the top gainers; Quickmart Supermarket and Shri Krishna Overseas were the top losers.
Money Market & Central Bank
Figures as at · As reported in this brief
- Liquidity and rates: The money market remained liquid through the week, with commercial banks’ excess reserves averaging KSh 31.5 billion above the 3.25% Cash Reserve Ratio requirement.
- KESONIA: The Kenya Shilling Overnight Interbank Average held steady at 8.75%, matching the Central Bank Rate of 8.75%. Interbank activity averaged 23 transactions worth KSh 13.4 billion.
- Treasury bills: The 12 November Treasury bill auction saw massive demand, receiving KSh 69.3 billion in bids against a KSh 28.0 billion advertised target (247.3% performance), with yields on the 91-day, 182-day and 364-day papers declining marginally.
Kenya Corporate News
Figures as at · As reported in this brief
Corporate and regulatory updates
- Co-operative Bank interim dividend: Co-operative Bank of Kenya announced an interim dividend of KSh 1.50 a share (books closure 25 November, payment on 4 December 2026), backed by strong nine-month earnings.
- Quickmart listing buzz: Quickmart’s recent NSE debut continued to draw heavy domestic and foreign institutional interest, recording strong foreign net inflows alongside KCB Group and Kenya Pipeline Co. (KPC).
- Microsoft outage hits Saccos: A global Microsoft cloud services outage disrupted email across Kenya, prompting deposit-taking Saccos and asset managers to switch swiftly to alternative channels with clients.
- Treasury and African Union financing: Treasury Cabinet Secretary John Mbadi reaffirmed Kenya’s backing for the Kigali Decision on Financing the Union, pushing for a 0.2% import levy across African Union member states to boost domestic resource mobilisation and reduce reliance on external development funding.
- Syokimau building collapse: An eight-storey building under construction collapsed in Syokimau, killing six people on the spot and injuring several others, prompting the Institution of Engineers of Kenya to call for a nationwide safety crackdown and independent structural investigations.
- IGAD and EAC digital integration: IGAD and the East African Community wrapped up a two-day joint communications officers’ workshop in Nairobi on the World Bank-financed Eastern Africa Regional Digital Integration Project (EARDIP), covering cross-border connectivity, e-payments, e-commerce and cybersecurity.
Real Estate
Figures as at · As reported in this brief
Kenya’s real estate sector centred on parliamentary scrutiny of KSh 200 billion in Housing Levy collections, major Nairobi land title conversions and heightened buyer protection alerts.
- KSh 200 billion Housing Levy scrutiny: Housing Principal Secretary Charles Hinga and Affordable Housing Board CEO Joe Mutugu appeared before the National Assembly’s Special Funds Accounts Committee on 13 November. MPs questioned fund management and value delivery after Auditor General findings that 269 affordable housing projects lacked land documentation for audit verification.
- Nairobi land reference number conversions: After a special Gazette notice issued on 12 November by Lands Cabinet Secretary Alice Wahome, landowners in Westlands, Karen, Lavington and Kileleshwa entered a 90-day window to verify new parcel numbers and object to updated cadastral maps.
- Off-plan investor protection alerts: Parliament continued addressing warnings about stalled private developments; lawmakers sought formal committee statements after more than 100 buyers in a Lavington off-plan project faced losses from developer loan defaults and bank auctions.
- Kitengela landlord–tenant dispute: Residents of Noonkopir Estate, Kitengela, protested on 13 November after a fatal altercation between a house agent and a tenant over KSh 1,500 in unpaid rent.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
130.62
As at
As published on this brief’s artwork
Equities
NSE All-Share (NASI)
241.74
+0.08%
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,188.86
+0.34%
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,820.37
+0.32%
As at
Nairobi Securities Exchange, as reported in this briefNSE Banking Index
284.07
+0.50%
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee, as reported in this briefKESONIA (overnight interbank)
8.75%
As at
Central Bank of Kenya, as reported in this brief
At a glance
- 1US stocks notched their strongest week since August (Dow +2.1%, S&P 500 +2.5%, Nasdaq +2.3%) despite a mixed Friday, as October wholesale inflation of 6.5% year on year pushed the 10-year Treasury yield to 5.17% and lifted bets on a December Fed hike.
- 2Every NSE index closed higher on 13 November: NASI +0.08% to 241.74, NSE 20 +0.34% to 4,188.86, NSE 25 +0.32% to 6,820.37 and the Banking Index +0.50% to 284.07, while turnover fell 56.49% to KSh 333.30 million.
- 3Co-operative Bank declared a KSh 1.50 interim dividend (books close 25 November, payment 4 December), and the 12 November Treasury bill auction drew KSh 69.3 billion against a KSh 28.0 billion target.
Sources
- Serrari Group desk compilation, 16 November 2026; Markets Snapshot – 13 November 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data