
17 November 2026
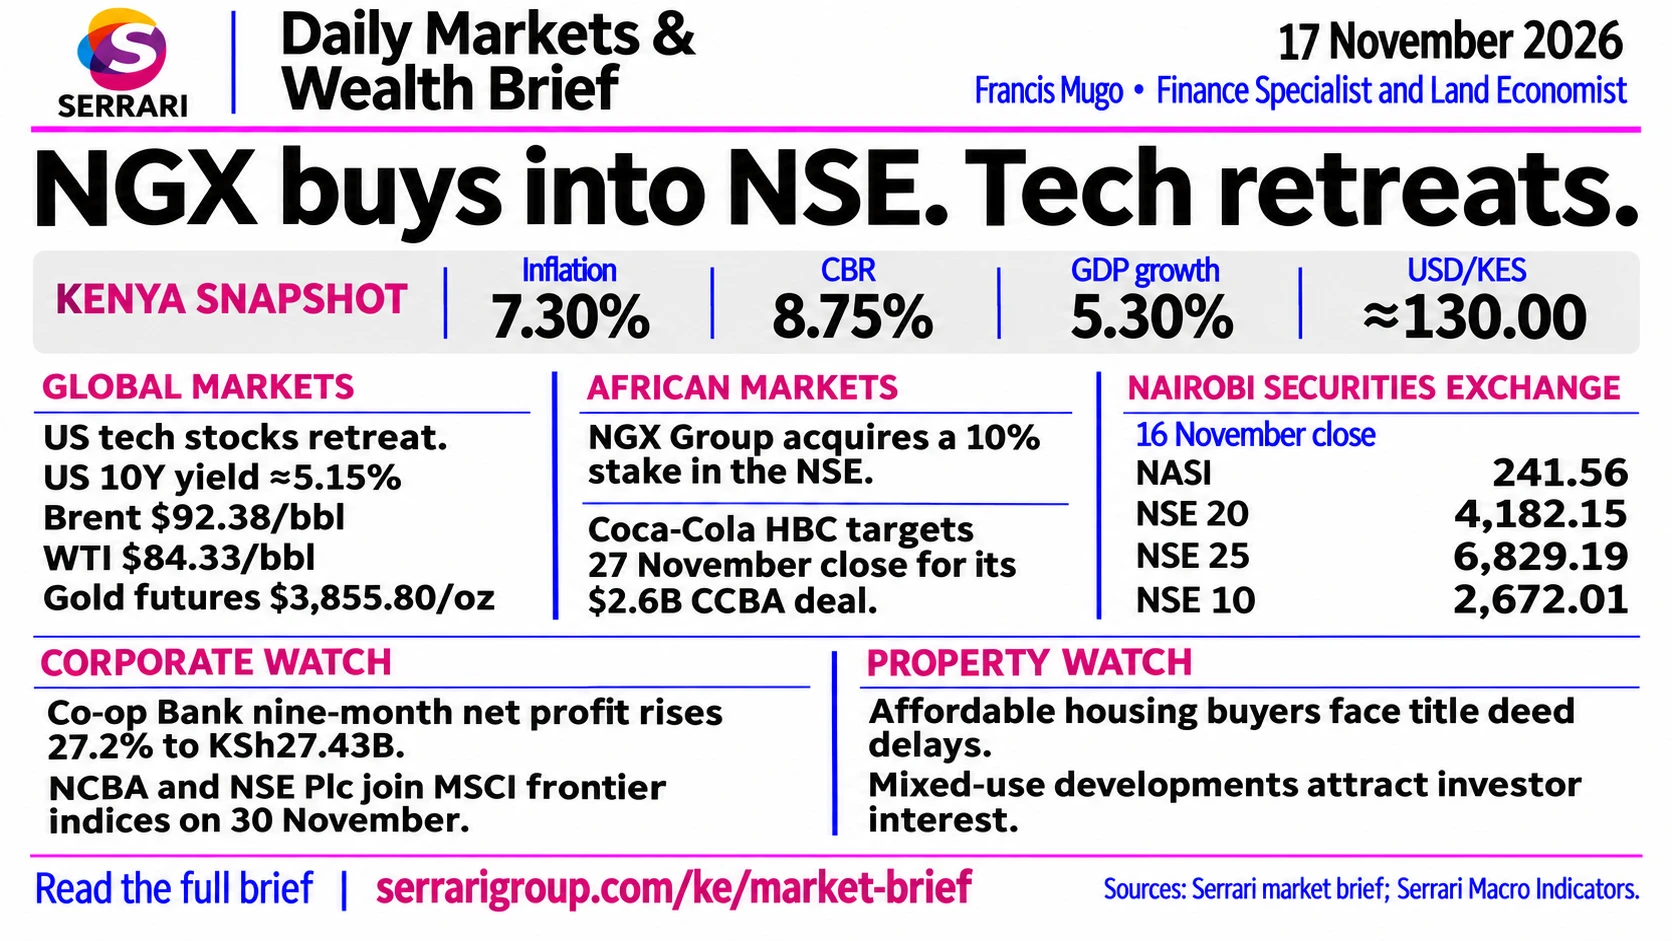
Nigerian Exchange Group bought a 10% stake in the Nairobi Securities Exchange, while NCBA and NSE Plc were added to MSCI frontier indices from 30 November. Globally, a steep tech sell-off hit Wall Street and Asia as the 10-year Treasury yield hovered around 5.15%.
Global Markets
Figures as at · Market data for Monday 16 November 2026, as reported in this brief
Global markets had a pronounced risk-off session, driven by a steep sell-off in technology stocks and persistent inflation pressures. Major indices retreated across the US and Asia as investors braced for pivotal AI catalysts and tighter monetary policy, while European indices held steady.
United States
- Major indices: The Nasdaq Composite tumbled about 1.3% to 2.4% (closing near 24,799) as technology and AI stocks faced heavy pressure. The S&P 500 dropped roughly 1% to 1.9% (near 7,487) and the Dow fell around 520 to 726 points (roughly 0.6% to 1.4%).
- Nvidia and the AI leadership crisis: Nvidia fell over 4% on continuing fallout from Jensen Huang’s abrupt resignation. Reports of a board decision not to bring him back, and new Commerce Department moves closing loopholes for Chinese firms renting offshore computing power, rattled confidence ahead of Nvidia’s quarterly earnings.
- Broader chip slump: The sell-off spread across semiconductors and AI infrastructure, hitting Intel, AMD, Micron, Broadcom and Marvell.
- Treasury yields: The 10-year yield hovered around 5.15% after hotter-than-expected October inflation (CPI up 0.4%), keeping pressure on equity valuations and cementing expectations for Federal Reserve rate decisions.
- Crypto, gold and bright spots: Bitcoin pulled back toward multi-month lows, dragging crypto-linked equities such as Strategy (formerly MicroStrategy), while gold traded slightly lower near $3,850/oz. Tyson Foods rose more than 7% on strong fiscal 2027 guidance.
Europe
- STOXX Europe 600: Edged up roughly 0.09% to 664.76 in early trading, supported by lower regional exposure to tech and semiconductors.
- Morgan Stanley upgrade: Morgan Stanley upgraded European equities to overweight, positioning the region as an alternative to tech-heavy markets.
- Macro headwinds: Eurozone industrial production for September contracted 1.5% year on year (against an expected −0.2%), complicating the ECB’s policy path.
- Currencies and rates: The euro slipped below $1.10 for the first time since April 2025 on expectations of US rate hikes. The ECB noted that third-party provider failures pose a bigger risk to eurozone banks than fraud.
- National indices: Germany’s DAX slipped about 0.4%, Italy’s FTSE MIB fell about 0.5%, France’s CAC 40 was flat and the UK’s FTSE 100 gained about 0.2%.
Asia
- Semiconductor slump: Asian tech and chipmaker benchmarks took heavy losses after US tech pressure and uncertainty around Nvidia’s leadership change. Taiwan’s TAIEX plunged about 6% (its worst drop since July), South Korea’s KOSPI fell about 3.6% and Japan’s Nikkei 225 about 2.4%.
- China data: October retail sales rose just 0.4% year on year (forecast 0.8%), industrial production grew 4.8% (forecast 5.3%) and fixed-asset investment dropped 8.1% year to date.
- Japan GDP: Third-quarter GDP slowed to 0.0% quarter on quarter, missing expectations of 0.1% and signalling weaker private consumption.
- Trade and policy: China said the upgraded China-ASEAN Free Trade Area (ACFTA 3.0) takes effect on 1 December 2026, and South Korea proposed new AI and cultural cooperation initiatives at the Korea-ASEAN Summit.
Global forex
- Dollar Index (DXY): The dollar traded firm, near 103.41 at fresh multi-month highs, backed by annual US PPI climbing to 6.5% and rising Treasury yields that solidified expectations of a December Fed hike.
- EUR/USD and GBP/USD: The euro slipped back toward 1.1030 (trading near 1.1018) on hawkish Fed expectations and euro-area production figures; sterling pulled back toward 1.3200 ahead of UK labour and inflation data.
- USD/JPY: The pair continued to test the ¥160 threshold, keeping markets alert to potential Japanese intervention.
- Commodity currencies and gold: The Australian dollar tumbled near 0.6770 and the New Zealand dollar fell to 0.5530. Gold (XAU/USD) traded around $3,880–$3,887 an ounce as higher yields and Fed tightening bets capped upside.
- Catalysts to watch: Commentary from Fed officials (including Kevin Warsh), the Fed’s October meeting minutes, UK labour market statistics, US retail sales and Canadian CPI.
Commodities
Figures as at · Prices for 16 November 2026, as reported in this brief
Commodities pulled back broadly on a stronger dollar, expectations of a December Fed hike and signs of improving oil supply. Energy and metals declined across the board, while agriculture was mixed.
Commodity prices, 16 November 2026
| Commodity | Price | Daily change |
|---|---|---|
| WTI crude oil | $84.33 / bbl | -3.39% |
| Brent crude oil | $92.38 / bbl | -3.61% |
| Natural gas (Henry Hub) | $3.118 / MMBtu | -3.47% |
| Gold (COMEX futures) | $3,855.80 / oz | -0.78% |
| Silver | $46.91 / oz | -4.50% |
| Copper (COMEX) | $5.992 / lb | -1.62% |
| Wheat (CBOT) | $5.87¼ / bu | ~-1.0% |
| Corn | $4.48 / bu | +0.59% |
| Soybeans | $12.27¼ / bu | -0.35% |
| Arabica coffee | 277.30 ¢ / lb | +1.39% |
Energy
- Crude and gas: WTI front-month contracts dropped 3.39% to $84.33 a barrel and Brent fell 3.61% to $92.38. Henry Hub natural gas declined 3.47% to $3.118 per MMBtu.
- Drivers: According to Bloomberg, surging Saudi output and International Energy Agency projections of a 2 million barrel-per-day surplus outweighed reports of vessels striking mines in the Strait of Hormuz.
Precious and industrial metals
- Gold and silver: With the dollar at fresh 19-month highs after hot US inflation data, COMEX gold futures slipped 0.78% to $3,855.80 an ounce, their lowest in over a year, and silver tumbled 4.50% to $46.91.
- Copper: COMEX copper declined 1.62% to $5.992 a pound, and LME three-month copper fell to a four-month low amid tech and AI pullbacks.
- Drivers: Analysts on MINING.COM said elevated producer prices solidified bets on a quarter-point December Fed hike, lifting yields and weighing on bullion.
Agriculture
- Grains: CBOT wheat fell roughly 1.0% to $5.87¼ a bushel on weak US weekly export sales and optimism about Russia–Ukraine peace talks. Corn edged up 0.59% to $4.48 on strong export demand from Mexico and Colombia, and soybeans slipped 0.35% to $12.27¼.
- Coffee: Arabica futures gained 1.39% to 277.30 cents a pound, supported by historically low certified warehouse inventories.
- Positioning: Successful Farming reported that money managers significantly trimmed bullish net long positions in corn and soybeans ahead of Monday’s session.
Africa
Figures as at · As reported in this brief
African markets were highlighted by major cross-border capital market integration, key index additions, corporate M&A milestones and pressure on regional currencies from a stronger dollar.
Capital markets and equities
- NGX acquires 10% of the Nairobi bourse: The Nigerian Exchange Group announced the acquisition of a 10% equity stake in the Nairobi Securities Exchange. Following NGX’s 2024 investment in the Ethiopian Securities Exchange, the deal establishes direct cross-ownership between West and East Africa’s leading capital markets.
- MSCI index additions: After MSCI’s November 2026 review, NCBA Kenya joins the MSCI Frontier Markets Index alongside Absa Kenya and Safaricom, and the Nairobi Securities Exchange Plc joins the MSCI Frontier Markets Small Cap Index, effective 30 November 2026.
- Coca-Cola bottling takeover nears close: Coca-Cola HBC expects to complete its $2.6 billion acquisition of a 75% controlling stake in Coca-Cola Beverages Africa (CCBA) on 27 November. Its secondary listing on the Johannesburg Stock Exchange is scheduled to take effect on 23 November.
Currencies and monetary policy
- South African rand: Weakened toward R17.00 per dollar, trading around R16.94–R16.99, on broad dollar strength ahead of anticipated Fed moves and local political uncertainty over metro coalition stability.
- East African currencies: The Kenyan shilling held near KES 129.96 per dollar, supported by central bank FX reforms and reserves of $14.61 billion (5.9 months of import cover). The Bank of Tanzania set its indicative mean at TZS 2,646.78 and the Bank of Uganda opened at UGX 4,123.57 / 4,133.57.
- West Africa: The naira traded around ₦1,345 per dollar. Ghana’s cedi hovered near GH¢11.70–GH¢11.72 on the interbank market ahead of the Bank of Ghana’s 18 November rate decision, after October inflation rose to 5.5%.
Macroeconomics and trade
- Agricultural integration: At the Third Global Parliamentary Summit Against Hunger and Malnutrition in Nairobi, President William Ruto urged African lawmakers to dismantle intra-African trade barriers and commit domestic budgets to the 10-year Kampala Declaration food security roadmap.
- Regional sugar deficit: EAC sugar producers called for deeper regional cooperation and strategic reserves to close a 1.2 million-tonne supply gap. Separate analyses highlighted continuing supply-chain and freight cost pressures across East and Southern Africa from maritime disruption in the Strait of Hormuz earlier in the year.
Nairobi Securities Exchange
Figures as at · Nairobi Securities Exchange session data for 16 November 2026, as reported in this brief
Kenyan markets were highlighted by the Nigerian Exchange Group’s 10% stake in the NSE, a steady shilling near KES 130 per dollar and strong momentum heading into a busy banking earnings week.
NSE benchmark indices, 16 November 2026
| Index | Ticker | Close | Daily change |
|---|---|---|---|
| NSE All-Share Index (NASI) | ^NASI | 241.56 | -0.07% |
| NSE 20-Share Index | ^N20I | 4,182.15 | -0.16% |
| NSE 25-Share Index | ^N25I | 6,829.19 | +0.13% |
| NSE 10-Share Index | ^N10I | 2,672.01 | +0.08% |
| NSE Banking Sector Index | ^NBSI | 284.66 | +0.21% |
| NSE Bonds Index | ^NBDI | 1,169.37 | -0.30% |
Session highlights
- Sector divergence: The NSE Banking Sector Index led the market with a 0.21% gain to 284.66, keeping the NSE 25 and NSE 10 in positive territory.
- Movers: Longhorn Publishers, Standard Group and WPP Scangroup led Monday’s gainers. Quickmart (QMRT) retreated after last week’s debut surge, alongside East African Portland Cement and Olympia Capital.
- Derivatives: The NSE Derivatives Market (NEXT) marked the December 2026 NSE 25 Index Futures contract at 6,852, up 7 points from the previous session.
Equities and capital markets
- NGX Group acquires 10% NSE stake: Nigerian Exchange Group Plc announced the acquisition of a 10% stake in the Nairobi Securities Exchange Plc to deepen West and East African market integration. The purchase price was not disclosed, but the stake matches a 26.31 million-share block trade executed in late October, valuing the holding at approximately KES 900 million.
- MSCI inclusions: NCBA Group and NSE Plc were selected for the MSCI Frontier Markets Index and the MSCI Frontier Markets Small Cap Index respectively. Both changes take effect after the market close on 30 November 2026, while KenGen exits the Small Cap Index.
- Market valuation: Total NSE equity market capitalisation recently surpassed KES 4.08 trillion. Co-operative Bank led gainers after a 27.2% jump in nine-month net profit to KES 27.43 billion, and Quickmart recently made a strong trading debut.
Kenya Economy, Currency & Fixed Income
Figures as at · As reported in this brief
Currency, monetary policy and fixed income
- Shilling stability: The shilling held steady around KES 129.97 to KES 130.05 per dollar, despite a 1.9% year-on-year dip in October diaspora remittances to USD 430.5 million and a USD 94 million weekly decline in usable reserves to USD 14.61 billion (5.9 months of import cover).
- Rates and Treasury bills: The CBK held the Central Bank Rate at 8.75%, with the 91-day Treasury bill yield at 8.745%. Falling rates have fuelled record fixed-income activity, pushing year-to-date NSE bond turnover past KES 2.90 trillion.
- Crypto regulation: The CBK and Capital Markets Authority highlighted the operationalisation of the Virtual Asset Service Providers (VASP) Regulations, 2026; all existing and prospective crypto and virtual asset businesses must apply for formal licences.
Macroeconomic and fiscal developments
- Fuel prices unchanged: EPRA retained pump prices for the 15 November to 14 December 2026 cycle, using KES 4.6 billion in stabilisation funds to cushion consumers against rising global petroleum costs.
- Budget and debt submissions: The National Assembly invited public submissions on the 2027 Budget Policy Statement and the Medium-Term Debt Management Strategy for FY 2027/28–2029/30.
- FATF grey list target: The National Treasury aims to exit the FATF grey list by April 2027, having completed 19 of 21 action items; remaining work focuses on ultimate beneficial ownership disclosure.
- State agency debt: A new report found state agencies owe a combined KSh 880.75 billion, weighed down by entities such as Kenya Railways and Kenya Airways.
Kenya Corporate News
Figures as at · As reported in this brief
Corporate earnings and banking
- Co-op Bank nine-month profit: Co-op Bank reported a 27.2% rise in nine-month net profit to KSh 27.43 billion, supported by stronger lending and a drop in its non-performing loan ratio from 17.1% to 12.9%.
- SME financing: A reported KSh 424.67 billion has been directed into Kenya’s SME sector, led by Equity Bank (KSh 127.9 billion), Co-op Bank (KSh 66.2 billion) and NCBA (KSh 31.8 billion).
- Tea sector recovery: Williamson Tea and Kapchorua Tea posted significant earnings recoveries for the first half of FY 2027, though weather and global market risks persist.
- Banking earnings week: Equity Group and Family Bank report Q3 2026 results on 17 November, followed by Absa Bank Kenya, KCB Group and Diamond Trust Bank on 18 November, and Stanbic Bank and Standard Chartered Bank Kenya on 19 November.
Infrastructure
- NSSF road investment: The National Assembly’s Social Protection Committee endorsed the NSSF’s investment in the KSh 176 billion Rironi–Mau Summit highway after inspecting the 81-kilometre Rironi–Gilgil section.
- LAPSSET corridor framework: CVI Kenya entered a cooperation framework with the LAPSSET Corridor Development Authority, the University of Nairobi and Panache Technohub to develop 27 million hectares along the corridor across Lamu, Tana River, Garissa, Isiolo, Samburu, Marsabit and Turkana counties.
- Roads levy ruling: The Milimani Law Courts dismissed a petition by county governments seeking direct funding from the Sh10.5 billion roads levy.
Real Estate
Figures as at · As reported in this brief
Kenya’s real estate sector is navigating title processing hurdles in public housing, rising investor focus on integrated urban developments and a sharp split between Nairobi’s prime suburbs and satellite towns.
Market highlights
- Affordable housing title deed bottlenecks: Buyers of completed units under the Affordable Housing Programme face administrative delays in obtaining individual title deeds; a Daily Nation report highlights legal and structural challenges complicating ownership transfers.
- Integrated developments draw capital: Mixed-use and master-planned projects are attracting heightened investor appetite. K24 coverage notes developers are prioritising self-contained ecosystems combining residential, retail and commercial space to hedge against single-sector slowdowns.
- Alternative building tech recognised: Thika-based Interlocking Blocks Housing Limited won dual honours at the Starbrands East Africa Awards 2026, underscoring growing adoption of cost-saving construction technologies.
Policy, regulation and outlook
- Off-plan buyer protections: After disputes affecting over 100 buyers at a Lavington apartment project, lawmakers petitioned Parliament’s Housing Committee for stricter safeguards; as reported by People Daily, the push aims to curb misuse of purchaser deposits in stalled off-plan developments.
- Cost and rate pressures: With the Central Bank Rate held at 8.75% and commercial lending averaging roughly 14.4%, HouseTuHome warns that rising construction material prices and elevated global oil costs pose fresh Q4 margin risks for builders.
- Stamp duty relief proposal: The National Treasury is advancing proposals to exempt land transactions of KES 1 million or less from stamp duty while introducing progressive rates for higher-value transfers.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
130.00
Traded 129.97 – 130.05
As at
As published on this brief’s artwork (≈130.00)
Equities
NSE All-Share (NASI)
241.56
-0.07%
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,182.15
-0.16%
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,829.19
+0.13%
As at
Nairobi Securities Exchange, as reported in this briefNSE 10
2,672.01
+0.08%
As at
Nairobi Securities Exchange, as reported in this briefNSE Banking Index
284.66
+0.21%
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
As at
Central Bank of Kenya — Monetary Policy Committee, as reported in this brief91-day T-bill
8.745%
At a glance
- 1Nigerian Exchange Group acquired a 10% stake in the Nairobi Securities Exchange, matching a 26.31 million-share block traded in late October and valued at about KES 900 million — direct cross-ownership between West and East Africa’s leading bourses.
- 2A steep tech and AI sell-off hit Wall Street (Nasdaq down about 1.3%–2.4%) and Asia (TAIEX −6%, KOSPI −3.6%) as Nvidia fell over 4%, while Europe held steady and the 10-year Treasury yield hovered around 5.15%.
- 3NSE indices were mixed: NASI −0.07% to 241.56 and NSE 20 −0.16%, while banks lifted the NSE 25 (+0.13%) and NSE 10 (+0.08%); NCBA and NSE Plc join MSCI frontier indices after the 30 November close.
Sources
- Serrari Group desk compilation, 17 November 2026; Markets Snapshot – 16 November 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data