
1 October 2026
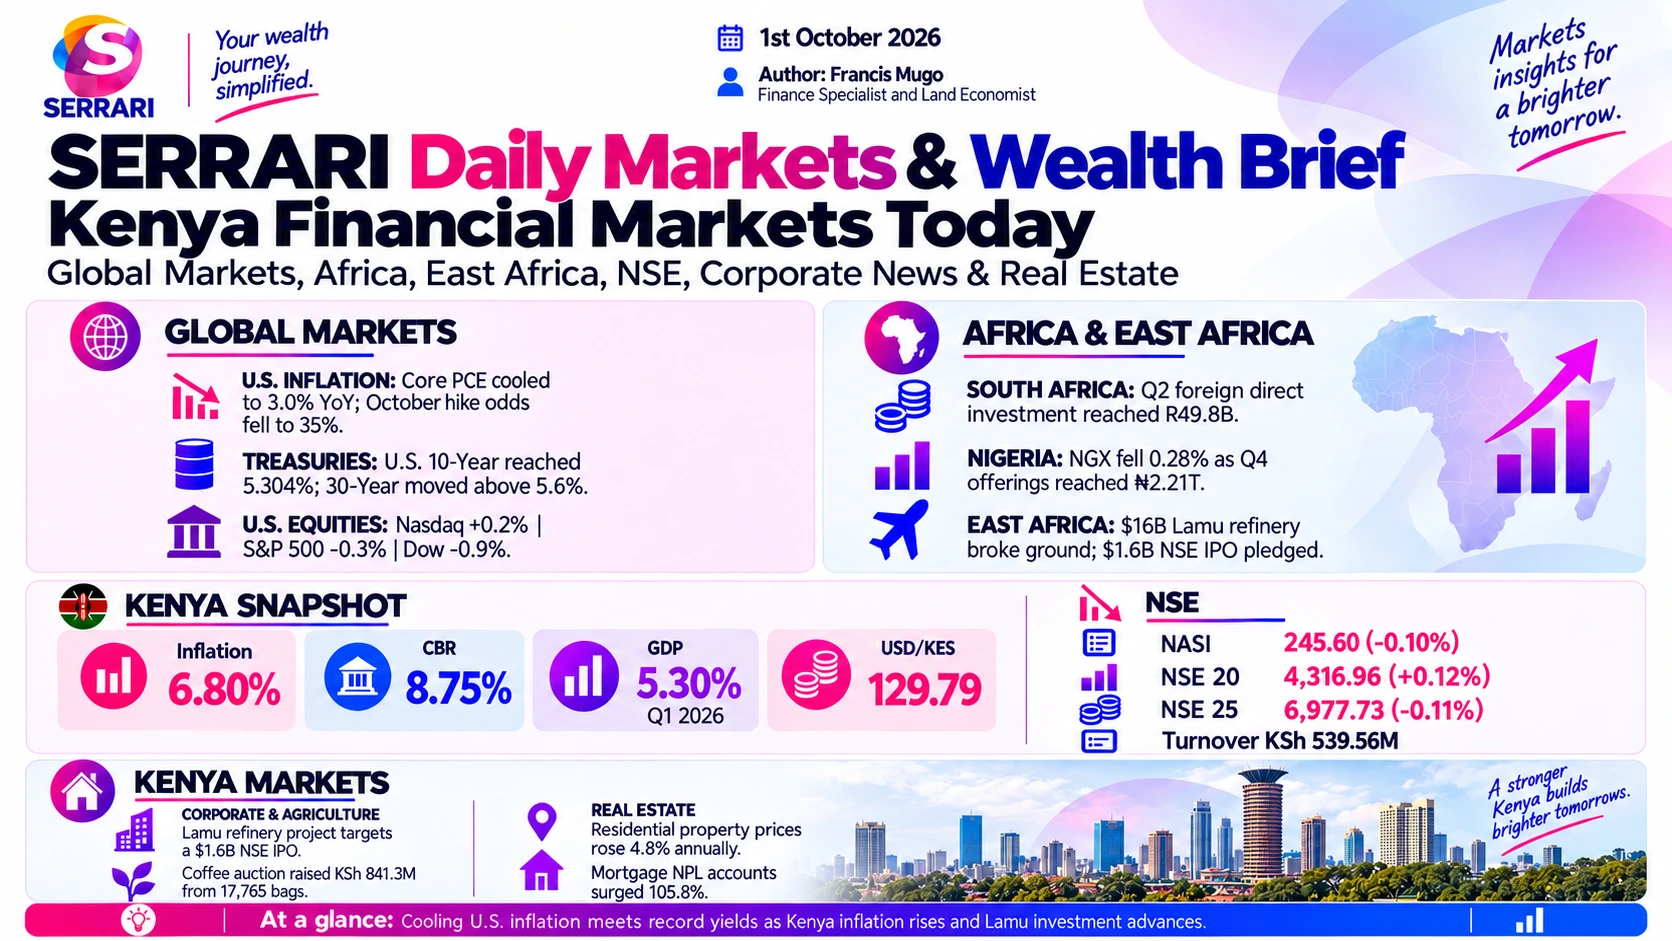
Core PCE cooled to 3.0% and cut October hike odds to 35%, yet the 10-year still closed at 5.304%, its highest since 2002. Kenyan inflation hit a 32-month high of 6.8% as Dangote broke ground on the $16 billion Lamu refinery.

Global Markets
Figures as at · Closing levels for Wednesday 30 September 2026, as reported in this brief
Markets closed a volatile third quarter under three catalysts: cooling US inflation data, surging multi-decade bond yields, and historic regional energy infrastructure expansion.
The PCE report alleviates near-term Fed fears
- The numbers: Core PCE — the Federal Reserve’s preferred inflation metric — cooled to 3.0% year on year, below Wall Street projections of 3.3%.
- The impact: The soft reading dragged the probability of an October Fed hike down to 35%, triggering an intraday short-covering rally in mega-cap technology equities. The Nasdaq rose 0.2%.
Yields rebound to multi-decade highs anyway
- Despite the cooling print, heavy sovereign debt supply and a resilient US consumer — spending rose 0.6% — fuelled an aggressive afternoon selloff across fixed income.
- US Treasuries: The 10-year reversed sharply to finish at 5.304%, its highest since May 2002. The 30-year crossed the 5.6% threshold.
- Global spillover: The yield surge locked in the STOXX 600’s first monthly loss in six months, down 2.5%, and kept the dollar index near a 16-month high against the euro.
Supply shocks and mega-inflows in emerging markets
- AI tailwinds: Japan’s Nikkei 225 skyrocketed 1.94% to 66,753.72, carried by a 6% rally in SoftBank Group following funding news for OpenAI.
- The Lamu energy corridor: East African markets were dominated by the official groundbreaking of the $16 billion Dangote East Africa Petroleum Refinery in Kenya. Its pledge to launch a $1.6 billion IPO on the NSE shifted regional frontier sentiment, anchoring the shilling at 129.79.
- Capital reversals: South African assets rallied on a R49.8 billion second-quarter FDI influx, while Nigerian equities pulled back 0.28% as traders braced for a ₦2.21 trillion public debt pipeline into Q4.
Commodities
Figures as at · Settlement prices for 30 September 2026, as reported in this brief
Energy cools on infrastructure breakthroughs
- Brent crude: Settled down slightly but stayed firmly above $100 a barrel on Middle East risk premiums.
- WTI crude: Traded near $96.50 a barrel.
- What moved it: Prices fell intraday after Saudi Arabia partially reopened its East–West pipeline, easing transit bottleneck anxieties. In East Africa, the $16 billion Lamu groundbreaking shifted sentiment on regional fuel supply chains.
Gold under pressure from spiking yields
- Spot gold: Traded lower, consolidating around $2,580 an ounce.
- Why: Upside stayed restricted despite the softer PCE print. With the 10-year at 5.304%, a 24-year high, the opportunity cost of holding non-yielding bullion rose and capital stayed in the dollar.
Agriculture
- Coffee: Kenya’s 2025/2026 coffee trading year closed at the Nairobi Coffee Exchange, generating Sh841.3 million from the auction of 17,765 bags. Stanbic Bank joins as a second Direct Settlement System provider, which should shorten farmer payout timelines in the new season.
- Wheat and corn: US and European grain futures edged down 1.2% on improved late-season North American yields, though high fertiliser and logistics costs kept the baseline expensive for net importers.
United States
Figures as at · Closing levels for 30 September 2026, as reported in this brief
The Nasdaq rallied while the S&P 500 and Dow retreated — a split session in which the index gain masked unusually narrow breadth.
Major US indices
| Index | Close | Change |
|---|---|---|
| Nasdaq Composite | 26,797 | +0.2% |
| S&P 500 | 7,651.54 | -0.3% |
| Dow Jones Industrial Average | 51,349 | -0.9% (over 400 points) |
What drove it
- Inflation relief: Core PCE cooled to 3.0% year on year in August, down from 3.3%, dropping October hike odds to 35%.
- Breadth weakness: Robust Q2 GDP revisions and strong September ADP private payrolls reinforced a higher-for-longer baseline. Roughly 75% of S&P 500 stocks posted net losses for the month.
Fixed income
- 10-year benchmark: After briefly dropping on the soft print, it reversed to 5.304% — the highest intraday level since May 2002.
- 30-year bond: Crossed the 5.6% threshold as concerns over debt issuance and Middle East energy disruption weighed on long-dated assets.
- 2-year note: Eased to 4.877% as traders priced out near-term hikes following a dovish pause speech by New York Fed President John Williams.
Forex
- Dollar index: Preserved its monthly expansion, keeping the euro locked near a 16-month floor.
Europe
Figures as at · Closing levels for 30 September 2026, as reported in this brief
Equities closed lower, marking their first monthly loss in six months on surging global bond yields and rising inflation risk.
Equities and bonds
- STOXX 600: Closed 0.5% lower, down 2.5% for the month, on energy-price shocks and hawkish central bank outlooks. Utilities and mining gained early then reversed with the broader market.
- Bond yields: Eased slightly following softer US data and Fed comments, after hovering near multi-decade highs earlier in the week. German 10-year Bund yields pulled back for a second consecutive session.
Forex and macro
- Euro: Remained pressured near 16-month lows against a strong dollar.
- Inflation: Higher-than-expected French CPI at 3.0% year on year fuelled ECB rate hike fears.
- Commodities: Brent stayed above $100 a barrel amid persistent Middle East supply concerns.
Asia
Figures as at · Closing levels for 30 September 2026, as reported in this brief
Markets staged a sharp rebound, snapping a three-session losing streak as a slump in crude and strong demand for AI-related technology shares eased inflationary concerns ahead of key US data.
Equities
- Japan: The Nikkei 225 jumped 1.94% to 66,753.72, spearheaded by a 6% rally in SoftBank Group on funding news for OpenAI.
- China: The Shanghai Composite finished 0.31% higher at 3,842.19 and Hong Kong’s Hang Seng edged up 0.37%.
- South Korea: The Kospi rebounded 0.65%, carried by semiconductor manufacturers bucking the month’s downward momentum.
Bonds and currencies
- Japan: The 10-year JGB eased two basis points to 3.07%, while the policy-sensitive 2-year stayed elevated near 1.975% on BoJ tightening expectations. Regional stabilisation was aided by the US 30-year pulling back from its 24-year high of 5.61%.
- USD/JPY: Fluctuated heavily before settling near 157.35, with traders wary of intervention near the 160 threshold.
- Emerging Asian FX: The Indian rupee and Indonesian rupiah locked in monthly losses of nearly 1% as the narrowing yield differential sapped the appeal of oil-importing economies.
Africa
Figures as at · Closing levels for 30 September 2026, as reported in this brief
African markets closed the third quarter with contrasting local movements. Month-end domestic data cushioned the southern and eastern regions, while rising global rates and heavy local issuance pipelines made for a harder environment in West Africa.
Southern Africa
- Equities: The FTSE/JSE All Share Index dropped 0.85% to 108,506.88, mirroring late-quarter global tech rotations.
- The rand firms: The rand traded at 16.3575 per dollar, insulated by M3 money supply growth accelerating to 8.89% and private sector credit expanding 7.47%.
- Bonds: The 30-year South African government bond yield pulled back to 9.22%, minor relief amid global fixed-income volatility.
West Africa
- NGX correction: The All-Share Index contracted 701.53 points, down 0.28% to 251,211.67, dragging market capitalisation to ₦163.10 trillion as high-cap financial and banking equities faced pricing pressure.
- Liquidity: Over 1.03 billion shares changed hands across 44,398 transactions despite the correction.
- Macro headwinds: Research flagged a dense pipeline of ₦2.21 trillion in open primary market offerings heading into the final quarter.
North Africa
- EGX30: Fell 0.8% to 51,894.83 on turnover of EGP 8.8 billion, 23.5% below the 90-day rolling average.
- Sector split: Abu Qir Fertilizers (-3.2%) and Orascom Development (-3.1%) dragged, while real estate buffered — Emaar Misr rose 10.2% and Palm Hills Developments 2.0%.
- Bonds: The Egypt 10-year settled flat at 23.090% and 3-month bills sat at 24.482%.
Kenya Corporate News
Figures as at · As reported in this brief
Inflation hits a 32-month high
- The data: Annual inflation accelerated to 6.8% year on year in September, up from 6.6% in August, according to the Kenya National Bureau of Statistics.
- Drivers: Persistent domestic food and energy price shocks.
- Policy impact: The 6.8% reading sits above the CBK’s 6.5% internal target, so analysts widely expect the monetary policy committee to tighten liquidity or raise rates rather than resume cuts.
Dangote breaks ground in Lamu
- Groundbreaking: President William Ruto and Aliko Dangote officially broke ground on the $16 billion East African Oil Refinery in Mokowe, Lamu County.
- Defiance: Despite a court order pausing the project over environmental and land disputes, Dangote publicly dismissed the halt and pressed forward with engineering partner Honeywell Technologies.
- NSE listing pledge: Dangote re-confirmed that a significant portion of the project will be listed on the Nairobi Securities Exchange to foster local ownership.
Corporate and agriculture
- Quickmart IPO: Retail interest stayed focused on Quickmart, which targeted 30 September to open its 2-billion-share offer-for-sale via Sokoni Retail Kenya.
- Coffee auction: The 2025/2026 trading year closed at the Nairobi Coffee Exchange with Sh841.3 million from 17,765 bags. Stanbic Bank Kenya joins Co-operative Bank as a second Direct Settlement System provider.
Nairobi Securities Exchange
Figures as at · Nairobi Securities Exchange session data for 30 September 2026, as reported in this brief
Major NSE indices, 30 September 2026
| Index | Close | Change | Focus |
|---|---|---|---|
| NSE All-Share Index (NASI) | 245.60 | -0.25 (-0.10%) | Tracks overall market capitalisation |
| NSE 20-Share Index | 4,316.96 | +4.96 (+0.12%) | Price-weighted index of top blue-chips |
| NSE 25-Share Index | 6,977.73 | -7.86 (-0.11%) | Tracks the top 25 most liquid counters |
| NSE 10-Share Index | 2,734.86 | -5.75 (-0.21%) | The ten most heavily traded counters |
| Banking Sector Index | 288.88 | -1.03 (-0.36%) | The major listed commercial banks |
Market summary
- Market capitalisation: KSh 4,121.65 billion, down KSh 4.22 billion on the session.
- Trading volumes: 12,113,575 shares traded for an equity turnover of KSh 539,558,475.76 across 12,819 deals.
- Derivatives: Turnover of KSh 7,826,752.00 with 19,305 open interest units.
Movers
- Top gainers: Car and General (K) Ltd (+2.27%), Flame Tree Group Holdings (+1.90%), Nairobi Business Ventures (+1.56%), Britam Holdings (+1.35%) and East African Breweries (+1.13%).
- Top losers: Home Afrika and Uchumi Supermarket both fell 2.73%. I&M Holdings and KCB Group fell 1.35%, and the Nairobi Securities Exchange Plc itself 1.62%.
Kenya Forex
Figures as at · As reported in this brief
The shilling closed stable at 129.79 per US dollar, balancing a late-session global decline in the greenback against growing domestic inflationary pressure.
Why the shilling is holding
- Agricultural earnings: Strong inflows from tea and horticulture exports continue to provide steady dollar supply.
- Late-day dollar relief: A drop in the dollar index late on Wednesday, triggered by softer US data, relieved immediate devaluation pressure.
- Diaspora inflows: Consistent remittances continue to match commercial dollar demand from fuel and machinery importers, preventing sudden spikes.
Tighter liquidity looming
- Inflation above target: September’s 6.8% print sits above the CBK’s preferred 6.5%, and analysts expect the committee to tighten liquidity or raise rates to prevent capital flight.
- Bond auction: The CBK ran a primary auction targeting KSh 50 billion across two long-term Treasury bonds, FXD3/2019/015 and FXD1/2019/020, carrying coupons of 12.34% and 12.87%, to mop up excess liquidity.
- Infrastructure inflows: The Lamu groundbreaking signalled future capital inflows, improving long-term sentiment on Kenya’s balance of payments.
Real Estate
Home buyers face severe financial pressure despite a structural boom in infrastructure and satellite development. Residential prices rose 4.8% annually and mortgage rates stabilised to an average of 13.5%, but credit is tightening sharply.
Residential and affordable housing
- Likoni Heights: Phase one of the Mombasa affordable housing project reached 55% completion in late September. The 648-unit scheme was inspected by President William Ruto.
- Satellite backlash: In Kahawa Sukari, welfare associations are pushing back against multi-dwelling apartment blocks to protect single-family zoning. Land values there average Sh15 million per plot despite uneven sewerage.
- Satellite land prices: Ruiru leads raw land growth at roughly KSh 42.2 million per acre, followed by Thika at KSh 32.4 million as it prepares for city status.
- Regional disadvantage: Knight Frank’s regional index shows Kampala and Dar es Salaam extending their rent yield dominance over Nairobi in prime warehouse and industrial property for a second year.
The credit crunch
- Mortgage defaults rocket: Central bank indicators show a 105.8% increase in mortgage accounts classified as non-performing — more than double the missed housing payments of a year ago — as lenders tighten terms.
- Saccos fill the gap: With mortgages out of reach at double-digit rates, Saccos are now the dominant financier: land and housing took 26.35%, over KSh 157 billion, of the KSh 596.54 billion Sacco credit pipeline.
- NCBA and Optiven: The two renewed an MoU allowing domestic and diaspora buyers up to 105% property financing, with the extra 5% covering legal, closing and transaction costs such as stamp duty and valuation.
Land legalities
- Mombasa road reserve ruling: The Environment and Land Court cancelled a 32-year-old lease on a parcel along Machakos Road in Mombasa after proving the land was originally part of a public road reserve — a warning on the need for historical land searches before buying.
- Ruaraka payout cancelled: The Court of Appeal threw out a Sh2.4 billion consent order and judgment, returning the ownership dispute to the Environment and Land Court for fresh determination.
- Construction costs: Developers closing the quarter noted that global supply chain headwinds have pushed local material costs up, threatening the pricing of upcoming off-plan deliveries.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.8%
Year-on-year headline CPI.
As at
KNBS CPI, Sep 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.79
Steady, anchored by the Lamu announcement and a late-session dollar decline.
As at
Closing interbank rate, as reported in this brief
Equities
NSE All-Share (NASI)
245.60
-0.25 (-0.10%)
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,316.96
+4.96 (+0.12%)
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,977.73
-7.86 (-0.11%)
As at
Nairobi Securities Exchange, as reported in this briefNSE 10-Share
2,734.86
-5.75 (-0.21%)
As at
Nairobi Securities Exchange, as reported in this briefNSE Banking Sector Index
288.88
-1.03 (-0.36%)
As at
Nairobi Securities Exchange, as reported in this briefMarket capitalisation
KSh 4.12tn
KSh 4,121.65bn, down KSh 4.22bn on the session
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 539.56m
12.11m shares across 12,819 deals
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
Held, but September inflation above target has the market expecting tightening.
As at
Central Bank of Kenya — Monetary Policy Committee, as published on this brief’s artwork
At a glance
- 1Cooling inflation did not cool yields. Core PCE at 3.0% cut October hike odds to 35%, yet the 10-year still reversed to 5.304% — supply and a resilient consumer are now setting the long end, not the Fed.
- 2Kenyan inflation hit a 32-month high of 6.8% in September, above the CBK’s 6.5% target, so the market expects tightening rather than the cuts that were on the table a month ago.
- 3Dangote broke ground on the $16 billion Lamu refinery despite a court order, and re-confirmed a $1.6 billion NSE listing — the largest prospective addition to the Nairobi bourse in years.
Sources
- Serrari Group desk compilation, 1 October 2026
- Kenya National Bureau of Statistics — September CPI
- Nairobi Securities Exchange — daily market statistics
- Central Bank of Kenya — Treasury bond auction