
30 September 2026
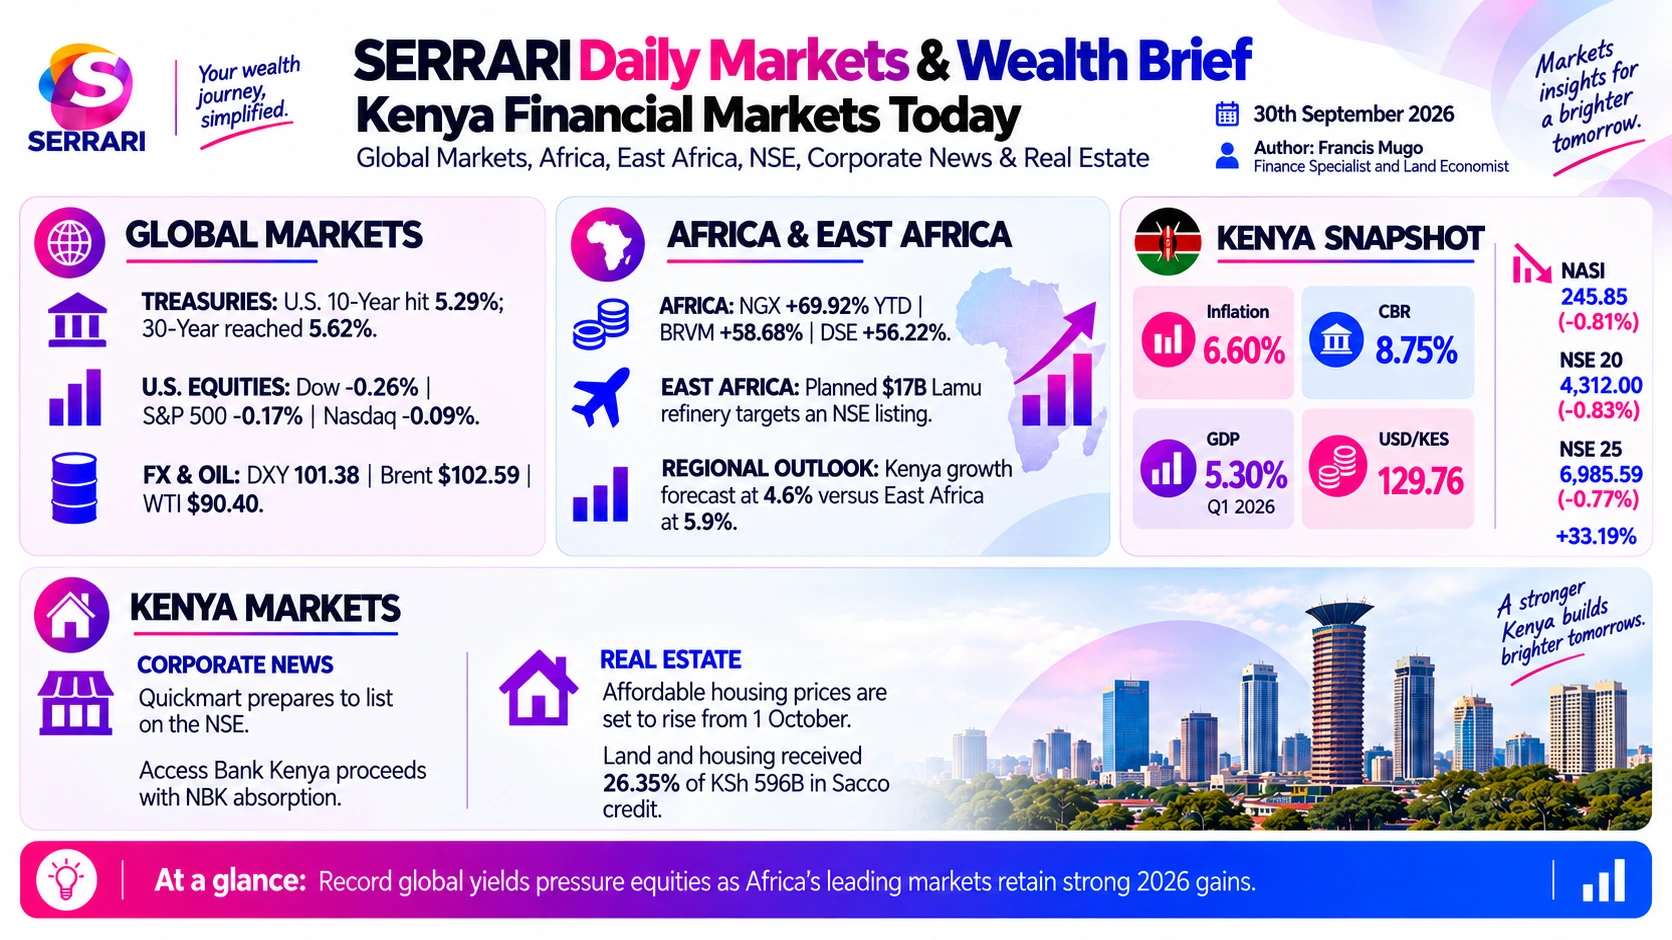
The 30-year Treasury at 5.62% is the highest since 2002, and a surprise RBA hike hardened the higher-for-longer case worldwide. Dangote will list the $17 billion Lamu refinery on the NSE, and Kenya is still up 33.19% for the year.

Global Markets
Figures as at · Closing levels for Tuesday 29 September 2026, as reported in this brief
Markets were gripped by intense volatility as a historic rout in global fixed income pushed long-term government bond yields to multi-decade highs. A macro triple threat — surging borrowing costs, sticky energy-led inflation and a booming dollar — forced global equities down for a second consecutive session.
What drove it
- Multi-decade sovereign yields: The US 30-year vaulted to 5.62%, its highest since June 2002, and the 10-year climbed to 5.29%, a peak not seen since June 2007. The German 10-year Bund hovered near 3.61%, its highest since 2009. Safer, high-yielding Western government debt pulled foreign institutional capital out of emerging market equities.
- A surprise RBA hike: The Reserve Bank of Australia unexpectedly raised its cash rate 25 basis points to 4.60%, citing stubborn service-sector inflation and supply-chain vulnerabilities. The move stoked fears that other major central banks would prolong high-rate cycles rather than pivot to cuts.
- Energy vulnerability: Middle East tensions kept energy volatile, with Brent fluctuating near multi-month highs around $96.16 a barrel, and European natural gas pushing past €80 per megawatt-hour — its highest since late 2022 — as the region entered its heating season.
- European fiscal risk: The France–Germany 30-year bond spread surged to a 14-year high of 140.9 basis points, exposing cracks in eurozone fiscal harmony ahead of sovereign credit rating reviews.
- A booming dollar: The dollar index advanced to 101.38, striking fresh 16-month highs against the euro and Swiss franc. The euro slid near $1.14 and the yen traded weakly around 157.03, prompting fears that Tokyo and Washington might intervene jointly.
- AI optimism against retail weakness: Tech found a temporary buffer in speculative reports of a public market IPO prospectus from Anthropic. Against that, Shein fell over 11% in Hong Kong after a disappointing first-half report, dragging hardware and semiconductor suppliers down.
United States
Figures as at · Closing levels for 29 September 2026, as reported in this brief
All three major Wall Street indices closed in the red for a second session as investors weighed elevated borrowing costs against cooling energy prices.
Major US indices
| Index | Close | Change |
|---|---|---|
| Dow Jones Industrial Average | 51,349.92 | -131.59 (-0.26%) |
| S&P 500 | 7,670.84 | -12.85 (-0.17%) |
| Nasdaq Composite | 26,797.54 | -22.84 (-0.09%) |
Corporate movers
- Meta Platforms: Rose over 3% after launching an AI agent workflow for small businesses, limiting the Nasdaq’s losses.
- Banks retreat: JPMorgan Chase and Bank of America led a financial sector retreat.
- Fair Isaac Corp: Plummeted 27% after housing regulators introduced a credit-scoring competitor.
Treasury yields
- 10-year note: Cleared a 19-year high, touching an intraday peak of 5.293% before settling.
- 30-year bond: Vaulted to 5.6206%, its highest level since June 2002.
- 2-year note: In contrast to the long bond, shorter-dated yields dipped on less hawkish rate commentary from John Williams.
Forex and commodities
- Dollar index: Advanced 0.2% to 101.38, hitting fresh 16-month highs against the euro and Swiss franc.
- Crude: Brent fell 2.6% to $102.59 a barrel and WTI slid 2.4% to $90.40. The drop gave stocks slight reprieve, though oil stays volatile on US–Iran tensions.
- Gold and crypto: Gold futures bucked the stronger dollar to rise 0.9% to $4,205 an ounce. Bitcoin hovered around $83,400.
Europe
Figures as at · Closing levels and yields for 29 September 2026, as reported in this brief
European indices opened higher on AI optimism and chip stocks, then gave it back: broad profit-taking into the close dragged banking, energy and consumer goods heavyweights down.
Major European indices
| Index | Close | Change |
|---|---|---|
| STOXX Europe 600 | 638.08 | -0.09%, after an intraday 0.7% rally |
| DAX (Germany) | 25,399.21 | +0.10% |
| CAC 40 (France) | — | -0.53% on luxury and banking pressure |
| FTSE 100 (UK) | 10,636.71 | -0.45% |
| FTSE MIB (Italy) | 51,804.94 | +0.09% |
Sovereign bonds
- German 10-year Bund: Eased 3 basis points to 3.61%, remaining near its highest since June 2009.
- Euro area 10-year benchmark: Structurally high at 4.07%.
- Widening risk premiums: Core yields paused, but political and fiscal uncertainty ahead of upcoming elections pushed the French–German spread to its highest in 14 years. ECB President Christine Lagarde signalled a measured response even as markets price potential hikes by December on year-end inflation approaching 4%.
Forex
- EUR/USD: 1.1338 — a fresh 16-month low, with European Commission economic sentiment slipping to 97.9 eroding domestic confidence further.
- GBP/USD: 1.3238 with a bearish bias. Hawkish comments from Bank of England Deputy Governor Dave Ramsden, hinting at hikes to counter energy-led inflation, kept sterling off its monthly baselines.
Asia
Figures as at · Closing levels for 29 September 2026, as reported in this brief
The region faced the same macro triple threat: multi-decade high US yields, geopolitically driven crude, and a dominant dollar sharply curtailed risk appetite across major trading hubs.
Major Asian indices
| Index | Close | Change | Driver |
|---|---|---|---|
| Nikkei 225 (Japan) | 65,481.27 | -1.2% | The broader Topix dropped 1.5%, led by defence-linked and industrial counters facing operational losses. |
| Hang Seng (Hong Kong) | 24,523.57 | -0.5% | Shein plummeted over 11% on weaker-than-expected first-half earnings. |
| KOSPI (South Korea) | 6,847.56 | -0.6% | Samsung Electronics and SK Hynix dragged index aggregates lower. |
| BSE Sensex (India) | 72,529.07 | -242 (-0.33%) | The Nifty 50 declined to 22,716.20 as foreign institutional outflows weighed on the market. |
Rates and currencies
- The RBA hike: The Reserve Bank of Australia raised its official cash rate 25 basis points to 4.60%, necessitated by rising global energy overheads and domestic core inflation stickiness.
- Sovereign outflows: Rising Western yields continued drawing capital away from emerging market fixed income, driving regional bond selloffs to maintain relative spreads.
- USD/JPY: 157.03 — intraday drops capped by fear that Tokyo and Washington might intervene jointly to support the yen.
- AUD/USD: The day’s standout, rallying toward 0.7050 directly after the RBA decision.
- Rupee and yuan: The rupee stayed pinned near historic lows on the cost of crude imports, while the yuan found support after a firmer-than-expected PBOC midpoint fixing.
Africa
Figures as at · Year-to-date returns in US dollars, as reported in this brief
African equity markets are seeing record-breaking momentum, led by macroeconomic reforms, massive corporate listings and resurgent foreign participation. Many African indices are heavily outperforming international benchmarks this year.
Top African exchanges, year to date 2026 (USD)
| Market | Index | YTD | Drivers |
|---|---|---|---|
| Nigeria | NGX All-Share | +69.92% | The $1.6 billion Dangote Petroleum Refinery IPO and sharp rate adjustments pushed NGX market cap to a record N164 trillion this week. |
| West Africa | BRVM Composite | +58.68% | Liquidity injection after the Bridge Bank Group Côte d’Ivoire IPO, which was 142% oversubscribed. |
| Tanzania | DSE All-Share | +56.22% | Supported by cross-border trade expansion and maritime gateways with Middle Eastern partners. |
| Kenya | NSE All-Share | +33.19% | Weekly leader with a 4.15% single-week rebound, restoring KSh 166 billion as banking stocks rallied. |
| Egypt | EGX 30 | +25.12% | Tech ecosystem growth and a pending listing of 1.6 billion shares by MNT Tech Holding. |
| South Africa | JSE All-Share | +2.04% | Flat as investors take profit amid currency fluctuations; the index tracks around 109,483 points. |
Market-moving developments
- The mega-IPO wave: Nigeria is absorbing the Dangote refinery listing while Kenya’s NSE has announced the Quickmart Supermarkets listing alongside a planned dual-listing of the $17 billion Lamu refinery project.
- The frontier bond shift: JPMorgan is finalising its Local-Currency Frontier Bond Index, where Africa is slated to command a 45% overall weighting.
- Sub-Saharan consolidation: Access Bank Kenya is completing its absorption of the National Bank of Kenya, and Old Mutual has debuted on the Victoria Falls Stock Exchange.
Currencies against the dollar
- Tunisian dinar 2.95. Moroccan dirham 9.58. Ghanaian cedi 11.58. South African rand 16.40. Zimbabwe Gold 26.65. Mauritian rupee 47.80. Egyptian pound 51.60. Kenyan shilling 129.76. CFA franc 573.75. Malawian kwacha 1,745.11.
- Retail forex boom: Fintech growth across Lagos, Nairobi and Johannesburg drove a 30% surge in retail volume this year, with nearly 70% of active young traders using AI tools and automated bots. Regulators are tightening rules in response.
East Africa
Figures as at · As reported in this brief
The region was dominated by a multi-billion dollar energy mega-project, cross-border capital updates and trade policy moves.
Dangote to list the $17 billion Lamu refinery on the NSE
- The announcement: At an investor summit in Nairobi, Aliko Dangote said the planned $17 billion (Sh2 trillion) East Africa Oil Refinery in Lamu will be listed on the Nairobi Securities Exchange.
- Public stakes: President William Ruto confirmed the Kenyan government will take a strategic equity stake, with shares fully opened to everyday Kenyan investors.
- Regional backing: The Dangote Group retains 70%, while East African governments including Kenya and Rwanda split the remaining 30%, with a flexible four-year payment window.
- Legal hurdle: A challenge by 133 residents in the Malindi Environment and Land Court ordered the status quo maintained until a hearing on 14 October. Dangote and Ruto both asserted the groundbreaking will proceed; the order may restrict heavy site clearing but does not bar the ceremonial launch of the 700,000 barrel-per-day hub. Flights to Lamu’s Manda Airport are fully booked.
Regional macro
- Growth downgrades: The African Development Bank trimmed Kenya’s 2026 growth outlook to 4.6%, trailing the East African regional average of 5.9%, on logistical disruption in the Middle East and rising fertiliser costs.
- Monetary policy: Central banks across East Africa have temporarily halted rate cuts to buffer local currencies, while the East African Business Council renewed talks on the EAC Single Currency framework.
- Qatar and Tanzania: Tanzania negotiated a bilateral agreement with Qatar establishing Dar es Salaam as a Gulf trade gateway, creating direct supply-chain competition with Kenya’s LAPSSET and Mombasa corridors.
Regional currencies against the dollar
- Kenyan shilling 129.76. Tanzanian shilling 2,635.00. Ugandan shilling 3,914.86. Rwandan franc 1,475.00. Ethiopian birr 160.98.
- The Kenyan cushion: Kenya’s reserves remain steady at $15.25 billion, minimising intraday volatility for regional businesses using the shilling corridor.
Nairobi Securities Exchange
Figures as at · Nairobi Securities Exchange session data for 29 September 2026, as reported in this brief
Broad-market profit-taking produced measured drops across the key indices, a fractional pullback against a quarter in which the NSE has been one of the strongest frontier markets.
Major NSE indices
| Index | Close | Change |
|---|---|---|
| NSE All-Share Index (NASI) | 245.85 | -2.02 (-0.81%) |
| NSE 20-Share Index | 4,312.00 | -36.25 (-0.83%) |
| NSE 25-Share Index | 6,985.59 | -54.36 (-0.77%) |
Trading action
- Top gainers: Nairobi Securities Exchange Plc, CIC Insurance Group, Flame Tree Group Holdings and Kenya Re-Insurance Corporation.
- Top decliners: Profit-taking on Safaricom Plc, Centum Investment Company, Britam Holdings and HFCB Group.
Triggers and strategic shifts
- Supermarket mega-listing: Quickmart Supermarkets, Kenya’s second-largest retail chain, is preparing to list on the NSE, injecting liquidity into the consumer services sector.
- Banking consolidation: Following final CBK approvals, Access Bank Kenya is proceeding with its absorption of the National Bank of Kenya, streamlining commercial banking stocks on the bourse.
- Recent performance: Despite the pullback, the NSE posted a 4.15% weekly rebound days ago that restored KSh 166.08 billion in investor wealth, and Kenya’s year-to-date equity performance sits over 33% in local currency terms.
Kenya Forex
Figures as at · Central Bank of Kenya official mean rates, 29 September 2026
Official CBK mean rates, 29 September 2026
| Currency | Symbol | CBK mean rate (KES) |
|---|---|---|
| US Dollar | USD | 129.76 |
| Sterling Pound | GBP | 172.10 |
| Euro | EUR | 147.49 |
| Japanese Yen (100) | JPY | 82.57 |
| South African Rand | ZAR | 7.90 |
| Uganda Shilling | UGX | 30.17 |
| Tanzania Shilling | TZS | 20.30 |
| Rwanda Franc | RWF | 11.35 |
Drivers
- Strong forex buffers: Kenya’s official reserves climbed back to $15.25 billion, equivalent to 6.3 months of import cover, protecting the shilling from external shock.
- Monetary policy on hold: CBK Governor Kamau Thugge indicated that planned interest rate cuts are temporarily on hold, on structural inflation risks linked to Middle East tensions.
- Where to trade: Retail bureaus across Nairobi and major towns quote wider margins, generally buying from 128.60 and selling up to 130.60 for physical dollar cash.
Real Estate
The day centred on infrastructural evictions, a landmark land payout ruling, and a hard deadline on the national housing programme.
Headlines
- KeNHA mass eviction notice: The Kenya National Highways Authority gave roadside traders and unauthorised structures 30 days to clear road reserves on four corridors: Likoni–Ukunda–Lunga Lunga (A7), Kilifi–Malindi–Garsen–Witu (A7), Maili Tisa–Kitale (B14) and Eldoret–Nyaru (B124).
- Ruaraka payout thrown out: The courts dismissed a Sh2.4 billion payout tied to the Ruaraka land dispute, a victory for the state against inflated compensation claims on public utility plots.
- Affordable housing deadline: 29 September was the final day to lock in current rates through the Boma Yangu platform. From 1 October the State Department for Housing and Urban Development raises prices to address funding strains and material costs. The programme remains legally active after the Court of Appeal dismissed challenges to the housing levy.
- Sacco credit: Sacco credit disbursements hit KSh 596 billion, with land and housing taking 26.35% of the total — Saccos remain the preferred financing route for Kenyans locked out of commercial bank mortgages.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.6%
Year-on-year headline CPI.
As at
KNBS CPI, Aug 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro dataForeign exchange reserves
$15.25bn
6.3 months of import cover
As at
Central Bank of Kenya, as reported in this brief
Foreign exchange
USD / KES
129.76
Retail bureaus buy from 128.60 and sell up to 130.60.
As at
Central Bank of Kenya official mean rateGBP / KES
172.10
As at
Central Bank of Kenya official mean rateEUR / KES
147.49
As at
Central Bank of Kenya official mean rate
Equities
NSE All-Share (NASI)
245.85
-2.02 (-0.81%)
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,312.00
-36.25 (-0.83%)
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,985.59
-54.36 (-0.77%)
As at
Nairobi Securities Exchange, as reported in this briefNSE year to date
+33.19%
Over 33% in local currency terms
As at
Year-to-date return in US dollars, as reported in this brief
Rates
Central Bank Rate
8.75%
Planned cuts are on hold on structural inflation risk.
As at
Central Bank of Kenya — Monetary Policy Committee, as published on this brief’s artwork
At a glance
- 1The 30-year Treasury at 5.62% is its highest since June 2002 and the 10-year touched 5.293%. Long-dated yields, not equities, are now setting the price of everything.
- 2The Reserve Bank of Australia’s surprise 25 basis point hike to 4.60% told markets that other central banks may prolong tightening rather than pivot to cuts.
- 3Dangote will list the $17 billion Lamu refinery on the NSE, with the Kenyan government taking a strategic stake and shares opened to retail investors.
Sources
- Serrari Group desk compilation, 30 September 2026
- Central Bank of Kenya — official exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data