
28 September 2026
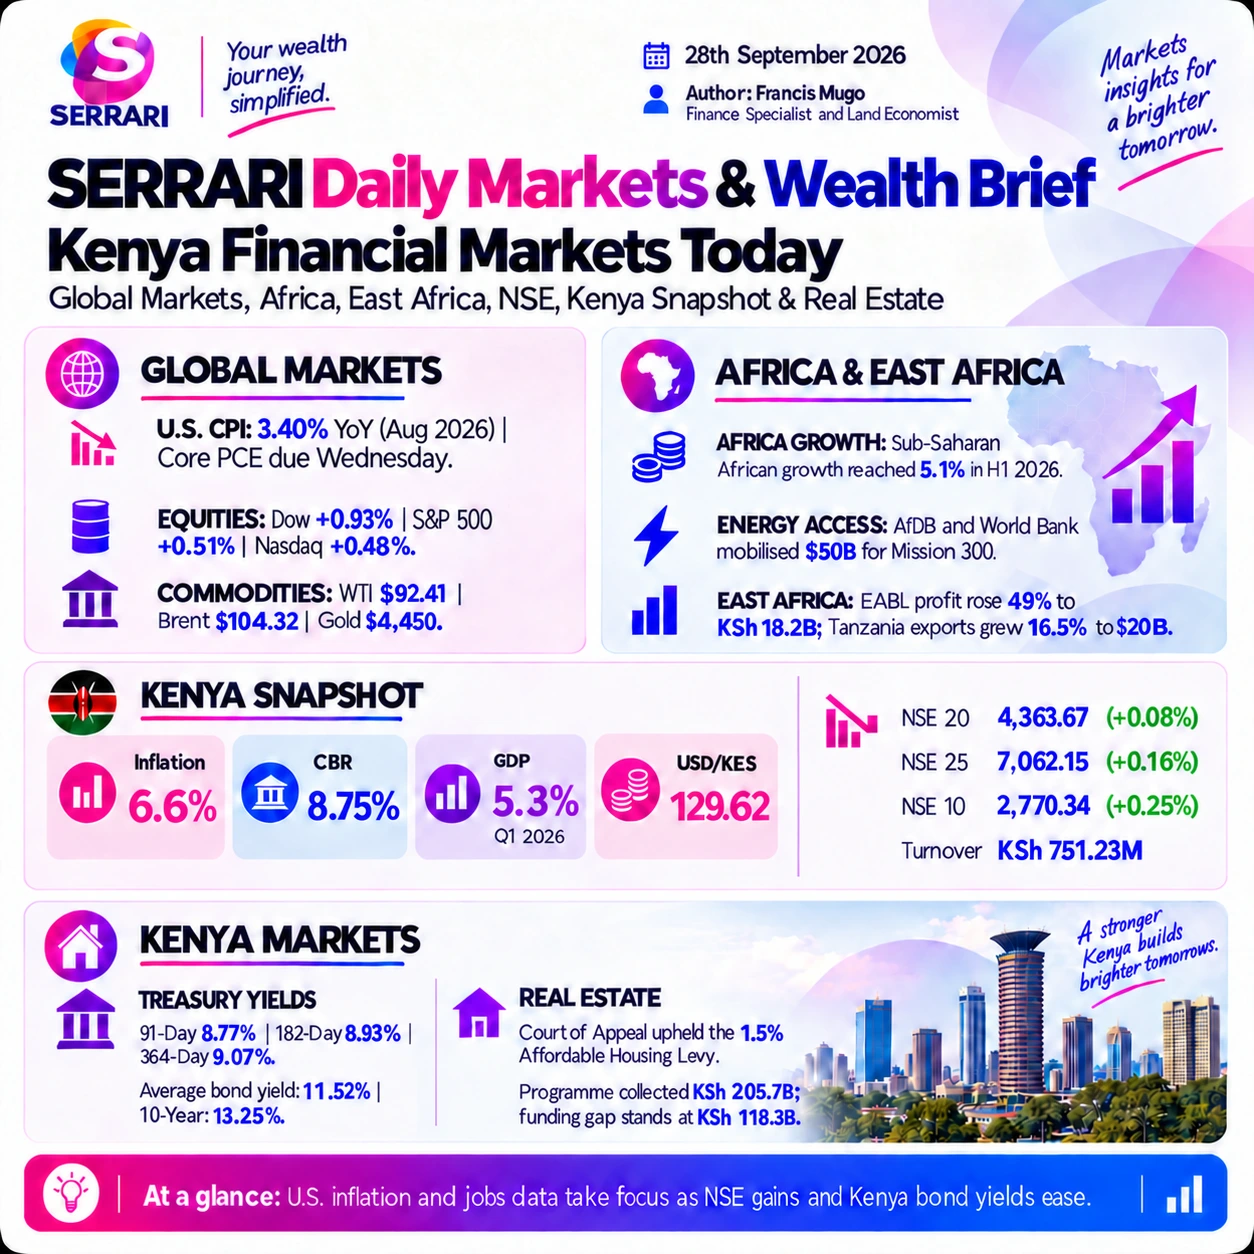
A Middle East diplomatic thaw cooled crude back below $100 and lifted equities into the weekend. Kenya’s T-bill auction came in 198% oversubscribed while the shilling held at 129.48.

United States
The macro focus for the week
- Wednesday’s core PCE inflation release: This will dictate whether corporate borrowing costs continue to escalate.
- Friday’s nonfarm payrolls report: Signals labour market dynamics.
Europe
Market highlights
- Aviation & travel rebound: Jet fuel relief directly supported consumer cyclical travel names. Ryanair and Lufthansa both climbed over 2% following a sharp retreat in crude prices back below the $100 threshold.
- The winter energy crisis premium: LNG competition is intensifying. European benchmark gas prices hover near $24.62 per MMBtu, with analysts warning Europe will need to pay steep premiums to compete against Asian buyers for winter buffers amid ongoing Strait of Hormuz constraints.
Asia
Market highlights
- Currency & trade summit: The Japanese yen swung wildly, strengthening roughly 1.01% to 157.22 per dollar. Finance Minister Satsuki Katayama said US leaders raised formal concerns over prolonged yen weakness during a bilateral summit between Prime Minister Takaichi and President Trump.
- Leaked deal pipelines: Regional sentiment was rattled after a senior Morgan Stanley banker in Asia inadvertently leaked the firm’s private deal pipeline via a client email misfire.
Global Equities
Figures as at · Index closes for Friday 25 September 2026, as reported in this brief
- Key market drivers: A rebound in AI and tech, rising Treasury yields, and sticky inflation concerns including geopolitics and trade.
Major indices performance
| Index | Level | Change |
|---|---|---|
| Dow Jones | 51,828.62 | +0.93% |
| S&P 500 | 7,743.41 | +0.51% |
| Nasdaq Composite | 27,068.72 | +0.48% |
| Nikkei 225 | 66,364.20 | +1.30% |
| Euro STOXX 50 | 6,330.65 | +0.93% |
| Euro STOXX 600 | 640.66 | +0.35% |
| FTSE 100 | 10,695.25 | +0.14% |
| DAX | 25,408.64 | +0.56% |
Commodities
Figures as at
Commodity markets diverged sharply on Friday 25 September 2026, as an energy retreat conflicted with acute physical supply strains across metals and agriculture. Headlines of a potential diplomatic truce in the Middle East sparked a late-week cooling of the global oil premium.
Energy benchmarks
- WTI crude: $92.41 per barrel (-2.33%) — cooled on US–Iran diplomatic progress.
- Brent crude: $104.32 per barrel (-2.14%) — fell back from recent supply-shock highs.
- European natural gas: $24.62 per MMBtu — remains highly elevated ahead of winter.
Precious & industrial metals
- Spot gold: $4,450 per ounce — pressed lower by multi-decade high Treasury yields.
- Copper & aluminium: Elevated, facing global supply deficits from mine halts and energy caps.
Key agricultural futures
- US corn: Above $5.00 a bushel, surging past the milestone following severe USDA yield cuts.
- Raw sugar: Volatile — spur-of-the-moment tariff adjustments in India are shaking up global trade.
Africa
African economies and capital markets are navigating a mix of sovereign rating upgrades, infrastructure milestones and monetary policy actions. Sub-Saharan African growth reached a resilient 5.1% in the first half of 2026, with central banks tightening to counter currency pressures and high global energy overheads.
Key macro & capital market news
- South African rate hike & rand pressure: The South African Reserve Bank raised its benchmark repo rate by 25 basis points to 7.25%.
- Sovereign upgrades & IMF programme completions: Benin finished its IMF-supported programme, prompting a two-notch upgrade from Moody’s to Ba3. Côte d’Ivoire completed its IMF review and issued a $1.3 billion Eurobond on robust international demand.
- De-dollarisation & payment integration: Rwanda’s largest commercial bank integrated into China’s cross-border payment network, a step in Africa’s push to reduce reliance on the US dollar for bilateral trade.
Mega-infrastructure & energy
- The Lobito railway corridor: The US Trade and Development Agency signed fresh agreements to finance reliable power grids along the Lobito Corridor, the railway network connecting copper-rich DR Congo and Zambia to Angolan ports.
- Mission 300 funding drive: The African Development Bank and the World Bank have mobilised $50 billion toward Mission 300, which aims to bring reliable, affordable electricity to 300 million Africans by 2030.
East Africa
Figures as at · Week ending 25 September 2026, as reported in this brief
Markets are showing strong regional momentum, driven by landmark retail listings, soaring corporate earnings and major infrastructure groundbreakings. Despite sticky inflation and high global energy overheads, domestic stock indices are demonstrating localised resilience.
Bourse performance snapshot — week ending 25 September 2026
| Exchange / metric | Latest closing status | Market drivers & key moves |
|---|---|---|
| Nairobi Securities Exchange (NSE) | Resilient / active | Driven by the Quickmart IPO announcement and strong EABL earnings. |
| Dar es Salaam Stock Exchange (DSE) | Domestic cap: TZS 28,328.56bn (+2.49%) | Total capitalisation hit TZS 40,815.12bn; CRDB Bank led weekly trading turnover. |
| DSE weekly turnover | TZS 27.47bn (-48.22%) | Volumes contracted sharply despite an 11.11% share price surge in MUCOBA. |
Key corporate & industrial triggers
- EABL earnings boom: East African Breweries PLC announced a 49% surge in profit after tax to KSh 18.2 billion for FY2026, anchoring investor confidence as it navigates its shareholder transition from Diageo to Asahi.
- Tanzanian export expansion: Tanzania’s macro landscape is supported by 16.5% growth in annual exports to USD 20 billion, supercharged by a 47% surge in gold revenues.
Regional macro pressures
- Imported energy strain: Local Murban crude prices above KSh 12,600 per barrel continue to inject high transport, electricity and utility costs into regional businesses.
- Inflation acceleration: Kenya’s year-on-year headline inflation is tracking toward 6.8% for September, maintaining pressure on consumer discretionary spending. This is a projection, not a published print — the last confirmed CPI figure is in the Kenya Snapshot above.
- Tourism cost warning: A recent World Economic Forum index flagged that rising food, labour and energy inputs are eroding East Africa’s traditional price-competitiveness edge in global travel and safari markets.
Kenya Corporate News
Industrial & infrastructure megaprojects
- Devki Group expansion: The Devki Group completed its KSh 11 billion iron-ore processing plant in Manga, Taita-Taveta County. The facility is slated for official launch in November 2026.
- Tata Chemicals Magadi disruption: The state temporarily suspended the company’s century-old soda ash mining operations in Kajiado County, ordering an exit while a joint technical committee resolves environmental and resource disputes.
Nairobi Securities Exchange
Figures as at · Nairobi Securities Exchange session data for 25 September 2026, as reported in this brief
Major index & performance summary
- NSE 20 Share Index: 4,363.67 (+0.08%) — continues a strong macro performance, up 46.5% year on year.
- NSE 25 Share Index: 7,062.15 (+0.16%).
- NSE 10 Share Index: 2,770.34 (+0.25%).
- Equity turnover: KSh 751.23 million on 18.25 million total shares traded.
Notable stock moves
- Centum Investment: Led the session’s gainers, jumping 4.16% to close at KSh 18.80.
- I&M Holdings: Rose 2.41% to finish at KSh 85.00.
- BK Group: The day’s sharpest decliner, dropping 5.31% to settle at KSh 58.00.
- Standard Chartered Bank Kenya: Fell 2.77% to KSh 324.50 as it traded ex-dividend following its interim payout books closure.
Derivatives
- The NSE Derivatives Market crossed KES 1 billion in year-to-date turnover for 2026, a historic benchmark.
Treasury Bills and Bonds
Figures as at · Central Bank of Kenya auction results and secondary market data, as reported in this brief
T-bills (CBK, 24 September close)
- 91-day: 8.77%.
- 182-day: 8.93%.
- 364-day: 9.07%.
- Down marginally week on week. The auction was 198% oversubscribed — KSh 55.5 billion of bids against KSh 28 billion offered. The 91-day was most in demand at KSh 29.58 billion against KSh 8 billion offered.
T-bonds secondary market — average 11.52% YTM across 58 bonds
- 2-year: 9.98% (8.98% after 10% withholding tax).
- 5-year: 11.29% (10.16% net).
- 10-year: 13.25% (11.93% net) — the sweet spot.
- 15-year: 12.44% (11.20% net).
- 20-year: 12.01% (10.81% net).
Top scoring bonds (yield, price and risk)
- FXD1/2010/25Yr: 12.89% YTM, price 91.54 (discount).
- SDB1/2011/30Yr: 12.60% YTM, price 96.03.
- FXD3/2019/15Yr: 12.58% YTM, price 98.81.
Current primary offer — closes Tuesday 30 September, 10am
- FXD3/2019/015: 12.34% coupon, matures 10 July 2034 (7.8 years left).
- FXD1/2019/020: 12.873% coupon, matures 21 March 2039 (12.5 years left).
- CBK is seeking KES 50 billion for each tranche. Minimum KSh 50,000 non-competitive, KSh 2 million competitive, via the DhowCSD app. Settlement 5 October, 10% withholding tax.
- Last auction, 18 September: Investors asked 13.68% average for the 20-year and 14.23% for the 30-year; CBK rejected KSh 31 billion of KSh 81 billion in bids to tame costs. Expect similar — bid 13.5–14% to win.
Kenya Forex
Figures as at · Interbank indicative rates, as reported in this brief
- KES/USD: 129.48 — range-bound this week, sideways.
- KES/GBP: 171.73.
- KES/EUR: 147.62.
- Regional: 30.14 UGX, 20.46 TZS, 11.37 RWF to the shilling.
- Reserves: $15.04 billion (6.1 months of import cover) — a $46 million dip, but still above the 4-month statutory floor, with diaspora remittances providing support.
- Expected range: KES/USD 129.00–129.80 this week.
Real Estate
Landmark legal victory for the state housing programme
- Levy upheld by the Court of Appeal: On Friday 25 September 2026 a five-judge bench upheld the Affordable Housing Act as constitutional, dismissing 42 separate cases that sought to dismantle the mandatory 1.5% statutory housing levy on workers and employers.
- Funding unlocked but strained: While the ruling secures long-term capital flows for contractors and suppliers, a budget advisory report flagged that the programme still faces a KSh 118.3 billion funding hole to complete its current fiscal phase. The state has collected a cumulative KSh 205.7 billion via the levy since 2023.
- Occupancy milestones: Over 10,000 affordable units are now complete. The 220-unit Boma Yangu project in Milimani, Kakamega County, reached 100% occupancy this week.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
6.6%
Year-on-year headline CPI.
As at
KNBS CPI, Aug 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
129.48
Range-bound; expected 129.00–129.80 this week
As at
Interbank indicative rate, as reported in this briefEUR / KES
147.62
As at
Interbank indicative rate, as reported in this briefGBP / KES
171.73
As at
Interbank indicative rate, as reported in this brief
Equities
NSE 20-Share
4,363.67
+0.08%; up 46.5% year on year
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
7,062.15
+0.16%
As at
Nairobi Securities Exchange, as reported in this briefNSE 10-Share
2,770.34
+0.25%
As at
Nairobi Securities Exchange, as reported in this briefEquity turnover
KSh 751.23m
18.25m shares traded
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
The prevailing policy rate on the date of this brief.
As at
Central Bank of Kenya — Monetary Policy Committee, as published in this brief91-day T-bill
8.77%
Auction 198% oversubscribed
182-day T-bill
8.93%
364-day T-bill
9.07%
At a glance
- 1Crude cooling on US–Iran diplomacy lifted travel and cyclical names — Ryanair and Lufthansa both climbed over 2%.
- 2Kenya’s T-bill auction was 198% oversubscribed (KSh 55.5bn of bids against KSh 28bn offered), and rates edged down across all three tenors.
- 3The Court of Appeal upheld the 1.5% Affordable Housing Levy, dismissing 42 challenges and securing the programme’s funding line.
Sources
- Serrari Group desk compilation, 28 September 2026
- Central Bank of Kenya — Treasury bill auction results
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data