
19 November 2026
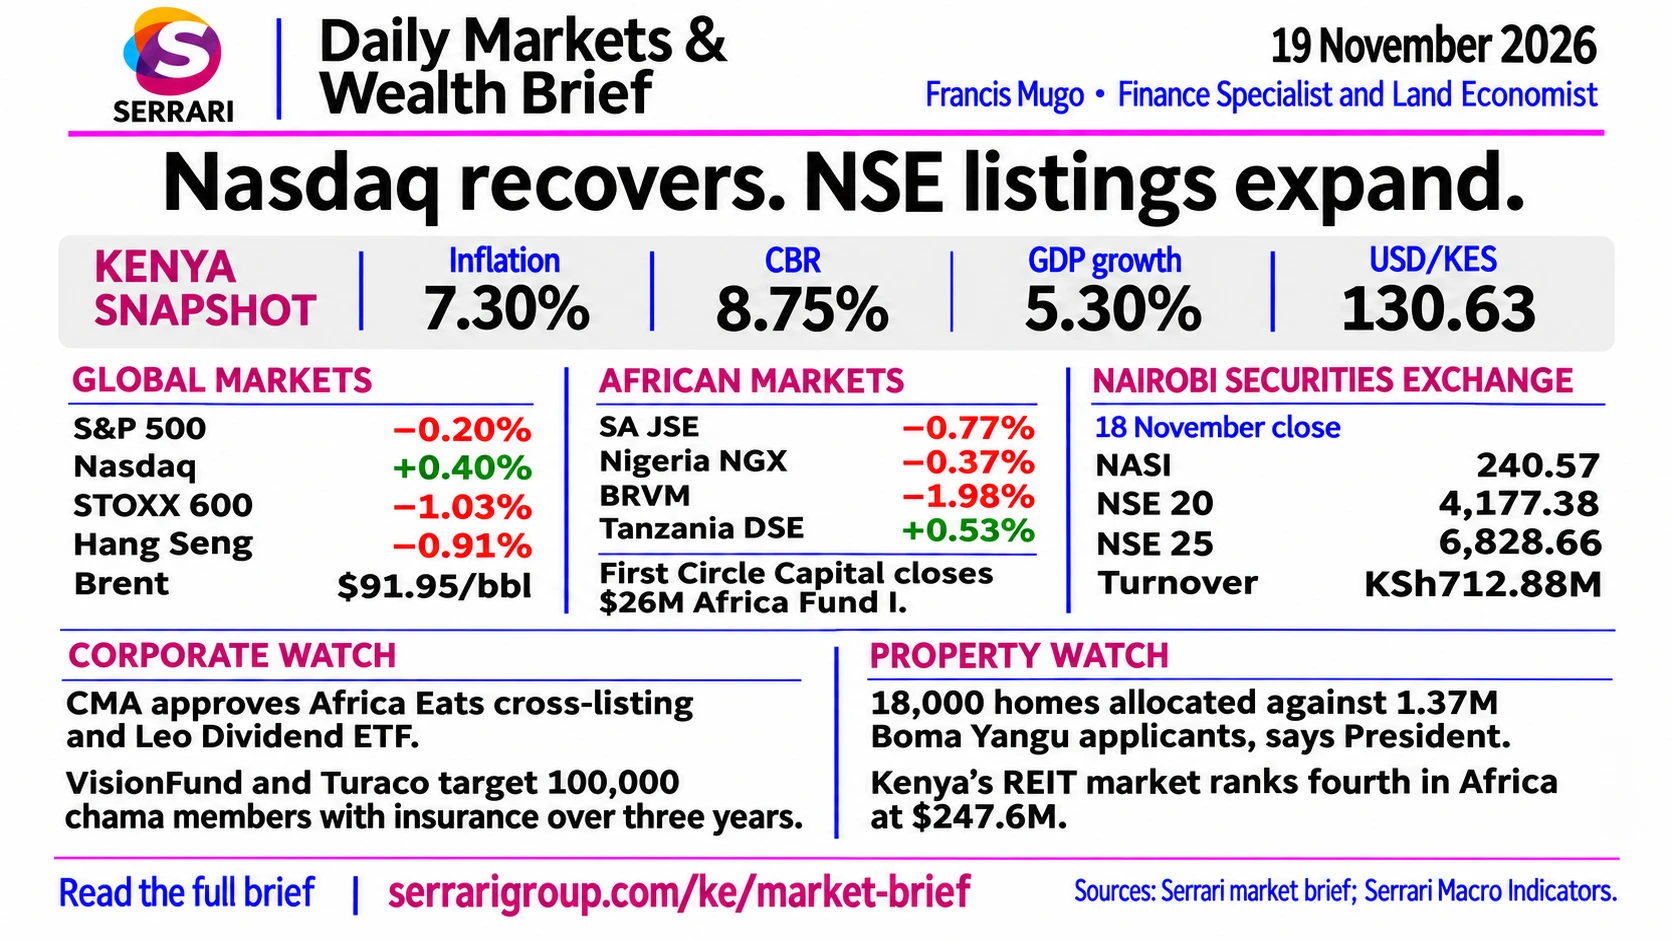
The CMA approved Africa Eats’ cross-listing on the NSE and the Leo Dividend ETF, while the Nasdaq rose 0.4% to end a four-day slide. In Nairobi, NSE 20 and NSE 25 gained as NASI slipped 0.14% to 240.57 on KSh 712.88 million turnover.
Global Markets
Figures as at · Market data for Wednesday 18 November 2026, as reported in this brief
Global markets swung on AI valuation doubts, a hawkish Federal Reserve outlook and falling commodity prices. US markets ended mixed as investors weighed hawkish Fed signals, a 19-month high for the dollar and swings in major technology and retail stocks.
Major currency pairs, 18 November 2026
| Currency pair | Rate | Daily change | Key market context |
|---|---|---|---|
| EUR/USD | 1.0969 | -0.42% | Slid to a 19-month low, testing a major 18-year technical support zone near 1.0900–1.0960 |
| USD/JPY | 159.29 | ~0.00% | Held steady just below 160.00 amid Bank of Japan intervention concerns |
| GBP/USD | 1.3146 | -0.53% | Touched fresh 2026 lows around 1.3140 on broad dollar demand and softer UK rate-hike bets |
| USD/CHF | 0.8433 | +0.53% | Reached a 6-month high as the franc weakened with other European currencies |
| USD/CAD | 1.4338 | +0.36% | Extended its rally toward yearly highs as US yields climbed |
| AUD/USD | 0.6712 | -0.44% | Pressured by broad greenback strength and global equity jitters |
| NZD/USD | 0.5488 | -0.12% | Near multi-year lows, but relatively resilient against other majors |
United States
- Mixed index performance: The S&P 500 fell 0.2% (closing around 7,324, its fifth straight loss and below its 200-day moving average). The Dow dropped 1.1% (about 561 points to 50,198), while the Nasdaq edged up 0.4% to 24,430 to end a four-day slide.
- Fed and macro pressure: October FOMC minutes and comments from Fed Governor Christopher Waller kept markets focused on the risk of another December hike, while 10-year Treasury yields hovered near 5.10%.
- Sector winners and laggards: Cybersecurity rallied (Palo Alto Networks up ~10%, CrowdStrike up ~8%) and Target gained ~4% on strong quarterly sales. Managed health insurers (UnitedHealth down ~10%, Humana down ~13%) and miners (Freeport-McMoRan and Newmont down over 6%) fell sharply.
- Dollar and yields: The dollar climbed to a 19-month high on tightening financial conditions and repriced rate expectations, while Treasury yields eased alongside falling oil.
- Tech, AI and corporate news: Nvidia erased initial post-earnings gains to finish down 2.9% amid continuing uncertainty after co-founder Jensen Huang’s departure. Anthropic priced its IPO at $83 a share, above its $70–$78 range, and retailers such as Target and TJX drew attention ahead of Walmart’s earnings.
Global forex drivers
- Hawkish Fed bets: Rising inflation readings and Governor Waller’s call for a 50-bps hike reinforced expectations of tighter US policy.
- Global rate backdrop: Elevated inflation in the UK (near 3.6%) and Japan (core CPI near one-year highs) kept central bank divergence and intervention risks in focus across majors and crosses.
- Cross-asset pressure: Dollar strength and rate-hike repricing weighed on gold (XAU/USD), which slipped below its multi-day range near $3,807.53.
Europe
Figures as at · Market data for 18 November 2026, as reported in this brief
European markets closed broadly lower for a third straight session as plunging commodity prices, hot inflation data and central bank warnings weighed on sentiment.
Key market drivers and sector movers
- Broad pullback: The STOXX 600 slid 1.03% to 644.05, its third consecutive loss, and London’s FTSE 100 fell 1.3% as commodity stocks weighed.
- Corporate movers: Alstom dropped 7.2% after a net loss of €822 million. Deutsche Bank fell 3.1%, extending Tuesday’s slump after a major leak of internal records. Experian gained 1.7% after beating first-half revenue estimates and announcing a $500 million buyback.
- Commodity and energy drag: Miners dropped 4.7% as copper hit a seven-month low (Glencore and Aurubis fell over 5%), and oil stocks slipped 2.1% with lower crude and a drop in TotalEnergies.
- AI and IPO caution: European tech pared early gains as investors weighed AI valuations and a potential liquidity draw ahead of Anthropic’s listing. Reports that ECB policymakers will discuss raising bank minimum reserve requirements added to the liquidity focus.
Macroeconomic and policy developments
- ECB financial stability warning: The ECB’s semi-annual Financial Stability Review, released on 18 November, warned that stretched AI valuations — backed by over $4 trillion in off-balance-sheet debt commitments among big tech firms — carry parallels to the dotcom and subprime bubbles, and flagged sovereign debt imbalances and geoeconomic tensions.
- Accelerating inflation: Eurozone annual inflation rose to 4.0% in October (from 3.8% in September). UK inflation accelerated to 3.6% (from 3.5%), slightly below the 3.7% consensus.
- EU funding for Ukraine: The European Commission proposed a new €45 billion ($50 billion) loan package for Ukraine for 2027, financed by EU debt issuance backed by budget headroom, though it faces political hurdles in wider budget talks.
- Currencies: A broad rally pushed the US Dollar Index to a 19-month high above 103.50; the euro slipped to around $1.0963 and sterling to $1.3140.
Asia
Figures as at · Market data for 18 November 2026, as reported in this brief
Asian markets traded mixed and cautiously as investors weighed hawkish central bank signals, AI sector volatility and regional data.
Equities and AI sentiment
- Mixed regional performance: Early gains on Nvidia’s stronger-than-expected Q3 revenue ($115.8 billion) and upgraded guidance narrowed or reversed amid doubts over the AI investment cycle. SK Hynix and Samsung Electronics helped lift the Kospi on relative value buying, while Tokyo and Taipei held modest gains.
- Hong Kong and Australia slip: The Hang Seng fell 0.91% to 23,294.75 on chip restrictions and tech pressure, and the S&P/ASX 200 lost 0.69% to 8,821.80.
- Anthropic IPO: Markets watched Anthropic price its IPO at $83 a share, above its $70–$78 marketed range, ahead of its Nasdaq debut.
Central banks and economic data
- Bank of Japan: Governor Kazuo Ueda reiterated readiness to keep raising rates, keeping a possible hike at the 17–18 December meeting in focus. Japanese exports reached a record ¥11.8 trillion (+20.5%) on AI chip demand.
- Indonesia and Australia: Bank Indonesia hiked for the fourth time this year to support the rupiah. Australian unemployment rose to 4.7%, the highest since 2021, after the RBA’s earlier hike to 4.85%.
- Currencies and commodities: The dollar stayed firm, while the Indian rupee opened at ₹93.30 on a three-day rally. Metals slid on the stronger dollar and Chinese demand concerns, and oil eased on rising US inventories despite Middle East supply risks.
Commodities
Figures as at · Prices for 18 November 2026, as reported in this brief
Commodities retreated across the board on a stronger dollar, hawkish Fed rate-hike expectations and rising supply inventories.
Commodity market summary, 18 November 2026
| Commodity | Benchmark / contract | Closing / spot price | Daily change | Key market driver |
|---|---|---|---|---|
| WTI crude oil | NYMEX futures | $83.26 / bbl | -3.20% | Larger-than-expected 3.4M bbl US inventory build |
| Brent crude oil | ICE futures | $91.95 / bbl | -1.28% | Oversupply forecasts outweighing Strait of Hormuz tensions |
| Gold | Spot / COMEX Dec | $3,728.30 – $3,755 / oz | ~-3.0% to -3.5% | Hit 14-month lows on Fed rate-hike signals |
| Silver | Spot / COMEX Dec | $45.74 – $47.36 / oz | ~-3.0% to -5.3% | Broad precious metals sell-off and rising real yields |
| Copper | LME 3-month | $12,770 / t | -3.50% | Fifth consecutive loss on slowing Chinese demand |
| Wheat | CBOT Dec futures | $5.70 / bu | -4.24% (-25¼¢) | Stronger dollar and improved winter crop ratings |
| Corn | CBOT Dec futures | $4.35½ / bu | -2.52% (-11¼¢) | Technical selling, harvest progress and weaker crude |
| Soybeans | CBOT Jan futures | $12.16¾ / bu | -0.71% (-8¾¢) | Fund selling and a sharp drop in soybean oil (-2.25¢) |
Africa
Figures as at · Market data for 18 November 2026, as reported in this brief
African markets closed mostly lower, weighed by falling gold, Fed rate-hike expectations and broad selling across major exchanges, alongside regulatory and venture capital milestones in East Africa.
African equities and indices, 18 November 2026
| Exchange / index | Closing level | Daily change | Key drivers and movers |
|---|---|---|---|
| South Africa (JSE All Share) | 110,616 | -0.77% | Third straight decline as gold and mining stocks slumped; Southern Sun rose on a 39% jump in H1 adjusted headline earnings per share |
| Nigeria (NGX All-Share) | 248,396 | -0.37% | Dragged by a 10.00% drop in Aradel Holdings, though McNichols Consolidated and DEAP Capital gained 10.00% |
| Kenya (NSE All Share / NASI) | 240.57 | -0.14% (-0.33 pts) | Mixed session: NSE 20 (+0.3% to 4,177.38) and NSE 25 (+0.2% to 6,828.66) rose; East African Portland Cement led gainers while Safaricom dipped on heavy volume |
| West Africa (BRVM Composite) | 503 | -1.98% | Steepest drop among major regional indices amid broad selling |
| Tanzania (DSE All Share) | — | +0.53% | Outperformed regional peers despite a 14.15% drop in TOL Gases |
| Zimbabwe (ZSE All Share) | 492 | -1.41% | Heavy losses in Zimre Holdings (-13.92%) and Cafca (-13.33%) |
Currencies, commodities and fixed income
- Rand and yields: The rand slumped as much as 1.9% to an eight-month low on political uncertainty after municipal elections and hawkish Fed commentary. South Africa’s 10-year yield climbed roughly 9 basis points to a four-week high of 8.91% ahead of the central bank’s decision.
- Gold retreat: Spot gold dropped below $3,800 an ounce for the first time since September 2025, triggering sell-offs across African precious-metal miners, including a 9.63% drop in London-listed Pan African Resources.
Venture capital
- First Circle Capital: The pan-African venture firm announced the $26 million final close of its Africa Fund I on 18 November, targeting pre-seed and seed startups in insurtech, regtech, climate fintech and financial infrastructure in Nairobi, Kampala, Casablanca and Cape Town.
Nairobi Securities Exchange
Figures as at · Nairobi Securities Exchange session data for 18 November 2026, as reported in this brief
Kenyan markets saw major regulatory approvals at the bourse alongside mixed equity trading.
Capital markets and listings
- CMA approvals: The Capital Markets Authority approved the cross-listing by introduction of Mauritius-listed Africa Eats Ltd on the NSE Main Investment Market Segment, and the Leo Dividend Exchange Traded Fund by Tradiam Asset Managers, which tracks dividend-paying NSE stocks and pays distributions quarterly.
Market performance, 18 November 2026
- Market capitalisation: KSh 4,067.26 billion (-KSh 5.61 billion).
- Indices: A mixed close: the NSE 20 gained 13.53 points to 4,177.38, the NSE 25 rose 16.25 points to 6,828.66 and the NSE 10 added 4.71 points to 2,670.66, while NASI dipped 0.33 points to 240.57. The Banking Sector Index edged up 0.32 points to 284.28.
- Trading activity: Equity turnover was about KSh 712.88 million across 16.45 million shares and 11,577 deals. Safaricom led turnover; East African Portland Cement was the top gainer and Crown Paints Kenya led decliners.
Rates and banking
- CBK key rates: The Central Bank Rate stood at 8.75% (discount window 9.25%), with KESONIA at 8.7503% as of 17 November 2026.
- Co-operative Bank: After nine-month net profit rose 27.2% to KSh 27.43 billion, its KSh 1.50 interim dividend has a books closure of 25 November 2026 ahead of a 4 December payout.
Kenya Corporate News
Figures as at · As reported in this brief
Corporate and economic news was dominated by product launches in insurance and tech, significant energy deals and President William Ruto’s fourth State of the Nation Address.
Corporate and sector highlights
- Insurtech and microfinance: VisionFund Kenya and Turaco unveiled a nationwide insurance programme under the FAST initiative for chamas (savings groups), covering hospitalisation and death, aiming to reach over 100,000 members over three years.
- Digital commerce and SMEs: TikTok and the International Chamber of Commerce launched the Digital Commerce Labs in Nairobi to train small businesses on AI-powered e-commerce tools; officials urged TikTok to pilot TikTok Shop in Kenya.
- Energy and power: Kenya signed a KSh 90 billion deal with a Greek firm to develop a floating power plant in Mombasa. NTV Kenya reported on the commencement of crude oil drilling in South Lokichar.
- Brand recognition: Citizen TV was recognised as Kenya’s top brand at the Jaffer Awards.
State of the Nation Address
- Capital mobilisation: The National Infrastructure Fund has been capitalised with KSh 340 billion to attract pension funds, institutional investors and proceeds from divesting mature public assets; a Sovereign Wealth Fund is also proposed.
- Pension growth: Monthly NSSF contributions have grown sixfold since 2023 to over KSh 8.5 billion, taking the fund to KSh 850 billion as of November 2026, with a KSh 1 trillion target by June 2027.
- Infrastructure and energy: The government targets an additional 10,000 MW of generation capacity, major road dualling (including the Nairobi–Mombasa highway) and extending the SGR from Naivasha to Malaba.
- Taxpayer engagement: KRA Board Chairperson Ndiritu Muriithi announced stepped-up nationwide taxpayer forums to resolve compliance bottlenecks and widen the tax base.
Real Estate
Figures as at · As reported in this brief
- Affordable housing allocation gap: In his State of the Nation Address, President Ruto said only 18,000 Kenyans have been allocated homes out of more than 1.37 million registered Boma Yangu applicants, with over 313,000 units under construction across all 47 counties.
- Jobs, Jua Kali and related facilities: The housing programme has generated over 1.1 million jobs and set aside more than Sh61 billion in orders for Jua Kali artisans, with plans for student hostels for 170,000 learners and 600 modern markets budgeted at Sh57 billion.
- Kenya’s REIT market lags peers: A new report shows Kenya’s REIT market ranks fourth in Africa at a market capitalisation of $247.6 million, behind South Africa ($18.9 billion), Morocco ($667.4 million) and Zimbabwe ($270.9 million). Analysts blame low pension-fund uptake and high government-securities returns; the CMA has moved to cut the minimum REIT subscription from KSh 5 million to KSh 100,000.
- Mortgage scheme for TSC staff: The National Treasury and the Teachers Service Commission unveiled draft regulations for a Car Loan and Mortgage Scheme Fund providing subsidised housing and vehicle finance for TSC Secretariat employees.
- NLC clarifies Sh21 billion land payouts: After reports citing World Bank concerns over valuation delays, the National Land Commission said compensation is under way for 1,280 project-affected persons along the Isiolo–Kulamawe–Modogashe corridor under the Horn of Africa Gateway Development Project.
- Income REIT in the NSE pipeline: As the CMA approved new NSE listings on 18 November, market updates noted that the Park Inn Income REIT remains among the key pending transactions in the exchange’s capital-raising pipeline.
- Garden City Mall scrutiny: HapaKenya examined corporate tax disputes and offshore holding structures tied to Nairobi’s Garden City Mall, detailing how institutional stakes are routed through Mauritius-based entities.
Kenya Snapshot
Every figure below carries the date it describes and who published it. Where this brief did not restate a value, the figure Serrari already publishes is carried over with its own effective date — it is never re-dated to today. Most recent figure in this snapshot: .
Macro
Inflation
7.3%
Year-on-year headline CPI.
As at
KNBS CPI, Oct 2026 — carried over from Serrari's published macro dataGDP growth
5.3%
Real GDP, year-on-year. Not restated in this brief.
As at
KNBS quarterly GDP (owner, 2026-09-14), Q1 2026 — carried over from Serrari's published macro data
Foreign exchange
USD / KES
130.63
As at
As published on this brief’s artwork
Equities
NSE All-Share (NASI)
240.57
-0.14%
As at
Nairobi Securities Exchange, as reported in this briefNSE 20-Share
4,177.38
+13.53 pts
As at
Nairobi Securities Exchange, as reported in this briefNSE 25-Share
6,828.66
+16.25 pts
As at
Nairobi Securities Exchange, as reported in this briefNSE 10
2,670.66
+4.71 pts
As at
Nairobi Securities Exchange, as reported in this briefNSE Banking Index
284.28
+0.32 pts
As at
Nairobi Securities Exchange, as reported in this brief
Rates
Central Bank Rate
8.75%
Discount window 9.25%
KESONIA (overnight interbank)
8.7503%
As at
Central Bank of Kenya, as reported in this brief
At a glance
- 1The CMA approved the cross-listing by introduction of Mauritius-listed Africa Eats on the NSE Main Investment Market Segment, and Tradiam’s Leo Dividend ETF, which tracks dividend-paying NSE stocks and pays quarterly.
- 2Wall Street ended mixed: the Nasdaq rose 0.4% to end a four-day slide while the S&P 500 fell for a fifth session and the Dow dropped 1.1%, as Fed minutes and Governor Waller kept a December hike in play and the dollar hit a 19-month high.
- 3In his State of the Nation Address, President Ruto said only 18,000 of 1.37 million Boma Yangu applicants have been allocated homes, with over 313,000 units under construction, and put the NSSF at KSh 850 billion.
Sources
- Serrari Group desk compilation, 19 November 2026; Markets Snapshot – 18 November 2026
- Central Bank of Kenya — indicative exchange rates
- Nairobi Securities Exchange — daily market statistics
- Serrari published Africa macro data